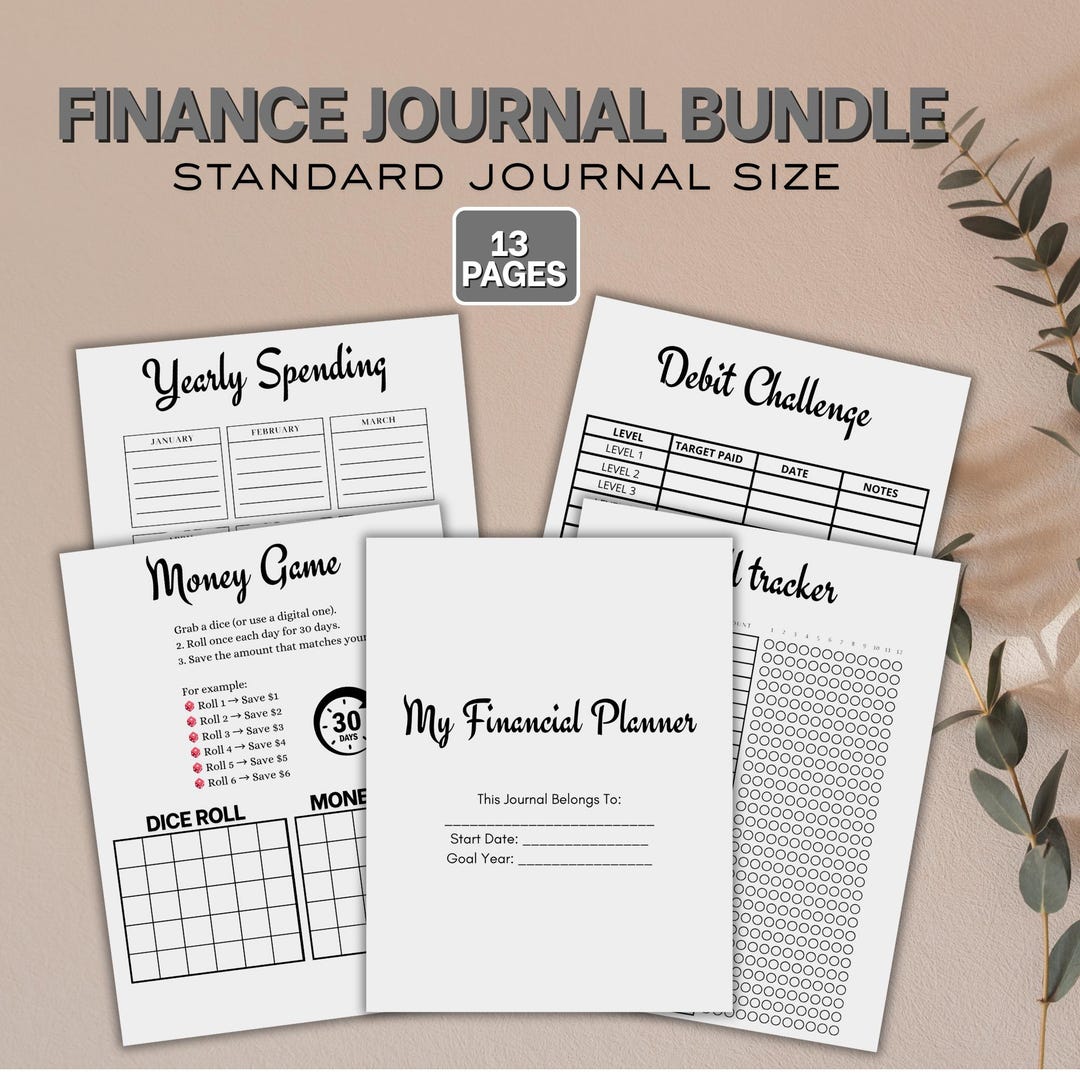
Building Your Own Finance Tracker Without the Subscription Fee
I spent three years using a $15/month budgeting app before I finally built my own system and never looked back. The short version: Diy Finance Journal Pages are printable, customizable spreadsheets or PDFs you design to track every dollar coming in and going out. They live in your hands rather than some cloud server. Let me walk you through how to actually make one that works. At their core, these are just structured pages you create to log income, expenses, savings, and sometimes debt payoff progress. Some people use a blank notebook and hand-draw tables. Others build Excel sheets with formulas. A few dozen templates exist online you can download and modify for free. The point is you control the categories, the layout, and how often you update it. I stopped trusting apps the day mine auto-categorized my grocery run as "dining out" for the fourth time in a row. That alone cost me sleepless nights reclassifying everything. My first attempt at building pages from scratch took about six hours over two weekends. After that, every month of tracking has been faster than any app I ever used.
The Basic Structure That Actually Works
Your finance journal needs four sections at minimum: daily spend log, weekly totals, monthly summary, and a recurring bills tracker. Everything else is decoration until you actually use it consistently for three months. Here is the structure I settled on after burning through two failed versions. I print each section on standard letter paper, use a single notebook, and refill pages quarterly. You can do this in Google Sheets if you prefer digital, but the printer method forces you to engage with the numbers physically, which changes how you perceive spending.
Setting Up Diy Finance Journal Pages
Start with a spreadsheet. Type these column headers in row one: Date, Category, Description, Outflow, Inflow, Balance. That is it. Add a second tab labeled "Recurring Bills" with columns for Bill Name, Due Date, Amount, and Status. Third tab gets a monthly summary with row labels for your actual categories, which you define based on where your money actually goes. The key insight nobody mentions: your categories should match your bank statement categories, not your ideal spending habits. If your Chase app buckets everything under "Shopping" but your spending is really split between Target, Amazon, and local boutiques, create three subcategories. Otherwise your monthly review becomes a guessing game.
Get the Full Details

My Specific Workaround for the Receipt Chaos Problem
About eight months into my journaling routine, I hit a wall. I had 47 unreconciled transactions in a single month. Small purchases, cash spends, tip discrepancies, the usual mess. My spreadsheet had the right totals but the wrong descriptions and I could not figure out which $3.50 charge was which coffee shop. The fix was ridiculously simple. I stopped trying to remember and started photographing every receipt immediately with my phone. Then I used a free app called DigiLogger to OCR scan them in batch and export the data as CSV, which I imported directly into the main sheet using a VLOOKUP formula against the transaction date and amount. That cut my monthly reconciliation time from about 45 minutes down to roughly 8 minutes. The first month of setup took two extra hours but paid for itself within six weeks.
Counter-Intuitive Things I Learned the Hard Way
First, more columns do not equal better tracking. I once had twelve columns across seven tabs and barely touched it twice in three months. Simplicity wins. Two columns for amounts, one for category, one for notes. That is the maximum useful complexity for 90% of people. Second, the monthly summary tab should be your only decision-making page. Everything else feeds into it. If you have to flip between five different tabs to understand whether you spent too much, the system has already failed you. I used to track investment contributions, emergency fund deposits, and side hustle income separately. I consolidated everything into one summary tab and actually started making decisions instead of just recording data. Third, and this one surprises most people: your journal should be updated the same day the transaction happens. Waiting until Sunday evening to enter the week's spending means you have already forgotten half of it. I learned this when my Sunday sessions ballooned from fifteen minutes to over an hour because I could not remember whether that $12 charge was lunch or gas. Same-day entry takes about three minutes per transaction.
Where This Approach Completely Falls Apart
Diy Finance Journal Pages do not work if you want automated bank syncing. Every entry is manual. If you have twenty to forty transactions per week, plan for roughly twenty to thirty minutes of entry time, usually spread across the week. This is not a scalable system for high-volume accounts. They also do not work if you need real-time net worth tracking. You have to calculate that yourself by subtracting total expenses from total income at the end of each period. The process is slower than any automated tool, though arguably more accurate because you are forced to examine each line item. For people with complex joint finances, multiple business accounts, or international transactions, the DIY route gets heavy fast. In those cases, a hybrid approach makes more sense. Use a service like YNAB or Monarch Money for the sync-heavy stuff and maintain a separate journal for whatever those platforms miss. I do this myself for my freelance income, which has too many irregular categories for a single spreadsheet to handle cleanly.

Practical Next Steps
If you want to start today, grab a free template from a site like Template.net or search for "budget tracker spreadsheet free" on Google. The ones with the best reviews are usually older designs with fewer bells and whistles. Avoid anything with conditional formatting, charts, or dashboards in month one. You can add those later when the habit is locked in. Print the first two weeks of pages. Fill them out. Review at the end of the month and adjust the categories to match reality. Then print another month. After three months you will know exactly what your journal needs, and you can rebuild it tighter than anything you started with. The entire system costs about four dollars a year in paper and ink if you print monthly. It takes about twenty minutes per week to maintain once you are comfortable. And you own the data, which is more than most people can say about their subscription budgeting tools.


