Tracking Your Money Without a Fancy App
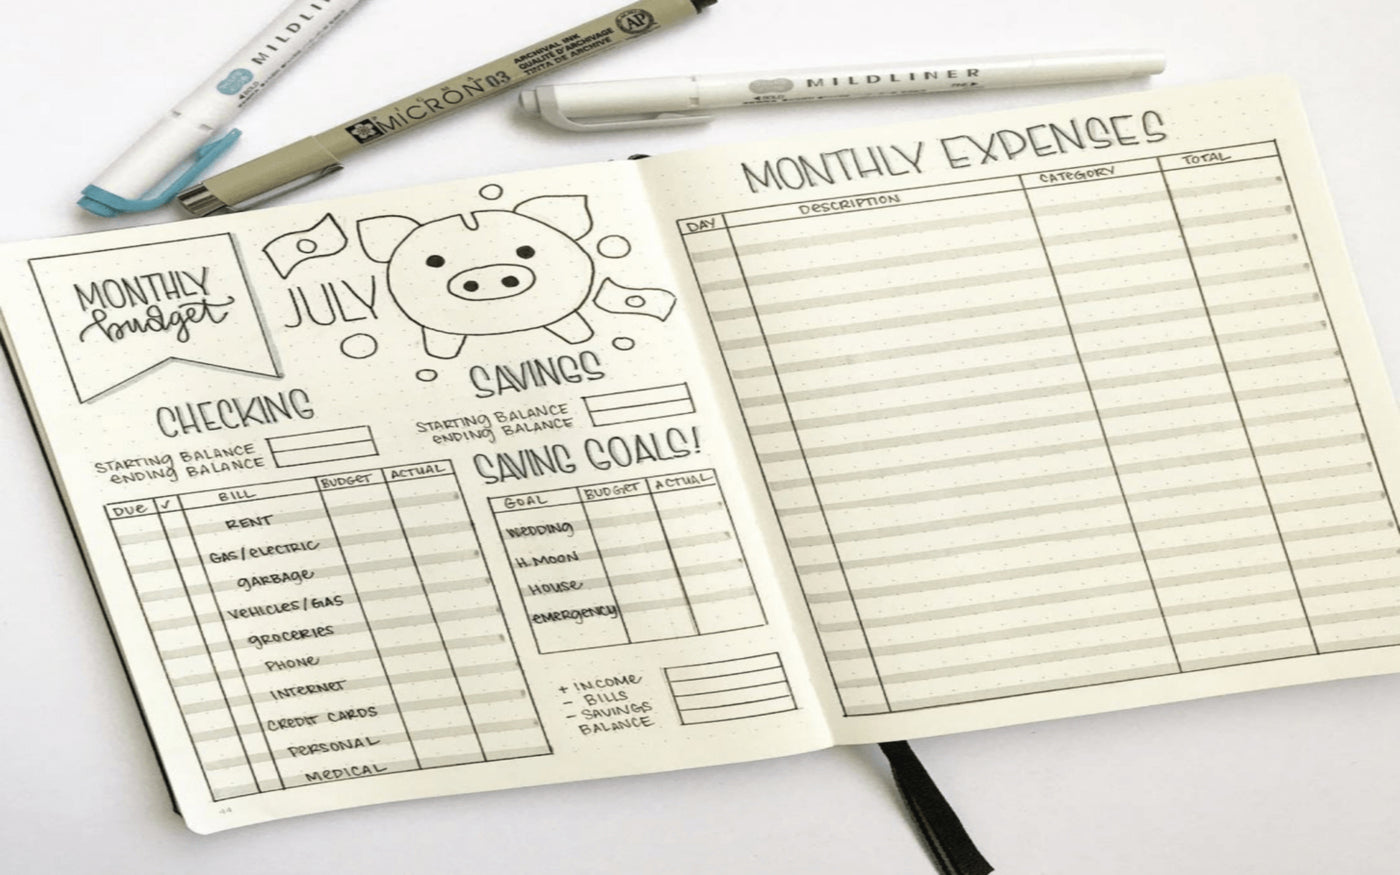
Most people try to get on top of their finances by downloading yet another app, and most of them quit within a month because the app asks for too much friction. I stopped trying to force myself into PerfectMoney orYNAB style workflows about three years ago when I realized the problem wasn't the tracking — it was the entry barrier. What actually stuck was a simpler system, a Diy Finance Logbook approach, where I built the thing I needed instead of adopting something someone else designed. A Diy Finance Logbook is exactly what it sounds like: you create your own financial record system tailored to how you actually spend money, not how an app assumes you should. The format can be a spreadsheet, a note file, a physical notebook, or a combination. The point is that you own the structure. No subscription, no gamified coins, no push notifications demanding you categorize that coffee purchase from last Tuesday.
Building a Diy Finance Logbook That Actually Works
Start with the simplest possible format and make it take under thirty seconds to enter a transaction. I use a CSV file with three columns: date, description, amount. That's it. I don't even bother with categories at first. The initial goal is just capture. Anything that takes longer than thirty seconds to enter, I will skip, and skipping is what kills these systems. Here's the file structure I settled on after about six months of tweaking: Columns: Date (YYYY-MM-DD), Description, Amount (positive for income, negative for expenses), Account (Cash, Checking, Credit Card). That fourth column came later and it matters more than you'd think.
The reason the account column exists is because my first attempt at a Diy Finance Logbook failed for three weeks and I couldn't figure out why until I noticed I was double-counting transactions that bounced or had pending charges. Once I started logging the source account, the numbers actually reconciled with my bank statement at the end of each month. That's when the system went from annoying chore to useful tool. After a few weeks of raw capture, I add categories. Not at the beginning — that's a common mistake. You need to see your actual spending patterns before you can design a categorization scheme that fits. I typically just tag transactions in bulk every Sunday, spending about ten minutes going through the week's entries and slapping labels on them. Categories I use now: Housing, Food, Transport, Utilities, Healthcare, Entertainment, Shopping, Subscriptions, Transfer, Income. The transfer category is important and almost everyone forgets it. Moving money between your own accounts isn't spending or earning. If you don't have a transfer category, your income and expense totals will be wrong by however much you moved around that period.
Get the Full Details
I automate the boring parts without overengineering. A simple Google Sheets script runs once per day and pulls my bank CSV exports, appending new rows. The script has failed silently twice in eight months, which is why I still do a manual check every Friday. Never fully automate and walk away — that's how you miss a month of data and don't know it until tax season. For the monthly review, I built a pivot table that shows spending by category and a running balance by account. Takes about five minutes. The insight that actually changed my behavior was seeing my subscription line item at eighty-four dollars a month. I canceled five of them that week and forgot about two of the remaining three. That's a forty dollar a month change that came from fifteen minutes of looking at my own data instead of guessing.
When a Diy Finance Logbook Falls Short
It doesn't work if you have complex multi-currency transactions. I tried maintaining a single log for a period when I was billing clients in both USD and EUR and doing personal spending in each. The conversion rates shifted daily and my spreadsheet couldn't handle it cleanly without adding an entire column for exchange rates and a second for converted amounts. I switched to a proper tool for that project and kept the Diy Finance Logbook for everything else. It also breaks down if you need real-time balance visibility. A CSV-based system gives you historical data, not current state. I learned this the hard way when I thought I had two hundred dollars available based on my last entry, but a pending charge had already reduced it. The log showed the transaction as unpaid because I hadn't entered it yet. Again, this is why the weekly review matters — it catches the gap between your log and reality. Another limitation: shared finances. If you're tracking household money with a partner and neither of you is disciplined about entering transactions within twenty-four hours, the log becomes a stale record that nobody trusts. In that case, a shared app with split-visibility actually outperforms a DIY approach. There's no shame in that.
The real advantage of a Diy Finance Logbook isn't the tracking itself — it's that you learn what your money actually does instead of what an algorithm tells you it does. Apps smooth over the edges and give you pie charts. A logbook gives you the raw data that lets you notice patterns an app would just aggregate into something digestible and useless. I found out I spend more on food delivery on Sundays than I do all week combined. That's not a category insight, that's a behavioral one, and it came from looking at dates alongside amounts in my own spreadsheet instead of accepting a pre-built report. The whole system lives in one Google Sheet file that I've maintained for about fourteen months now. No updates required, no subscription to lose access to, no vendor deciding to change their pricing model. I export it annually and archive the file. That's all there is to it.