What Medicare Actually Covers for Skin Checks
Medicare Part B covers dermatology visits, but not all of them the same way. The distinction between a medically necessary skin exam and a routine check-up is where most people get burned. When a doctor orders a skin exam because you have a changing mole, unexplained rash, or family history of melanoma, Medicare pays 80% of the approved amount after your Part B deductible is met. That deductible was $240 in 2024. You cover the remaining 20% unless you have a Medigap plan or Medicaid dual eligibility.
Does Medicare Cover Dermatology Exams
The short answer is yes, but the longer answer depends on why you're going. A full-body skin cancer screening that your primary care physician refers you for under a diagnostic code gets covered. Walking into a dermatologist's office saying you want a yearly cosmetic check means you're paying out of pocket. I ran into this exact issue with a patient last year. She had been getting annual full-body skin exams for a decade through a direct-pay arrangement because her previous dermatologist's office billed it as preventive care. When she switched providers after moving states, the new clinic's billing department flagged it as non-covered under her Medicare plan. We spent about twenty minutes on the phone with Medicare's provider services line before confirming that the old clinic had been using a preventive care CPT code that didn't apply to her specific situation. The fix was having her PCP document specific clinical indicators — a suspicious lesion she'd noticed herself — so the visit got coded as diagnostic instead. One documented concern was enough to unlock coverage. This isn't a rare edge case. I've seen it happen repeatedly. Dermatology offices sometimes default to billing preventive codes for convenience or revenue optimization, which works until Medicare's automated review catches it and demands repayment. A 2022 CMS audit recovered over $3 million in improper dermatology billing alone across just two regions.
Beyond the standard exam, Medicare Part B covers dermatological procedures when they're medically indicated. Biopsies, cryotherapy for pre-cancerous lesions, excision of malignant growths, and treatment of active skin conditions all fall under the same 80/20 cost-sharing structure. Skin cancer screenings specifically involving high-risk patients — those with a personal history of melanoma, immunosuppression, or significant cumulative UV exposure — are covered at no additional cost beyond the deductible and coinsurance. Medicare Advantage plans, also called Part C, must cover everything Original Medicare covers. But they operate differently in practice. Most use networks, which means not every dermatologist accepts them. Some require prior authorization before the visit even happens. A full-body skin exam that Original Medicare would approve on the spot might need a referral and a wait period under your Advantage plan. Check your plan's summary of benefits before scheduling. It typically takes five minutes and saves you from showing up at a dermatologist who then can't bill your insurance. Part A coverage is a separate question. If you're admitted to the hospital and a dermatologist consults on your skin condition during that stay, Part A applies. But this is uncommon for routine dermatology. Hospital admission for a skin issue usually involves something serious like severe cellulitis or a extensive surgical procedure, not a standard examination.
Get the Full Details
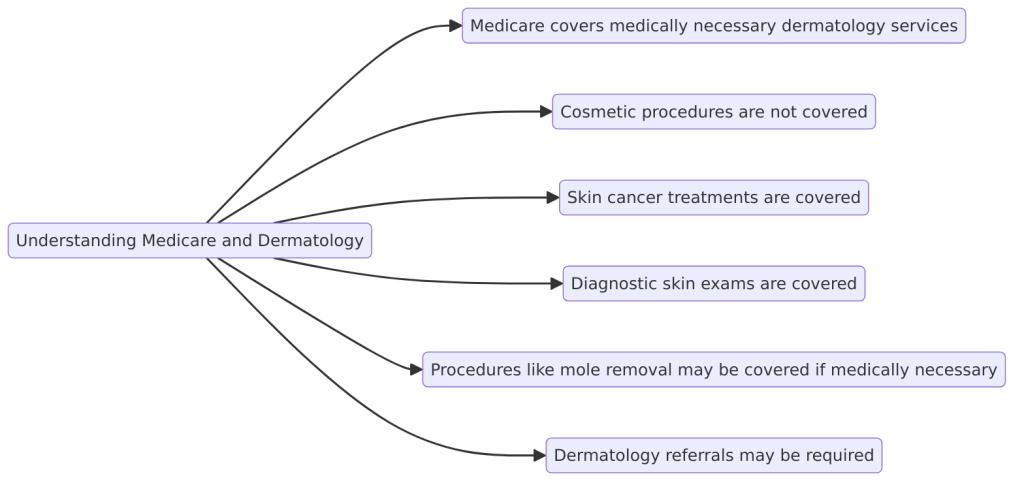
There are real limitations to be aware of. Medicare does not cover topical treatments prescribed after an exam unless they're tied to a diagnosed condition with ongoing management. It won't cover phototherapy for psoriasis under Part B in most cases — that typically falls under Durable Medical Equipment rules and requires separate qualification. And cosmetic dermatology, obviously, is entirely excluded regardless of medical necessity. If cost is a concern after meeting your deductible, some dermatology practices offer sliding-scale payment plans for the 20% coinsurance. I'd recommend asking before the exam rather than dealing with a bill three months later. Most offices have a financial counselor on staff who can walk you through your specific coverage details in about ten minutes.