The Tax Cuts and Jobs Act and everything before it
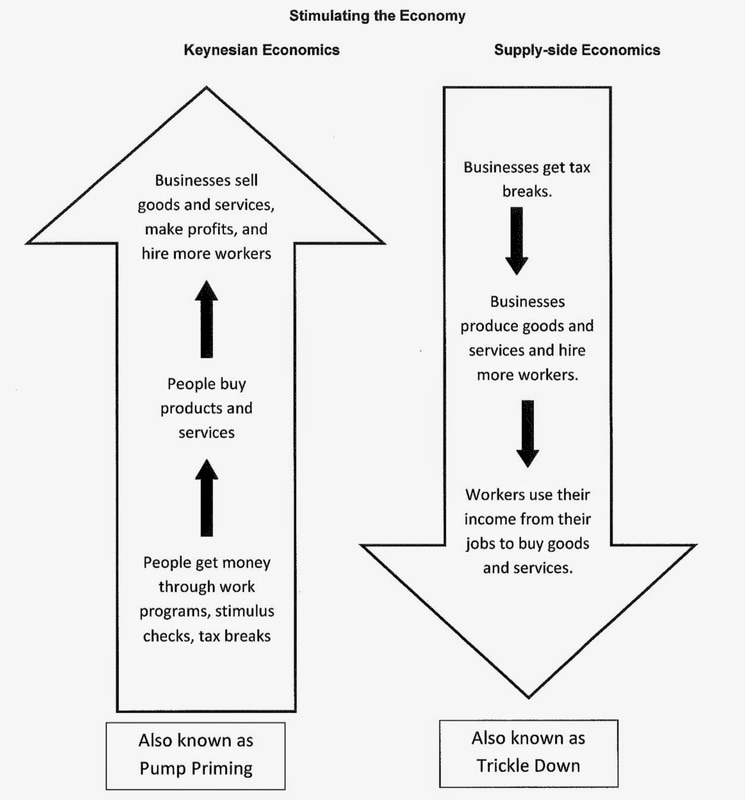
Supply side economics is one of those frameworks that shows up in every policy debate but rarely gets explained in a way that matches what actually happened. The basic claim is simple: cut taxes on businesses and high earners, reduce regulation, and growth follows because investment increases. The Laffer curve gets dragged into every conversation about it. The idea is that at some point, higher tax rates actually reduce revenue because they distort behavior enough to shrink the taxable base. That part isn't entirely wrong, but it gets treated like a law of physics when it's more of a sketch on a napkin. The honest answer depends on what you're measuring and over what time horizon. In the short run, tax cuts tend to boost GDP growth because disposable income rises and business investment picks up. That's straightforward macro. But the revenue side is messier. The 1981 Reagan tax cuts were sold on supply-side logic and were followed by a severe recession in 1982, partly because the Fed was simultaneously crushing inflation with aggressive rate hikes. Revenue actually fell in the early years and then recovered as the economy grew out of the downturn. Whether that recovery was caused by the cuts or just by monetary policy normalizing is still debated among economists. The 2001 and 2003 Bush tax cuts showed a different pattern. They were accompanied by an increase in the deficit that never fully got paid back through growth. The Congressional Research Service looked at this and found that the growth effects were modest at best, well below what the supply-side argument predicted. The 2017 Tax Cuts and Jobs Act did something interesting: corporate tax revenue actually increased in the first two years because the statutory rate dropped from 35 percent to 21 percent but the broader tax base expanded through limitations on deductions and the addition of a GILTI provision on international earnings. Revenue went up for three years, then started falling as the temporary provisions expired and the economy adjusted. The deficit widened by roughly a trillion dollars annually, according to the CBO.
There's a reason I bring up the 2017 act specifically. I was working on a project evaluating the impact of the corporate rate change on a mid-market manufacturing firm. The company had been structuring its operations around the old depreciation rules and the 35 percent rate. When the rate dropped, their effective tax liability shifted dramatically, but not in the way their CFO had projected. They'd assumed the full benefit would flow to equity holders. It didn't. A significant portion was absorbed by changes in state tax allocations, the new limitation on interest deductions under section 163(j), and the transition tax on repatriated earnings. The net benefit to capital expenditure was maybe 40 percent of what the supply-side argument suggested they should get. I learned to never take a company's own projection of tax benefit at face value after that. The actual numbers are always lower because compliance costs, state-level interactions, and international provisions create drag that theoretical models don't capture well.
What the models miss
Most supply-side analyses use dynamic scoring, which attempts to model how taxpayer behavior changes in response to rate shifts. The problem is that the behavioral elasticities baked into those models are highly uncertain. A 1 percent change in the elasticity assumption can swing revenue projections by hundreds of billions over a decade. The Treasury Department's own historical record on dynamic scoring accuracy has been poor. They consistently overestimated growth and underestimated the deficit impact from tax cuts. Another thing people don't talk about enough is the distributional question. Supply-side theory assumes that tax cuts at the top cascade down through investment and job creation. What actually happens is that a disproportionate share of the benefit goes to capital owners, and the labor share of income tends to fall or stay flat during these periods. The 1980s saw the beginning of a long decline in labor's share of GDP that accelerated through the 1990s and 2000s. Tax policy isn't the only factor, but it's a real one. Wage growth for middle-income workers didn't keep pace with productivity growth after the major tax cuts of the 2000s, which is the opposite of what the supply-side promise would predict. There's also the question of what gets cut when you cut taxes. The 2017 act didn't just reduce rates. It capped the state and local tax deduction at ten thousand dollars, limited the mortgage interest deduction, and reduced the estate tax exemption. Those changes hit different groups in different ways. The SALT cap, for example, was projected to raise revenue but also had the unintended consequence of pushing some high-tax states toward structural fiscal stress. New Jersey and New York have both floated workarounds, including potentially treating SALT payments as business expenses, which the IRS has pushed back on. This is the kind of second-order effect that supply-side models don't really account for.
Get the Full Details

When it actually works and when it doesn't
Supply-side policies tend to show stronger results in countries with high marginal tax rates and significant tax avoidance capacity. The 1960s Kennedy cuts, for instance, were justified on similar logic and did coincide with strong growth, though the baseline was already recovering from a recession. The key difference there was that the U.S. top marginal rate was in the 90 percent range, which creates real distortion. Cutting from 91 percent to 70 percent moves the needle more than cutting from 37 percent to 21 percent. Diminishing returns matter here. Most developed economies are already in a range where further corporate rate cuts have minimal impact on investment decisions. The approach also works better when paired with spending discipline. The 1980s showed what happens when you cut taxes and don't cut spending: the deficit balloons, and you end up with the same problems you'd have had without the cuts, just with a larger debt service burden. The 1990s surplus was partly the result of the 1993 tax increases that reversed some of the 1980s cuts, combined with spending restraint. Supply-side economists criticized the 1993 increases at the time. The revenue went up anyway, which undermines the strict Laffer curve argument for a reason. International coordination is another factor that gets ignored. In a globalized economy, cutting corporate tax rates can trigger a race to the bottom. Ireland at 12.5 percent, Hungary at 9 percent, and now the OECD's minimum corporate tax floor of 15 percent show the tension between competitive rate-cutting and the need for a baseline. The U.S. 2017 cut to 21 percent was partly a response to that pressure. But the base erosion and anti-abuse provisions that came with it, like BEAT and GILTI, show how hard it is to cut rates without also strengthening enforcement mechanisms. You can't just lower the rate and expect revenue to hold. The two moves are connected.
I've also seen supply-side arguments applied to individual income tax cuts with similar results. The 2001 and 2003 cuts included reductions in the top marginal rate and in capital gains and dividend tax rates. The argument was that these would pay for themselves through increased investment and economic activity. They didn't. The capital gains tax rate cut in 2003 was followed by a surge in realized capital gains as investors repositioned ahead of the change, but that was a one-time revenue boost, not a sustainable increase. The long-term revenue effect was negative. That pattern of one-time revenue shifts followed by structural declines is common and gets smoothed over in political discourse but shows up clearly in the data.
What to watch if you're evaluating this
Don't look at GDP growth alone. Look at productivity growth, wage growth for median workers, the labor force participation rate, and the deficit. Those four metrics tell you more about whether supply-side policy is actually delivering on its promise than any single headline number. The 1980s had strong GDP growth after the recession, but productivity growth was weak throughout the decade except for a brief spike around 1982-1983. The 2010s had solid GDP growth after the Great Recession, but wage growth was historically flat and productivity growth was sluggish. Tax cuts don't fix structural issues in demographics, education, or technology adoption, and pretending they do is where a lot of the policy analysis goes wrong. If you're looking at a specific tax cut proposal, check the static versus dynamic scoring difference. The CBO and JCT publish both. The dynamic score includes behavioral responses, but the assumptions behind those responses are often opaque. Ask for the elasticity parameters. If they're not disclosed, the score is less useful than you'd think. I've seen analysts rely on dynamic scores that assumed growth elasticities double the historical range without any justification beyond model calibration choices. That's not rigorous analysis. It's just a number with a fancy coat of paint. The bottom line is that supply-side economics isn't wrong in every case, but it's not right in most cases either. It works when marginal tax rates are high enough to create real behavioral distortions, when the economy has slack that can be activated by increased demand, and when the tax cuts aren't immediately offset by spending increases that crowd out productive investment. In the current U.S. environment, with rates already relatively low by historical standards and the economy near full employment, the margin for supply-side growth stimulation is thin. That doesn't mean the policy is pointless. It means the effects are smaller than the rhetoric suggests and the distributional consequences are significant enough to warrant attention that they rarely get.