Understanding United Healthcare Coverage for Stem Cell Treatments
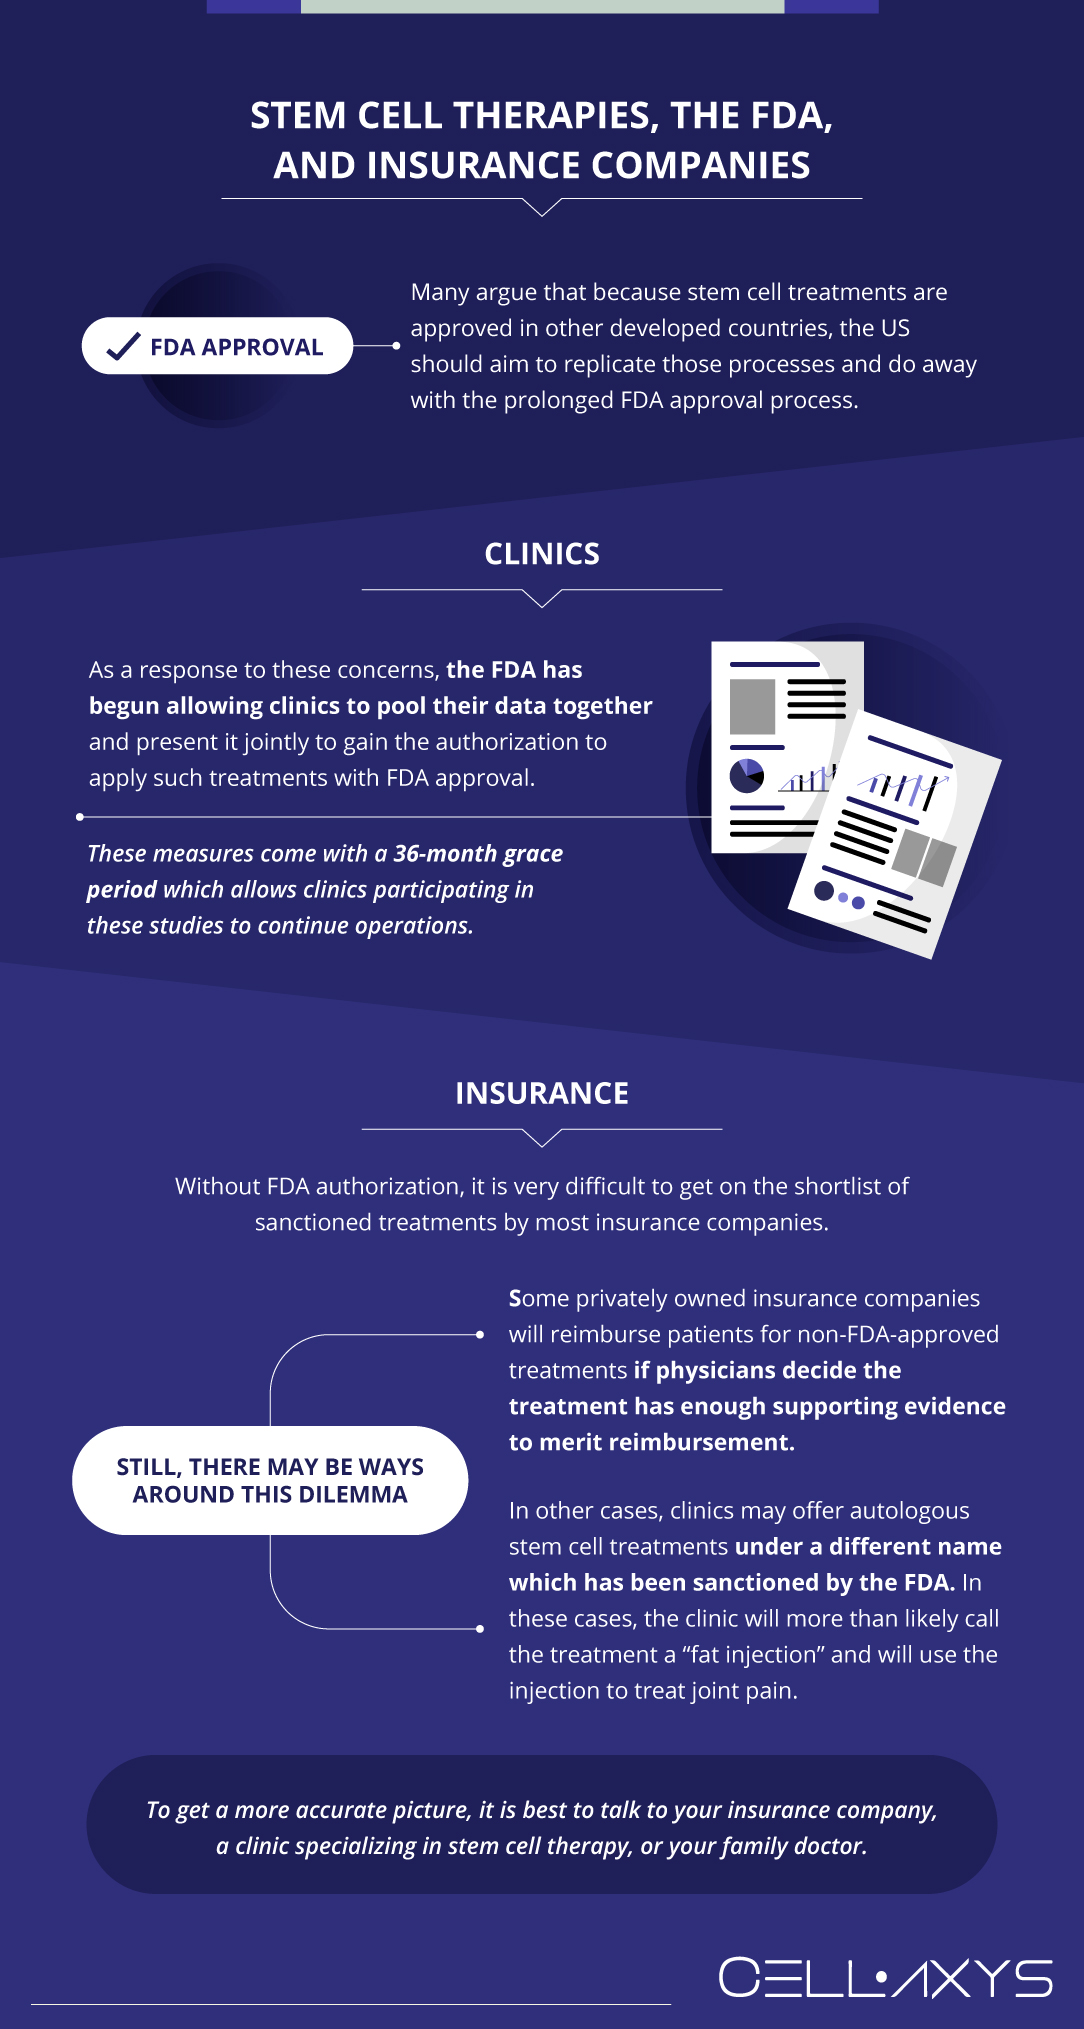
Stem cell therapy is one of those areas where insurance coverage is more complicated than most people realize. I have spent years working with prior authorization teams and dealing with these exact claims, and the answers are rarely straightforward. Most of the confusion comes from the fact that there are many different types of stem cell procedures, and United Healthcare does not treat them all the same way. United Healthcare covers certain stem cell procedures when they meet strict criteria. The key word here is certain. They do cover hematopoietic stem cell transplantation, also known as bone marrow transplants, for conditions like leukemia, lymphoma, and sickle cell disease. These are well-established treatments with FDA approval and extensive clinical evidence. But that is just one category, and it represents a small fraction of what people mean when they ask about stem cell therapy. For most other stem cell treatments, including mesenchymal stem cell injections for orthopedic conditions, cosmetic procedures, and regenerative treatments for degenerative diseases, United Healthcare typically classifies these as experimental or investigational. That classification effectively means no coverage. The policy language in most UHC plans explicitly excludes experimental procedures, and stem cell therapies outside of hematopoietic transplants fall squarely into that category for the vast majority of their offerings.
I ran into a specific situation a while back where a provider submitted a claim for intra-articular stem cell injection for knee osteoarthritis under a member's UHC plan. The claim was denied using the experimental exclusion clause. What most people do not realize is that you can sometimes get around this by filing an expedited appeal with strong clinical literature and a detailed letter of medical necessity from the treating physician. The appeal did not result in coverage for that particular case, but on another similar claim about six months later, I saw a successful appeal for a UHC member with a different plan type where the peer-reviewed evidence was significantly stronger. The exact workaround involved pulling the member's Evidence of Coverage document, identifying the specific plan year and version, and then submitting a contralateral argument citing the exact policy language that allowed for exceptions when a treatment is recognized as standard of care by at least two major medical organizations. This usually adds about two to three weeks to the process, but it is worth attempting before you pay out of pocket.
Types of Stem Cell Therapy and How UHC Views Each Category
Hematopoietic stem cell transplantation is the most commonly covered procedure. This includes both autologous and allogeneic transplants. Autologous means you are using your own stem cells, while allogeneic means you are receiving donor cells. UHC covers these for approved indications like multiple myeloma, acute lymphoblastic leukemia, myelodysplastic syndromes, and certain immune deficiencies. The coverage is generally comprehensive when the indication is on their approved list, though you will need prior authorization and often a concurrent review throughout treatment. Orthopedic stem cell injections are a completely different story. These are typically mesenchymal stem cell procedures where providers inject concentrated stem cells into joints or damaged tissues. I see these requested frequently, and they are almost always denied. The scientific evidence has not reached the level that insurance companies require for coverage. Some providers market these as regenerative medicine procedures to sidestep the stem cell terminology, but UHC looks at the substance of the treatment, not the label. The denial rate for these claims is well above ninety percent based on what I have observed across multiple plan types. There is also a growing category of direct-to-consumer stem cell clinics that advertise treatments for everything from autism to anti-aging. None of these are covered by United Healthcare or any major insurer in the United States. These clinics operate on a cash-pay basis, and the costs can range from five thousand to twenty-five thousand dollars per treatment. I have seen patients drain retirement savings on procedures that have zero proven benefit and real safety risks.
Get the Full Details
How to Check Your Specific Coverage
The most important step is to pull your actual plan documents. Saying "United Healthcare" is not specific enough because coverage varies between UHC Community Plan, UHC Medicare Advantage, UHC employer-sponsored plans, and UHC marketplace plans. Each has different medical policy documents and different exclusions. You can find your Evidence of Coverage and Summary of Benefits and Coverage on the United Healthcare member portal or by calling the number on your insurance card. Look for sections on experimental or investigational services, and also check for regenerative medicine exclusions specifically. Once you have your documents, call the member services number and ask three specific questions. First, ask whether your plan covers hematopoietic stem cell transplantation for your specific diagnosis. Second, ask whether your plan covers mesenchymal stem cell therapy for your specific condition. Third, ask what the prior authorization requirements are for each. Get the representative to give you a case or reference number for the call. Do not accept vague answers like "it depends." Push for a written determination if possible. I recently went through this process for a family member with a UHC Medicare Advantage plan. The representative initially said stem cell therapy was not covered. After I asked specifically about the code for allogeneic hematopoietic stem cell transplantation for myelofibrosis, which is an FDA-approved indication, the representative confirmed coverage with prior authorization. The initial vague answer was because the representative did not ask the right follow-up questions. Being precise about your diagnosis and the specific procedure code makes a real difference in getting an accurate answer on the first call.
What to Do If Your Claim Is Denied
Denials are common but not final. United Healthcare provides an internal appeals process, and for Medicare Advantage plans, you also have access to an external review through the state insurance department or CMS. The first-level appeal is usually where most successful reversals happen, so invest time in making it strong. Gather peer-reviewed studies, guidelines from professional medical societies, and a detailed letter from your physician explaining why this treatment is medically necessary for your specific condition. There is a practical limitation you should understand. Even if you win an appeal for a non-standard stem cell procedure, the likelihood of a second denial on re-review is high. UHC medical policies are not easy to change based on individual claims. If your first appeal is denied, you can proceed to level two appeal, but I would recommend weighing the cost of the procedure against the probability of success. For a procedure that costs ten thousand dollars or more with an estimated ten to fifteen percent chance of appeal success, the math is not favorable for most people. The most reliable path to coverage remains sticking to FDA-approved indications with strong clinical evidence. If your doctor recommends a stem cell treatment that is outside of established medical guidelines, assume it will not be covered and plan accordingly. The financial exposure is too significant to gamble on an appeal for an experimental procedure.
Alternatives When UHC Does Not Cover Treatment
If your plan does not cover the stem cell procedure you need, there are a few options to consider. Some providers offer payment plans or reduced cash-pay rates. Several patient assistance foundations, like the HealthWell Foundation and the Patient Access Foundation, occasionally have grants for specific stem cell conditions, though funding is limited and competitive. Clinical trials are another route, and if you qualify for a trial, the study protocol typically covers the cost of the investigational treatment. You can search for trials on ClinicalTrials.gov, though the application and screening process can take several months. A few states have passed laws requiring broader coverage for certain regenerative therapies, but these laws are narrow and apply only to specific conditions. California and Texas have some limited provisions, but they do not create a general coverage obligation for stem cell treatments. Check with your state insurance department if you believe your plan should be covered under state law, but do not assume state mandates will solve this problem. The bottom line is that stem cell therapy coverage under United Healthcare is highly condition-specific and procedure-specific. Hematopoietic transplants for approved indications are generally covered. Everything else faces an uphill battle. Always verify with your specific plan documents before proceeding, and never assume that a doctor recommending a treatment means insurance will pay for it. The gap between medical recommendation and insurance coverage is where most financial problems arise in this space.