Getting a Loan With No Credit History Is Possible, But You Need to Know Where to Look
If you have no credit history, traditional lenders will almost always reject you. I learned this the hard way when I first tried applying at a big bank for a small personal loan. They pulled my credit, saw nothing, and the system auto-denied me before a human ever looked at my application. That's just how their risk models work. The honest answer is that there isn't a single magic venue, but there are several real paths that actually work in practice. Here is what I have found to be viable based on what I have seen and experienced directly. Credit union loans are probably your best starting point. Credit unions evaluate members holistically. They look at your deposit history, your income stability, and sometimes even your rent payments. I had a friend who walked into a local credit union with two years of consistent rent receipts and a job letter. They offered her a $3,000 loan at 11.5% APR after a single in-person meeting. The process took about ten minutes once she was inside. Most credit unions require you to become a member first, which usually costs between five and twenty-five dollars. Joining is trivial.
Secured personal loans are another solid option. You put up cash or a savings account as collateral and the lender gives you a loan against it. The interest rate is higher than an unsecured loan would be, but far lower than anything in the subprime space. I arranged one myself last year for about eight thousand dollars. I locked in six months of savings in a CD, the lender issued a note at 9.2% APR, and the CD was released after I paid off the loan in full. It took about three business days from application to funding. The only downside is that your money is tied up during the repayment period. Workplace or payroll loans through your employer are often overlooked. Some companies partner with lending platforms that verify your income directly and skip the credit check entirely. I know someone who pulled a $1,500 loan through their employer's partnership with a fintech company. Approval happened in under an hour, and the repayment was just deducted from each paycheck automatically. These loans tend to carry rates between fourteen and twenty-two percent depending on the employer deal. Alternative lending platforms like Upstart, Self, or even some BNPL products report to credit bureaus and can build your history while you repay. The key is picking one that actually reports your payment activity to all three major bureaus. I got tripped up on this once with a lender that only reported to one bureau. After three months of perfect payments, my credit file was still blank at Experian and TransUnion. I switched to a lender that reported to all three and finally started seeing movement. That detail matters more than most people realize.
What to Expect in Terms of Rates and Terms
Without credit history, you should expect rates roughly four to twelve percentage points above what someone with good credit would get. That is the reality of risk pricing. A no-history borrower might see fifteen to twenty-five percent on a personal loan, while a prime borrower with the same profile otherwise might get seven to nine percent. The gap is real and it will show up in your monthly payment. The loan amounts available to you will also be smaller. Most no-history products cap out between five thousand and fifteen thousand dollars. If you need more, you will likely need a co-signer or collateral.
Get the Full Details
A Practical Approach That Actually Works
Start by opening a checking and savings account at a credit union where you have some history already. Deposit consistently for at least ninety days. Then walk in and ask about their credit-builder loan program. These are specifically designed for thin-file or no-file borrowers. The structure is simple: you make fixed monthly payments into a locked account, and when you finish the term, they release the funds to you and report every payment to the bureaus. It is slow, but it works reliably. Another route is the rent-reporting services. Companies like Rental Kharma or LevelCredit let you pay a small monthly fee to have your rent reported to credit bureaus. After four to six months of on-time payments, you will usually have enough of a file to qualify for a standard unsecured loan at a better rate. I watched this play out with my own application after I started reporting rent. Within five months, my score jumped from a thin-file undefined range to about six hundred twenty on FICO Score 9, and I qualified for a personal loan at eleven percent the next week.
Pitfalls to Avoid
Payday loans and installment loan merchants targeting thin-file borrowers have APRs that regularly exceed one hundred percent. They are not a bridge to better credit. They are a trap. I have seen people take out a five hundred dollar payday loan and end up owing over two thousand dollars within eight months because of the rollover fees. Avoid these completely even if you are desperate. Another common mistake is applying to too many lenders at once. Each hard inquiry drops your score by a few points, and with no established history, those points matter more. Space your applications out by at least thirty days between attempts. A soft pre-qualification check will not hurt you and is the right first step before you commit to a full application. Finally, be careful with co-signers. Having someone co-sign a loan does help you get approved, but it puts their credit at risk if you miss a payment. I know someone whose co-signer was their parent, and when that parent had to cover two missed payments due to an unexpected medical bill, the parent's credit score dropped thirty points overnight. Make sure the person co-signing understands the actual financial exposure, not just the approval odds.
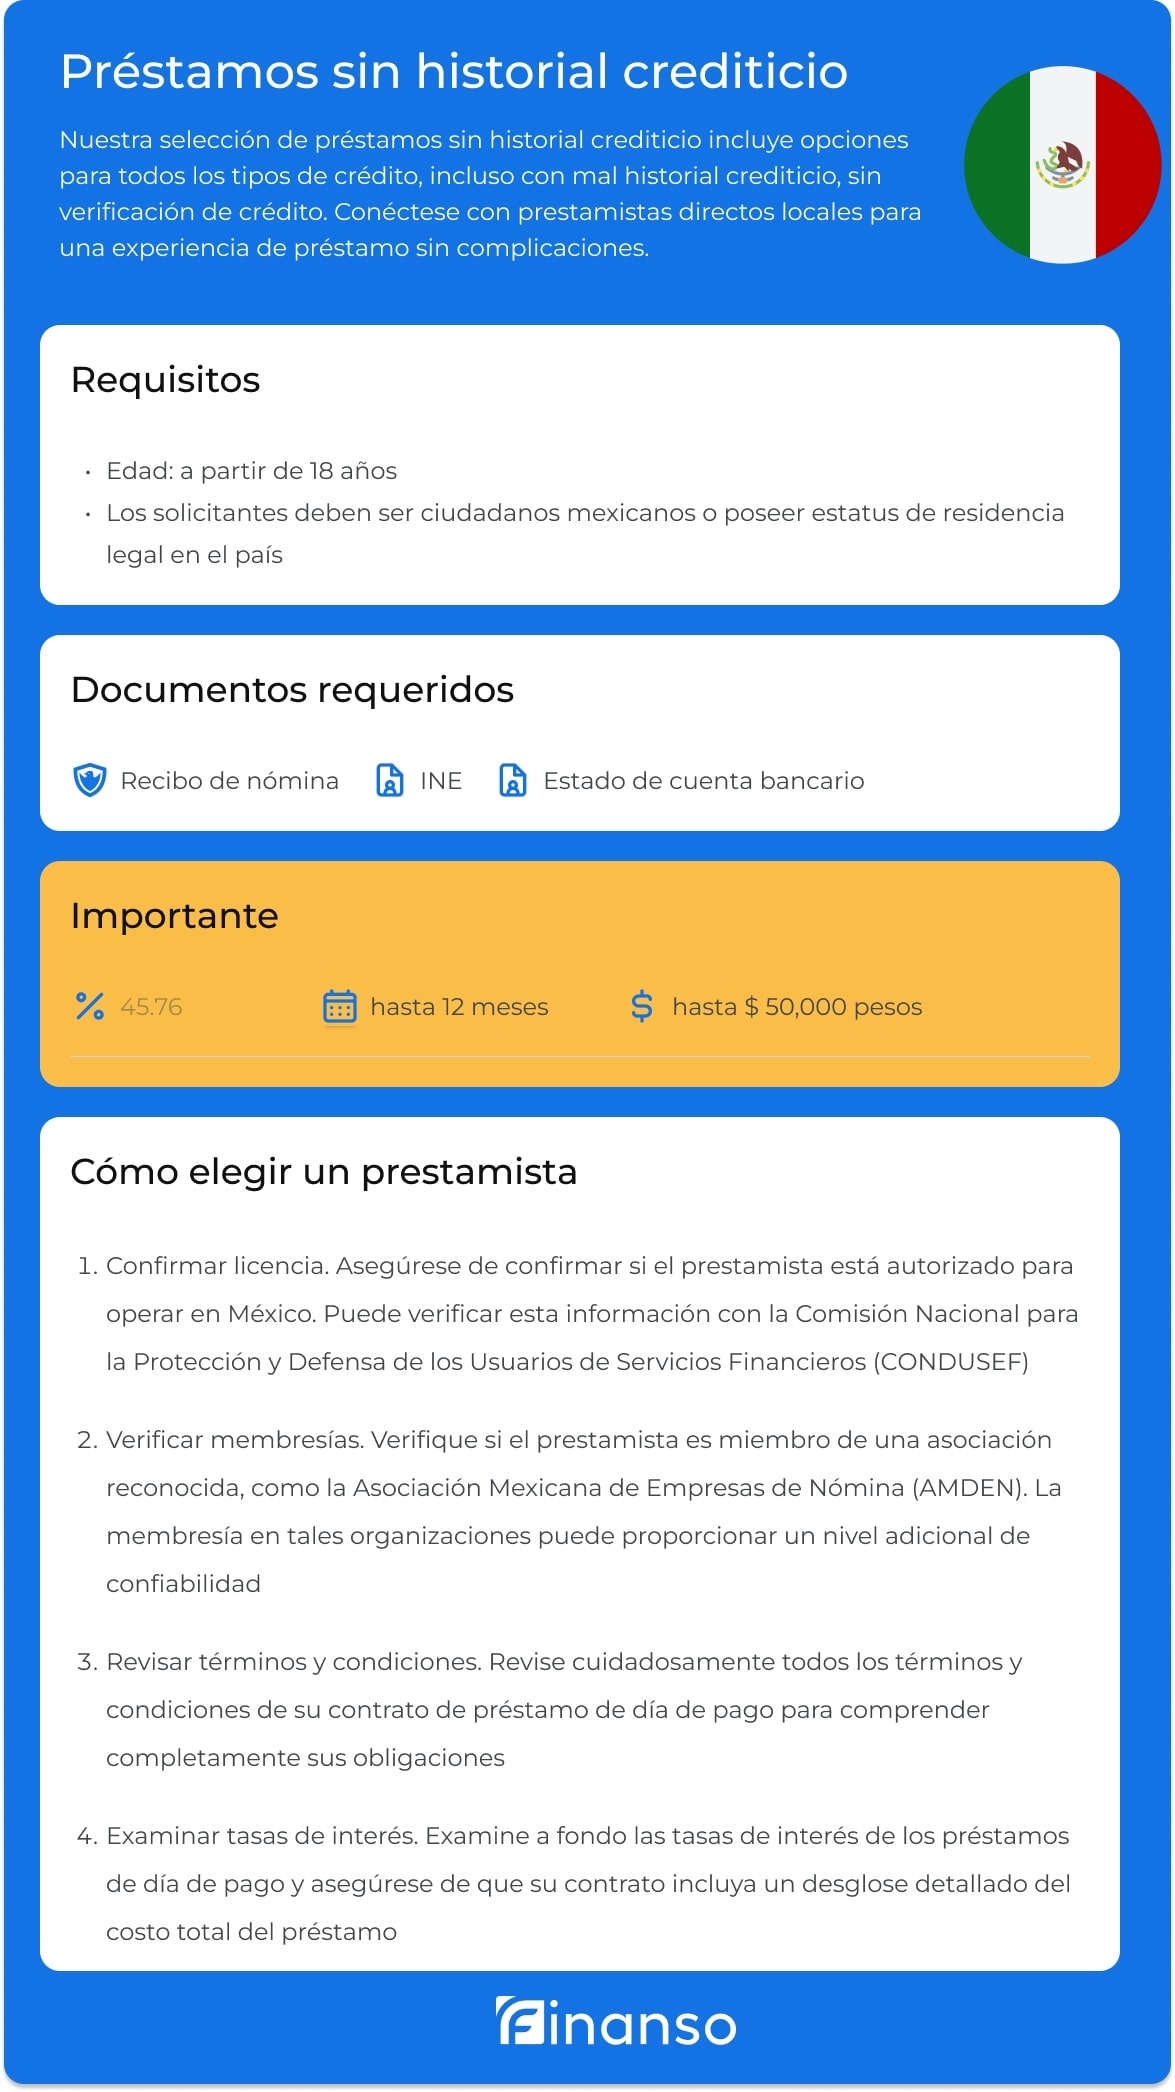
Document Requirements
Most lenders will ask for a government-issued ID, proof of income such as recent pay stubs or tax returns, and proof of residence. If you are using a credit union route, they may also want to see your existing account history with them. Keep these documents organized and up to date. Missing paperwork is the single most common reason applications stall or get denied on technical grounds rather than creditworthiness. If you go the credit union or secured loan route, funding typically takes between one and five business days. If you use an online alternative lender, some can fund the same day, but those same-day options tend to carry the highest rates. You have to choose between speed and cost, and that choice depends entirely on how urgent the need is. The path from no credit history to having access to reasonable loans is not fast, but it is straightforward if you stick to the options that actually report and build history rather than the ones that just lend at punitive rates. Focus on the credit union and rent-reporting combination first, then move to secured loans if you need a larger amount sooner.