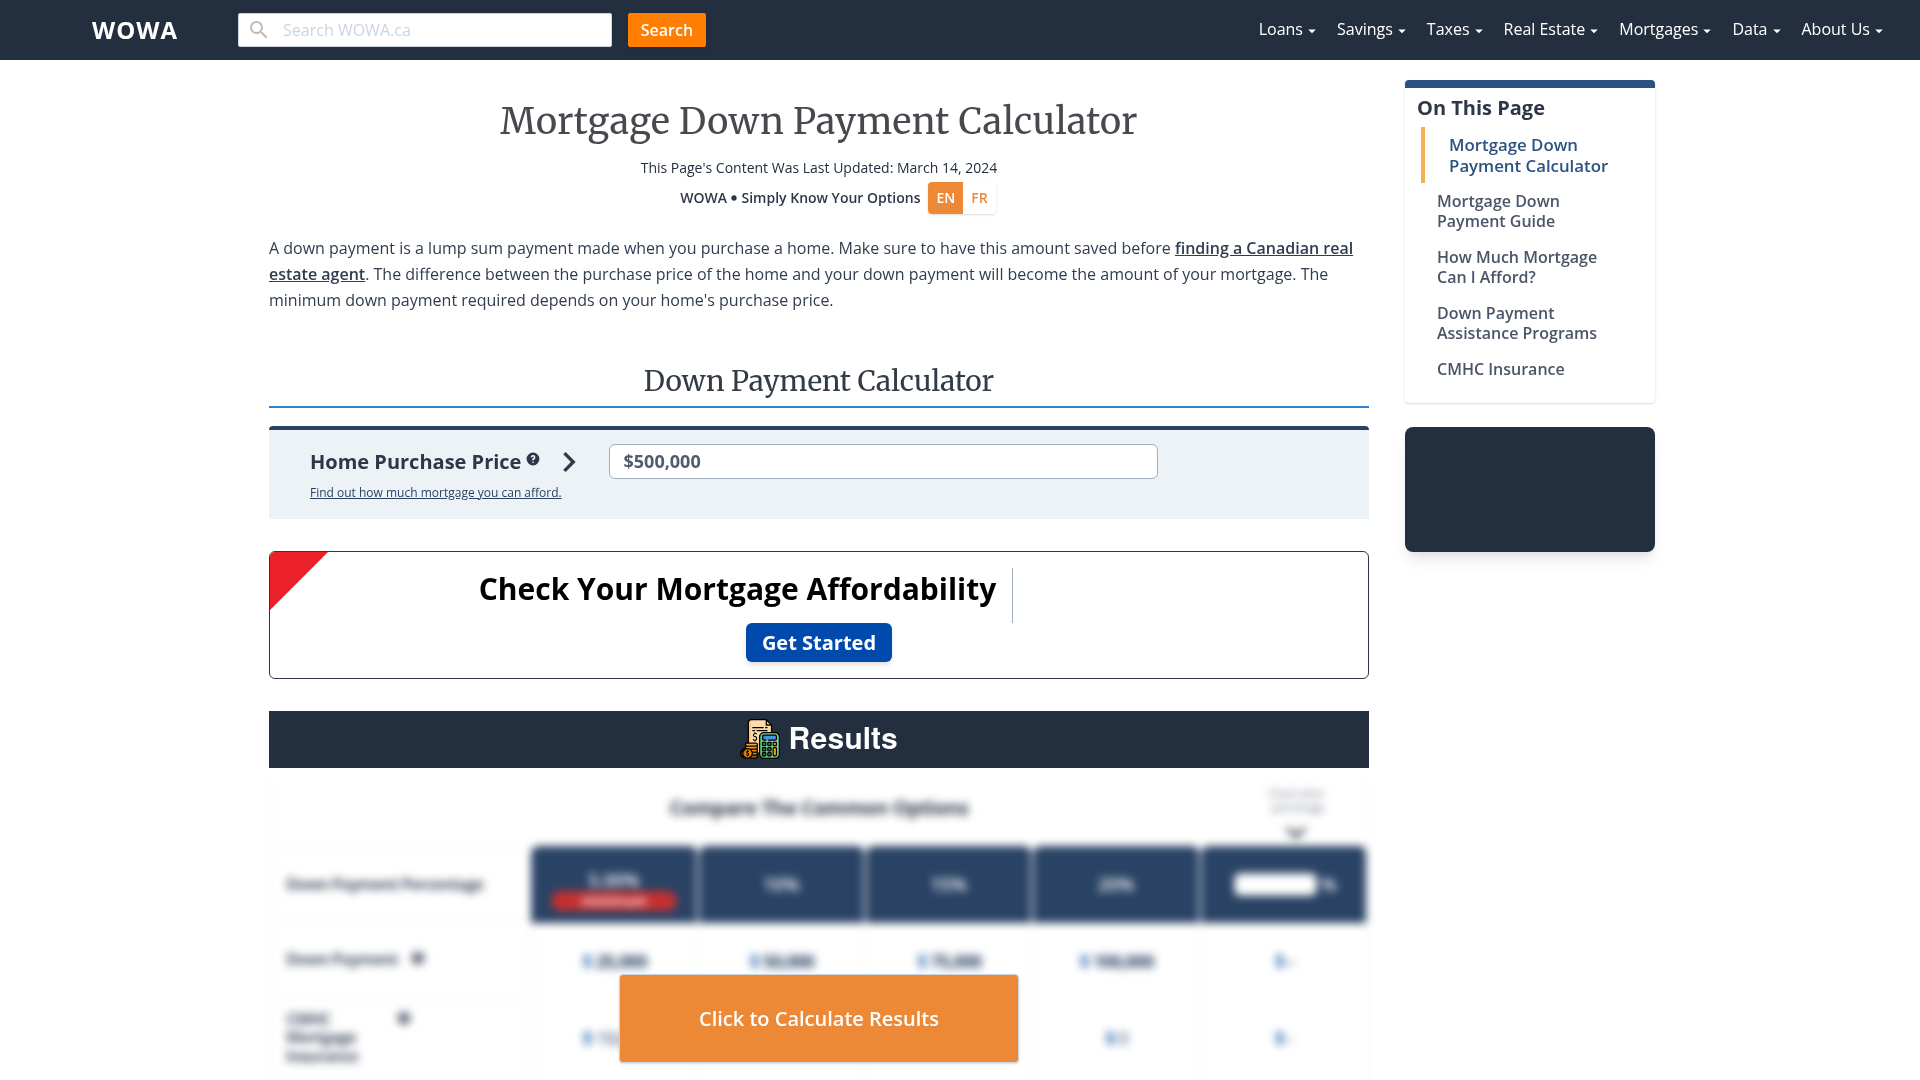
What actually happens when you run a down payment through a mortgage calculator
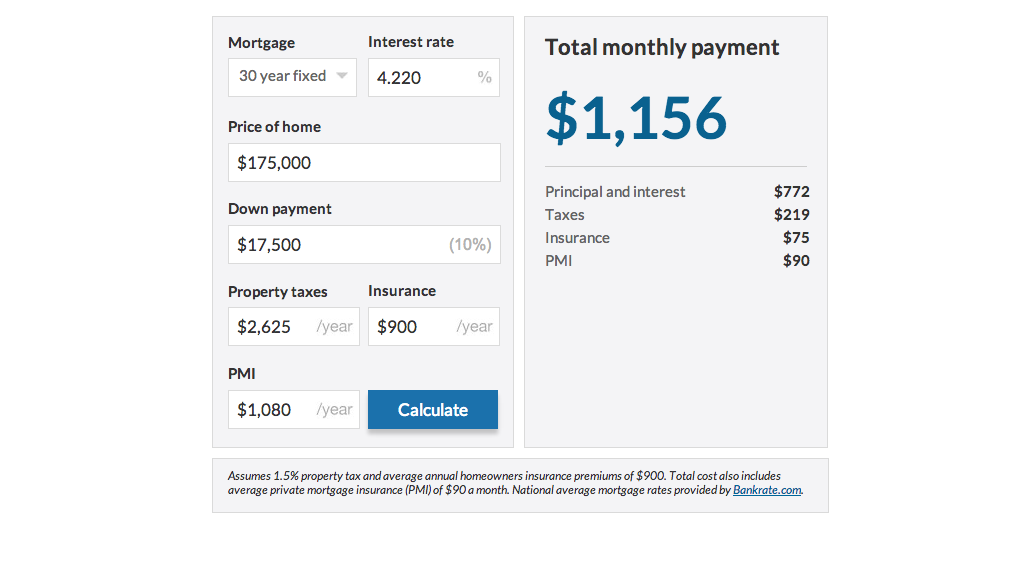
The Down Payment Mortgage Calculator is just a tool that plugs three numbers into a standard amortization formula to spit out your monthly payment. I know that sounds insulting to anyone who has worked with them, but most people think there is more going on under the hood than there actually is. The math is straight-line algebra from 1960. What trips people up is not the calculator itself but the inputs they feed it and the outputs they expect to be accurate. Here is the practical workflow I have seen work and fail over many years of watching borrowers, loan officers, and real estate agents bounce between tools. You enter the purchase price, the down payment amount or percentage, the interest rate, and the loan term. The calculator returns your principal and interest payment, sometimes taxes and insurance if the tool is fancy enough. That is the core of it. I recently had someone run a calculation for a $425,000 home with 8 percent down at 6.875 percent interest over 30 years. The output said $2,687 a month. They showed up at a closing appointment convinced that was their total housing cost. It was not. Property taxes in their county added $580 monthly. Homeowners insurance ran another $145. PMI came in at $198 because 8 percent down was below the 20 percent threshold. Their actual PITI payment was $3,610, not $2,687. The calculator gave them exactly what they asked for. They just asked for the wrong thing.
The fix is simple but most people skip it. After you get your P&I number from the calculator, you add estimated property taxes, homeowners insurance, and PMI if applicable. Most counties publish property tax rates online. Insurance quotes take ten minutes on an aggregator site. PMI drops off once you hit 20 percent equity, but until then it is a real monthly cost. I always tell people to budget for the full payment, not just the principal and interest portion, or you will look comfortable on paper and broke in reality. If you want a downloadable tool, most national banks offer free spreadsheets or web calculators you can save. Search for "Fannie Mae mortgage calculator" or "Freddie Mac loan estimator." Those are not affiliated with your specific loan but they follow the same FHA and conventional formulas everyone uses. Avoid random PDF generators from real estate blogs. They often have stale interest rate assumptions and broken formulas that date back to the 2015 market. One thing that catches people off guard is how down payment percentage affects your rate. Lenders price loans in discount points. A 25 percent down payment on a conventional loan often qualifies you for a rate half a point lower than an 10 percent down payment on the same loan. That is not a calculator quirk. That is how risk-based pricing works. The Down Payment Mortgage Calculator will not warn you about this. You have to know to ask about it during the rate lock conversation with your lender.
Another nuance most tutorials miss involves debt-to-income ratios. A larger down payment reduces your monthly payment and improves your DTI, which can qualify you for a slightly higher purchase price or a better rate tier. But if you drain your savings to 3 percent down, your reserve requirements change. Some lenders require six months of payments in liquid assets after closing. Others require zero. That decision changes your effective down payment by tens of thousands of dollars. Run the scenario both ways before you commit. The calculator breaks down completely when you throw unusual loan types at it. Jumbo loans, VA loans, FHA loans with upfront MIP, and construction-to-perm loans all have different cost structures that generic calculators do not model. A VA loan with zero down will show a monthly payment that looks incredible until you remember the 1.44 percent funding fee gets rolled into the loan balance. A $350,000 VA loan becomes $350,500 before the first payment hits. An FHA loan adds an upfront mortgage insurance premium of 1.75 percent plus monthly MIP that never drops even at 20 percent equity. Generic tools do not handle either of these correctly. If you are dealing with an unconventional loan, stop using the calculator for anything beyond a rough ball park figure and go straight to a lender estimate. You will save about 40 minutes of back-and-forth re-plugging numbers that were wrong anyway.
Get the Full Details

When the calculator gives you useful data and when it does not
A Down Payment Mortgage Calculator is useful for side-by-side comparisons. Show me a 15-year at 6.125 percent versus a 30-year at 6.625 percent on a $310,000 home with 12 percent down and I can tell you which costs more in total interest within a minute. The 15-year saves roughly $47,000 in interest over the life of the loan but increases the monthly payment by about $580. That trade-off is visible in the numbers immediately. The calculator makes that comparison trivial. Where it fails is in modeling rate changes between application and closing. I had a client lock at 6.75 percent, then rates dropped to 6.25 percent the next week. Her calculator results were obsolete. She had already done all her budgeting around the higher rate. This happens constantly during volatile rate periods and no calculator can account for it. You need to understand that any number coming out of a calculator is a snapshot, not a guarantee. The other practical limitation is that calculators assume perfect payment history. They do not factor in late payment penalties, escrow shortages, or the possibility of an adjustable rate reset. If you are looking at an ARM, the calculator will show you the initial teaser rate payment, which is almost never the payment you will live with long term. Get an amortization schedule from your actual lender instead. It takes five minutes and is more accurate than any web tool.
Bottom line: use the calculator for quick comparisons and sanity checks. Do not use it as your final budget number. Add taxes, insurance, PMI, and funding fees yourself. Verify the output with a lender estimate before you make any offers. The difference between a confident buyer and an overwhelmed one usually comes down to whether they ran the real total cost or just the P&I number and called it a day.