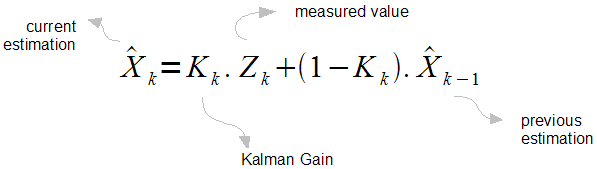Getting Started With Kalman Filters in MATLAB
Kalman filters are used whenever you have noisy sensor data and need to estimate a system state. The math is standard linear algebra, but implementing one correctly takes more care than people expect. This guide walks through the practical steps of getting a basic Kalman filter running in MATLAB, from first principles to a working simulation. The core idea is simple enough that it can be explained in a few lines. You predict where a system should be based on your model. Then you correct that prediction using whatever measurement you just received. The filter computes an optimal balance between trusting the model and trusting the sensors. That balance is controlled by the process noise covariance and the measurement noise covariance.
What Actually Happens Inside the Filter
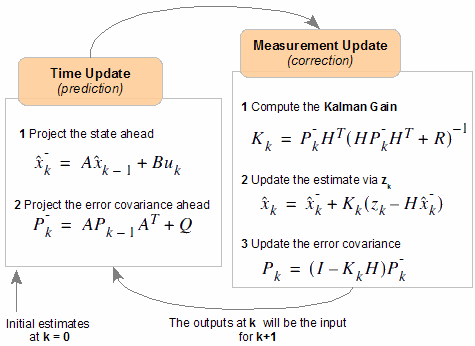
A discrete-time Kalman filter has two main phases: prediction and update. In the prediction step, you propagate the state estimate forward using the state transition matrix and add process noise. In the update step, you compute the Kalman gain, which determines how much weight to give the new measurement versus the predicted state. The Kalman gain formula is well-known but worth writing out explicitly because getting it wrong is the most common beginner mistake. It is the predicted error covariance multiplied by the observation matrix, times the inverse of the measurement innovation covariance. If any of these matrices are the wrong size or have the wrong dimensions, MATLAB will throw an error or silently produce garbage results. I spent two days debugging a navigation filter once because my measurement noise covariance matrix was shaped as a row vector instead of a square matrix. The filter converged to completely wrong values and nobody noticed because the output looked smooth. Smooth does not mean correct.
Download Kalman Filter For Beginners With Matlab Examples
There are several resources available online that package starter code for Kalman filtering in MATLAB. When looking for Download Kalman Filter For Beginners With Matlab Examples, focus on repositories that include both the prediction and update steps implemented separately rather than a single black-box function. Being able to see the intermediate matrices is what lets you debug when things go wrong. GitHub and the MATLAB File Exchange are the two places most tutorials point to. Search terms like "kalman filter matlab tutorial" or "kalman filter example pdf" will surface a handful of usable repos. Pick one that shows the covariance matrices at each step and includes a simulation rather than just theory. A one-dimensional constant velocity model is the simplest case that still demonstrates everything you need. Let the state be position and velocity. The state transition matrix moves position by adding velocity times the time step. Velocity stays constant unless you add an acceleration term, which you usually will once the basic filter works. Here is the structure you would implement:
Get the Full Details
Initialize the state vector with your best guess. Set the initial covariance to reflect how uncertain you are about that guess. If you do not know the velocity at all, make that covariance element large. If you are very uncertain about position, do the same there. The initial covariance choices matter more than most tutorials admit because they affect the first few updates dramatically. Define the process noise. This is the covariance of the uncertainty you introduce at each step due to modeling errors or unmodeled dynamics. A common choice is a small value on the velocity component if you are assuming constant velocity but expect occasional acceleration. The exact value should come from experimentation or calibration, not from picking a nice round number. Define the measurement model. For position-only measurements, the observation matrix selects the position element from the state. The measurement noise covariance is a scalar variance if you have a single sensor, or a diagonal matrix if you have multiple measurements.
Working Through the Code Structure
In MATLAB, the implementation runs inside a loop over time steps. At each iteration, you perform the prediction, then the update. The prediction uses the state transition matrix and the process noise covariance. The update uses the Kalman gain, the measurement residual, and the updated error covariance. The residual is the difference between the actual measurement and the predicted measurement. If the sensor is reading position and your filter predicts position, the residual is just measurement minus predicted position. Getting this sign wrong flips the correction in the wrong direction and destabilizes the filter quickly. I once had a temperature sensor integrated into a state estimation pipeline where the measurement was delayed by two time steps. The filter diverged within minutes because it was treating stale data as current. The fix was to keep a queue of recent measurements and feed the filter only the one matching the current time step. This kind of timing issue does not show up in textbook examples and it takes real deployment experience to anticipate it.
Common Pitfalls and How to Avoid Them
The first pitfall is treating the Kalman filter as a smoothing tool. It is not. It is a recursive estimator that uses only current and past data. If you need past, present, and future data to improve estimates, you need a smoother like the Rauch-Tung-Striebel algorithm, which is a separate implementation. The second pitfall is initializing the covariance too small. A small initial covariance makes the filter trust its own predictions almost entirely and ignore measurements for a long time. If your initial state guess is wrong, the filter will be slow to correct. I usually set the diagonal elements of the initial covariance to something larger than I think I need, then tighten it after watching the filter behavior over a short test run. The third pitfall is using a fixed process noise covariance across conditions that vary widely. If your system experiences both gentle motion and abrupt changes, a single process noise value will either over-smooth during rapid changes or under-smooth during steady motion. The workaround is either to tune two sets of parameters for different regimes or to move toward an adaptive approach.
There is also the issue of numerical stability. If you update the covariance using the standard Joseph form instead of the basic update equation, you reduce the risk of the covariance matrix losing symmetry due to floating-point error. It adds a few extra multiplications but prevents a class of bugs that are very hard to trace. MATLAB handles most of the matrix operations efficiently, but the covariance update is where people cut corners and pay for it later.
Testing the Filter Before Deploying It
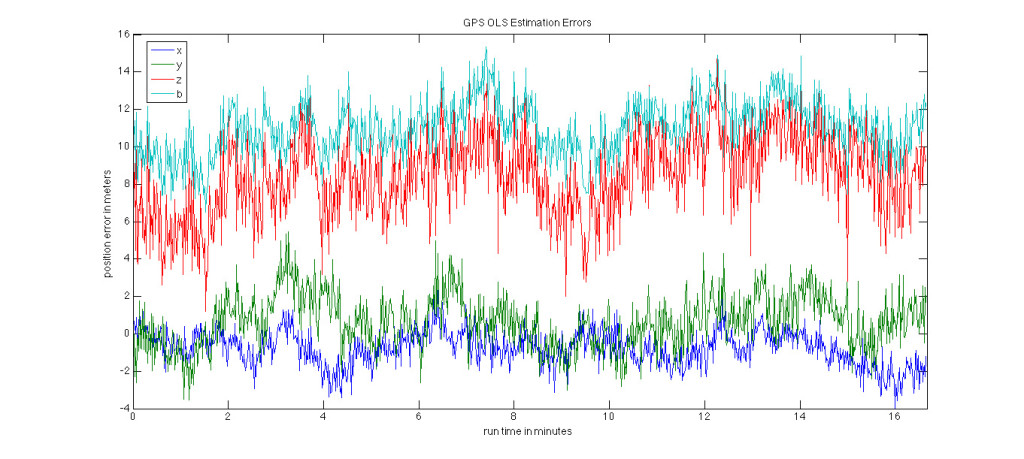
Before attaching the filter to real sensor data, generate synthetic measurements from a known trajectory. Add Gaussian noise with a specified standard deviation and run the filter over the same data. Compare the estimated states against the true states. If the estimation error grows over time, something in the covariance tuning is wrong. If the error oscillates wildly, the measurement noise might be underestimated or the model might be missing a dynamics term. A useful diagnostic is the normalized innovation squared. It should follow a chi-squared distribution with degrees of freedom equal to the number of measurements. If the values are consistently outside the expected range, the filter is either overconfident or underconfident in its uncertainty estimates. I use this check as a first validation step on every new system I build. It catches most covariance misconfigurations in under a minute. Another check is the residuals over time. They should look like white noise with zero mean. Any pattern in the residuals means the model is missing something. A trend in the residuals usually indicates a biased measurement or an unmodeled constant acceleration. A sinusoidal pattern can indicate a periodic disturbance that the model does not account for.
Limitations You Should Know About
The standard Kalman filter assumes linear dynamics and Gaussian noise. Real systems rarely satisfy both assumptions perfectly. When the dynamics are nonlinear, you need an extended Kalman filter or an unscented Kalman filter. The extended version linearizes around the current estimate, which can fail badly if the nonlinearity is strong or the initial uncertainty is large. The unscented version uses sigma points and is generally more robust, but it is also more computationally expensive and harder to debug. If the noise is not Gaussian, the Kalman filter is no longer optimal. It will still produce the minimum variance estimate among linear estimators, but that does not mean it is the best estimate you can get. Particle filters handle non-Gaussian noise better, but they require many more samples and run significantly slower. For most engineering applications with reasonable sensor specs, the Kalman filter is sufficient, but you should not use it when the noise characteristics are heavy-tailed or multi-modal. Maintaining the filter over long periods requires periodic re-evaluation of the noise covariances. What works on day one may drift as sensors age or environmental conditions change. I set up a logging routine that records the innovation statistics and covariance traces so I can spot drift without stopping the system. This has saved me from having to replace hardware unnecessarily multiple times.
Where to Find Ready-to-Run Examples
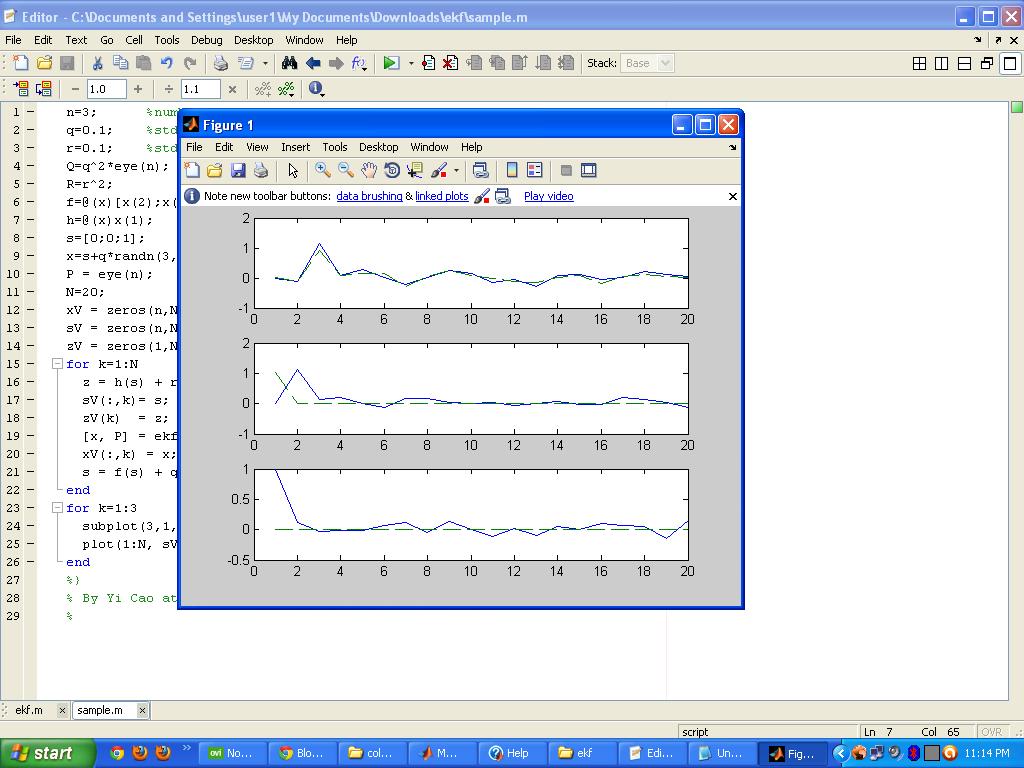
The MATLAB File Exchange has several user-uploaded Kalman filter implementations. Look for submissions that include a demo script with a plot of the true state, the noisy measurements, and the filtered estimate on the same axes. A good example will also show the covariance bounds over time. If the example only shows the state estimate without uncertainty bounds, treat it as incomplete documentation. University lecture notes are another reliable source. Many control systems courses post problem sets with full solutions. These tend to be more rigorous than commercial tutorials and usually include the math alongside the code. The downside is that they can assume familiarity with matrix notation that a complete beginner might not have. Start with a simple example and read the math in parallel rather than trying to absorb both at once. If you search for Download Kalman Filter For Beginners With Matlab Examples, you will find a mix of blog posts, course handouts, and GitHub repositories. Prioritize sources that show the code line by line with comments explaining each matrix operation. Copy-pasted code without explanation is faster to start with but slower to learn from when something breaks.
Next Steps After the Basic Filter Works
Once the one-dimensional case is stable, extend it to two or three dimensions. Add more state variables as needed. Common additions are acceleration, bias estimation, and additional sensors. Each new state variable increases the dimension of the matrices, which increases computation but also increases the information available for estimation. Adding a bias state is particularly useful when your sensors have a slowly drifting offset. Estimating the bias alongside the primary state removes the need for manual calibration on every system restart. The trade-off is that the filter becomes slower and more sensitive to the tuning of the bias process noise. Too much bias process noise and the filter chases random noise. Too little and the bias estimate never converges. There is no universal default for these parameters. The tuning process involves running the filter on recorded data, inspecting the innovation statistics, and adjusting the covariances until the diagnostics look healthy. This is iterative and usually takes several hours for a nontrivial system. Budget that time when planning a project.