How to Build and Use a Downloadable Amortization Schedule
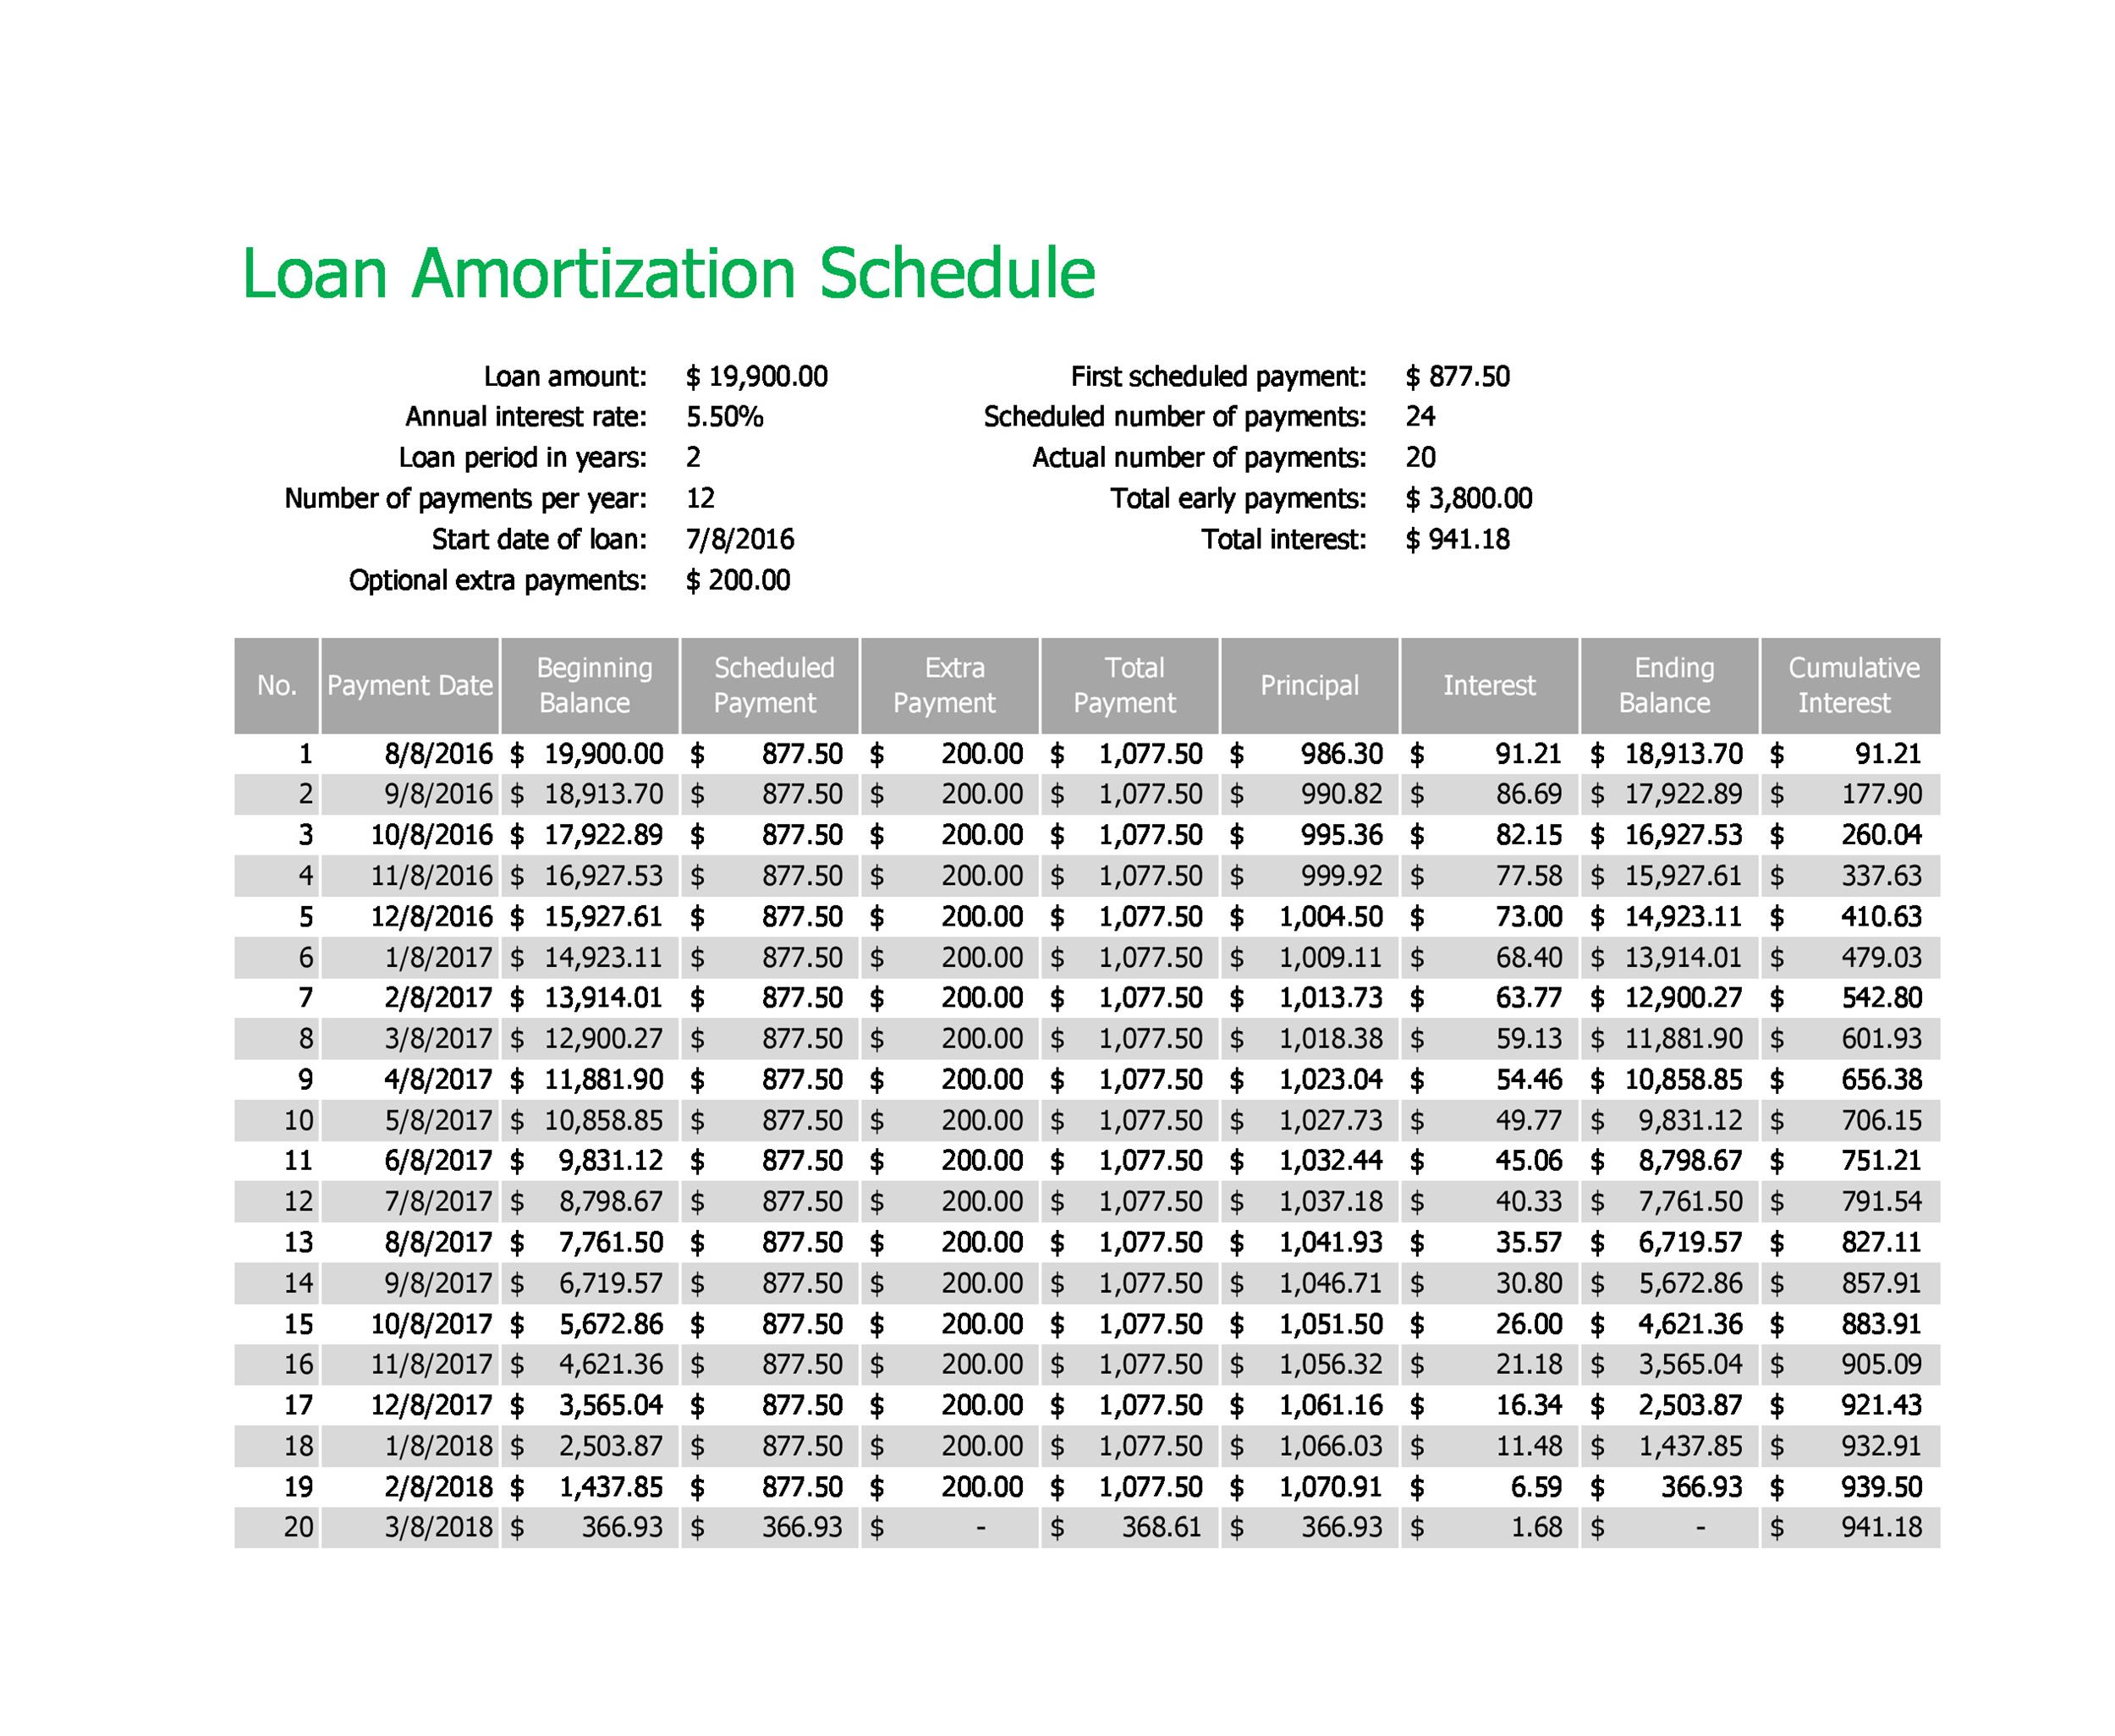
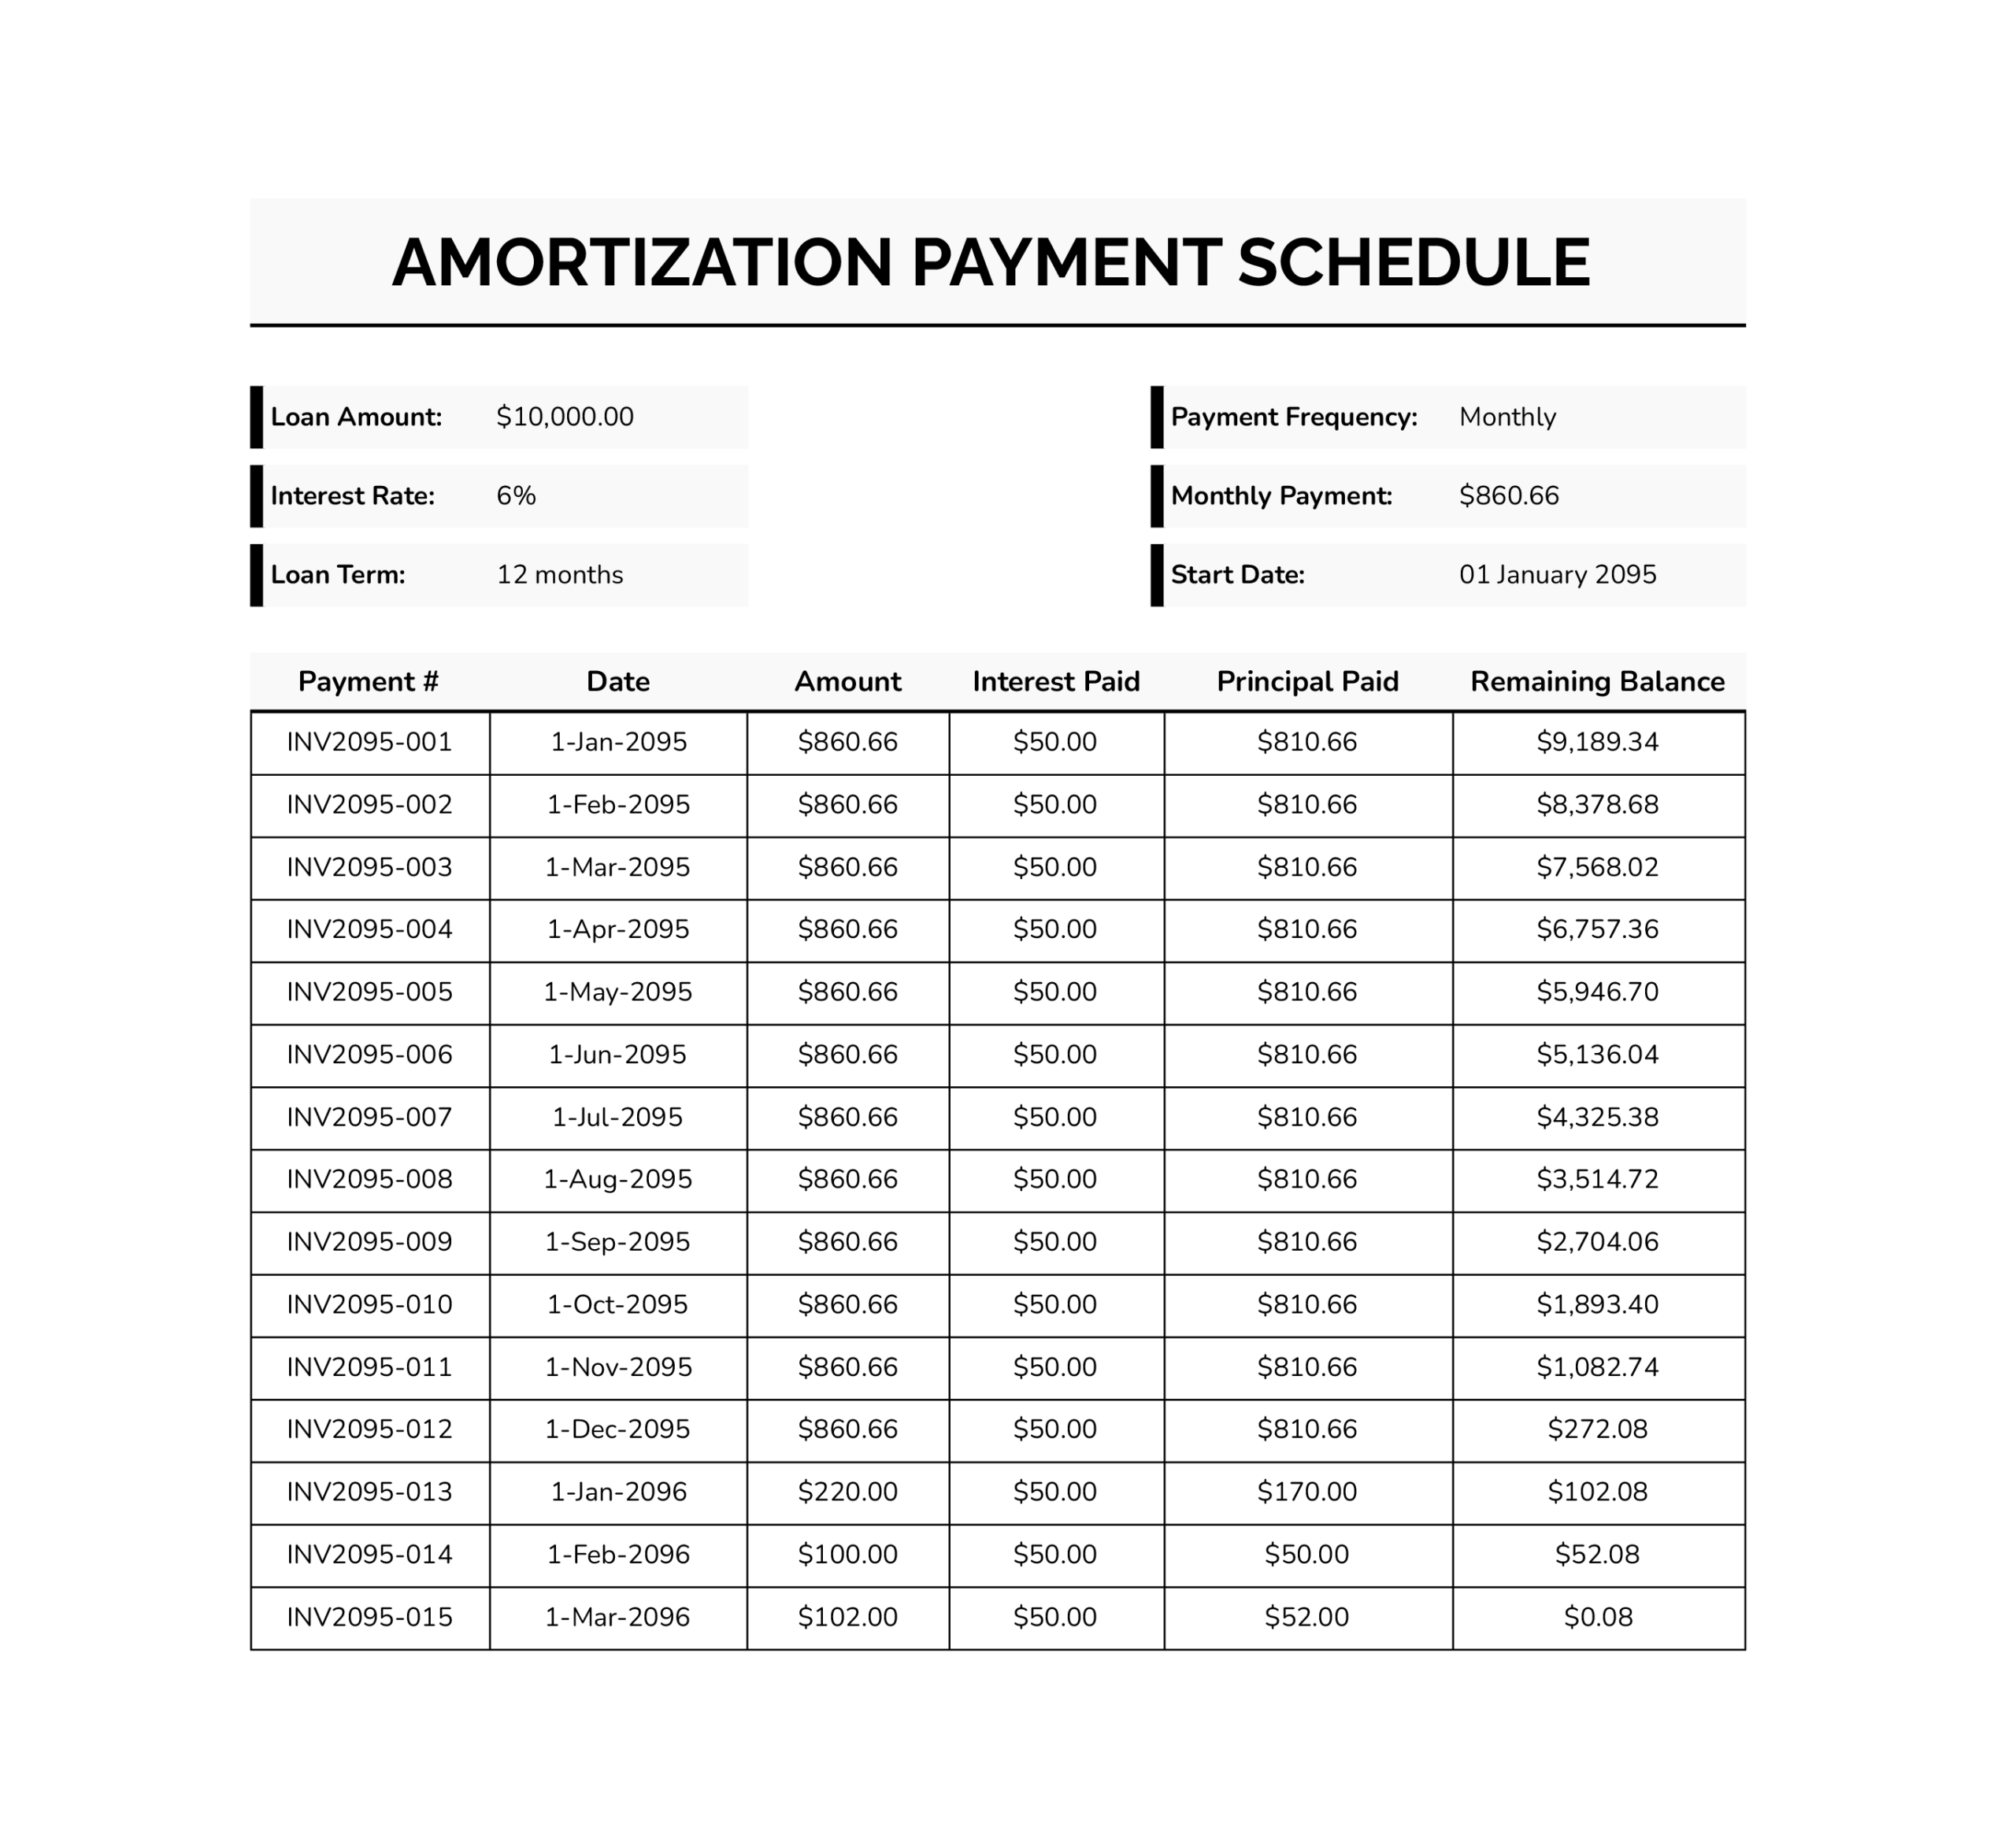
A Downloadable Amortization Schedule is just a spreadsheet — usually in CSV, XLSX, or PDF format — that breaks down every payment on a loan into principal and interest over the full term. You fill in the loan amount, rate, and term, then export the table so you can see exactly how much goes where each month. That is about all there is to it. I built a lot of these by hand before I started generating them programmatically. Back when I was underwriting rental properties, I needed to show investors exactly how the debt service looked year by year. A printed 360-row schedule was useless for a quick meeting. What I actually needed was a file I could email, open in Google Sheets, and highlight the annual totals. That was the moment I stopped looking for pre-made templates and started building my own.
How to Create a Downloadable Amortization Schedule in Excel
The basic structure is a table with columns for Period, Payment, Principal, Interest, and Remaining Balance. You can build this in about ten minutes. Set up your inputs in the top section: Loan Amount: B1, enter 200000
Annual Rate: B2, enter 0.05
Term (years): B3, enter 30
Then in column A, list period numbers 1 through 360. The payment column uses the PMT function: =-PMT(B2/12, B3*12, B1). The negative sign flips the result to positive since PMT returns a negative value by convention. That gives you $1,073.64 per month for this example. The interest portion for each row is straightforward. In row 2, the formula is =B1*$B$2/12. The principal portion is the payment minus the interest: =C2-D2. The remaining balance for that row is the previous balance minus the current principal payment: =B1-E2. Drag those formulas down 360 rows and your schedule is complete. You can then export it as a CSV or XLSX file and share it however you need. Here is what most people skip. The interest calculation above assumes the beginning balance stays static through the month. In reality, some loans compound differently, and the payment timing matters. If your loan payment is due on the first but you pay on the third, the extra two days can shift the accrual enough to change the final payment by a few dollars. Over thirty years, those rounding differences accumulate. I once had a borrower who was twenty-three dollars short on their final payoff because their lender used a 30/360 day count method instead of actual/365. The downloadable amortization schedule they had downloaded from a generic template didn't account for that. It showed a zero balance at month 360, but the actual payoff letter said $23.17 remaining. I had to recalculate the entire schedule using a day-count-aware formula and resubmit it to the escrow company. The workaround was switching every interest calculation to use =BALANCE*RATE*(ACTUALDAYS/365) instead of the flat monthly split. Took me an afternoon but saved a closing delay.
Get the Full Details

Edge Cases That Break Most Templates
The first counter-intuitive thing nobody tells you is that the last payment on a standard amortization schedule is almost never identical to the others. Because of how the formulas round to the cent, the final row often shows a payment that is a dollar or two different. Some templates handle this by forcing the last payment to match the others and showing a tiny leftover balance. Others zero out the balance and adjust the final payment. Neither is inherently wrong, but they produce different numbers and it matters if you are using the schedule for tax purposes or refinancing calculations. Pick one approach and be consistent. The second thing is the difference between an amortization schedule and an interest-only schedule. A lot of free downloadable tools label themselves as amortization schedulers but actually generate interest-only tables for the early years and only shift to principal reduction near the end. This is common with balloon loans and some government-backed programs. If you are evaluating a loan with an interest-only period, make sure the tool you are using actually models that transition, not just a standard fixed-payment schedule. Another nuance: some lenders report the amortization schedule using a 30/360 day count convention, which means every month is treated as thirty days regardless of whether it has twenty-eight or thirty-one. This simplifies the math but creates a mismatch with calendars. The schedule will show 360 equal payments, but your actual calendar will show some months are longer. If you are comparing a downloadable schedule against your bank statements and the numbers look slightly off, this is usually why. The discrepancy is small — maybe a dollar or two per year — but it adds up over the life of the loan.
Using the Schedule After You Download It
Once you have your file, the real work starts. Most people download the schedule and forget about it. That is a mistake. The schedule is most useful when you are planning extra payments or evaluating refinancing options. If you want to test what happens when you add an extra hundred dollars a month, do not just adjust the payment column. Add a separate column for additional principal and recalculate the remaining balance each month. The original schedule will show you how much interest you would save and how many months you shave off the term. In the example I built above, adding just $100 to the monthly principal payment cuts the term from 360 months to about 306 months and saves roughly $28,000 in total interest over the life of the loan. When refinancing, pull the current remaining balance from your schedule and compare it against the new loan terms. Do not rely on the payoff quote from your servicer alone. Servicers sometimes include escrow balances, late fees, or advance interest in their payoff numbers. A clean amortization schedule shows you the true principal remaining, which is what matters for comparing refinance offers.
Limitations of Free Downloadable Tools
Almost every free online amortization scheduler I have encountered has the same blind spots. They do not handle extra payments correctly. They do not support balloon payments. They do not model adjustable-rate mortgages beyond the first adjustment period. And they rarely let you export data in a format that is easy to work with — PDFs are the worst offender because you cannot edit the numbers afterward. My advice is to build your own schedule in a spreadsheet and save it as a template. Once you have the formulas set up, you can reuse it for any loan without relying on third-party tools. The initial investment is about an hour. The time savings over decades of loan analysis is significant. If you still want a pre-built solution, search for a downloadable amortization schedule template that includes support for additional principal payments and customizable day-count conventions. Those are the features that actually matter in practice. The bottom line is that an amortization schedule is only as good as its underlying assumptions. Verify the day-count method. Check how the final payment is handled. Make sure the tool accounts for the specific loan structure you are dealing with. A generic schedule from the internet will get you close, but close is not always accurate enough when money is on the line.