What the Calculator Actually Does
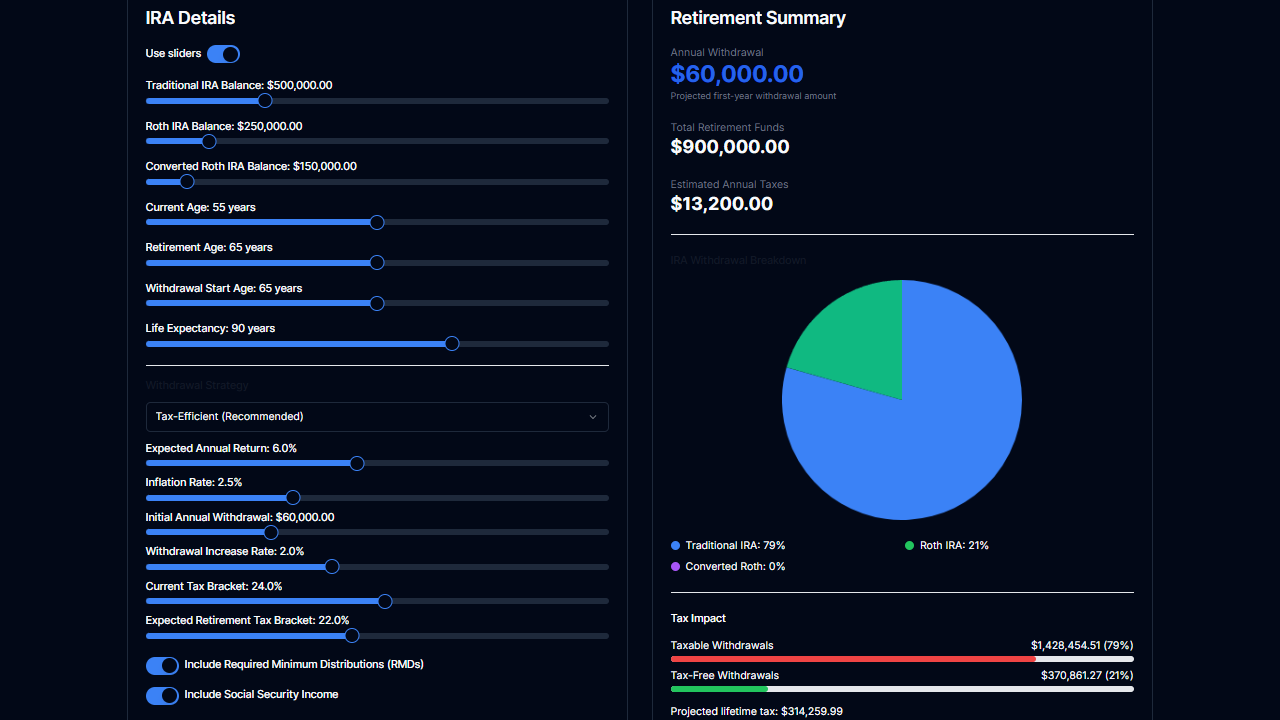
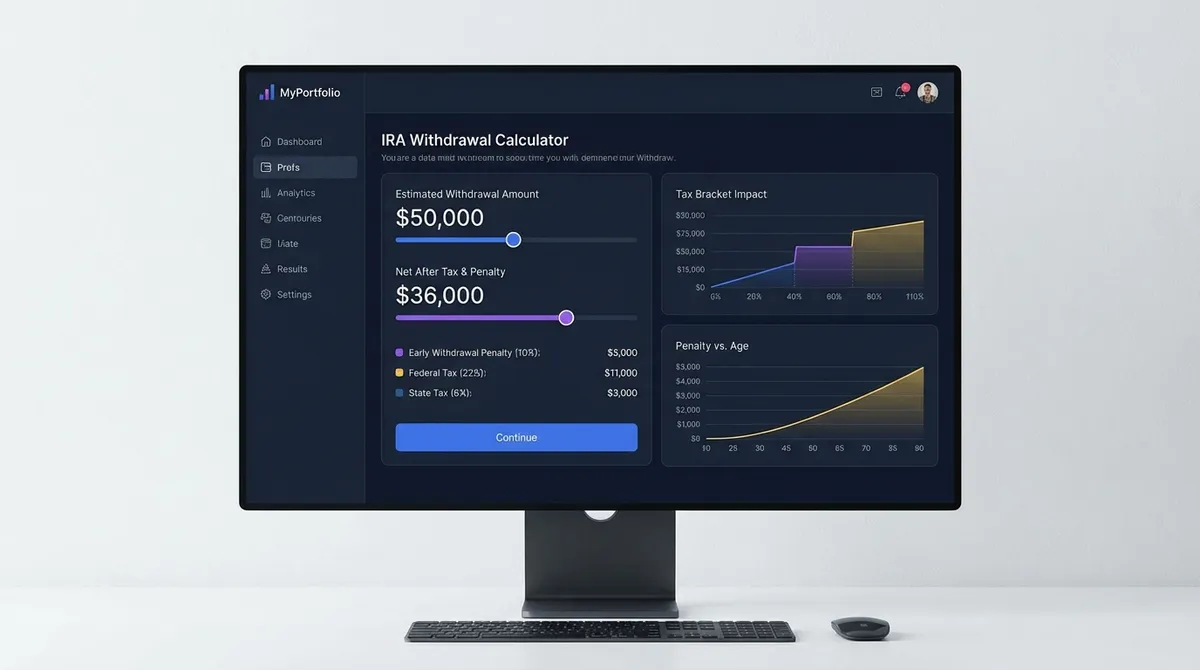
An Early IRA Withdrawal Calculator figures out the real after-tax cost of pulling money out of a retirement account before you hit 59½. The federal government charges a 10% penalty on top of treating the distribution as ordinary income. So if you withdraw $20,000, you aren't just losing 10%. You're looking at 10% plus whatever your marginal tax rate happens to be that year. The inputs are pretty standard. Account type — traditional, Roth, SEP, or SIMPLE. Distribution amount. Your current age. Filing status. Most importantly, your projected taxable income for the year, because that determines your effective marginal bracket and whether the withdrawal pushes you into a higher tax tier. Some calculators also ask for your state, since a handful of states layer their own early-withdrawal penalties on top of the federal rule.
Early Ira Withdrawal Calculator
Here's how you actually use one without getting a misleading number. Enter the gross distribution amount first, not what you want to walk away with. A lot of people flip that around and try to back-calculate from a target net figure, which trips up the tax bracket logic. Then pick the right account type. That matters more than most people realize. A traditional IRA withdrawal is fully taxable as income plus the 10% penalty, unless an exception applies. A Roth IRA is different. Qualified Roth withdrawals are tax-free. For a Roth, the conversion order rule applies — contributions come out first, always. You can pull your regular contributions out at any time without penalty or tax. Only the earnings portion triggers the penalty and income tax if you're under 59½ and don't qualify for an exception. A good calculator flags this distinction automatically. A cheap one won't. I ran into a specific problem with a Roth SEP-IRA last year that a couple of online calculators got wrong. The account was a Roth designated account inside a SEP plan. One tool treated it like a standard Roth IRA and let the user pull out the full balance penalty-free. That was incorrect. Roth accounts inside employer plans like SEP and SIMPLE have different rules than standalone Roth IRAs when it comes to early distributions. The workaround I used was to treat the account as a traditional SEP for withdrawal purposes, apply the penalty to the earnings portion, and manually adjust the output. I ended up cross-referencing the result against IRS Pub 590-B to confirm.
Common Exceptions and When They Apply
The 10% penalty has exceptions. The main ones that come up repeatedly are first-time homebuyer expenses up to $10,000 lifetime limit, qualified education expenses, unreimbursed medical expenses exceeding 7.5% of adjusted gross income, health insurance premiums while unemployed, and a permanent disability. The exception for each is penalty-specific. It does not remove the ordinary income tax that still applies to a traditional IRA distribution. A Roth distribution used for a first-time homebuyer still takes contributions out penalty-free and tax-free, but the earnings portion is subject to income tax even though the 10% penalty drops out. People miss that part. They think "no penalty" means "no tax," and it does not, not in a Roth, not ever for earnings. Substantially equal periodic payments, sometimes called Rule 72(t), is another exception that deserves more attention than it gets. You commit to taking equal payments for five years or until you turn 59½, whichever is longer. The calculators that support it will show the exact payment stream and flag the recapture tax risk. If you modify the payment amount even slightly during that period, the IRS can claw back all the penalties from year one. I've seen two people do this in the last three years. Both were costly mistakes.
Get the Full Details

Where These Calculators Fall Short
No calculator handles everything correctly. The usual gaps are straightforward to predict. Most tools assume you know your exact federal tax bracket for the year, which you often do not until you file. The withdrawal can change your bracket in real time, pushing part of the distribution into a higher marginal rate or even triggering additional taxes like the net investment income tax or Medicare surtax if your income crosses certain thresholds. State tax treatment is another blind spot. California and Michigan, for example, conform to the federal early-withdrawal penalty. Many other states do not, and some states actually offer their own deductions or exemptions for retirement distributions. A calculator that only outputs federal numbers can give you a misleading picture if you live in a state with a different regime. RMDs do not merge cleanly with early withdrawal logic either. If you are over 73 and already subject to required minimum distributions, pulling extra money early does not create an additional RMD obligation, but it does inflate your taxable income for the year. Some calculators miss that interaction entirely.
Steps to Run a Realistic Estimate
- Gather your numbers. Current balance, approximate contribution basis if it is a Roth, and your expected total income for the year including wages, interest, dividends, and any other retirement account distributions you plan to take.
- Enter the gross distribution. Not the net amount you hope to receive. Gross.
- Select account type and tax filing status. Traditional, Roth, SEP, SIMPLE. Single, married filing jointly, head of household. This changes both your bracket and the penalty exceptions available to you.
- Check the exceptions box. Homebuyer, education, medical, SEPP, disability, or none. Be honest. The IRS does not care about hopeful categorization.
- Run the calculation and review the breakdown. You should see the penalty amount, the ordinary income tax, the net distribution, and your estimated effective tax rate on the withdrawal itself.
- Compare to a state-by-state adjustment if your calculator does not include it. Look up your state's treatment of early IRA withdrawals and add or subtract accordingly.
That last step alone usually changes the result by a meaningful margin. In my experience it shifts the final number by anywhere from zero to over a thousand dollars on a five-figure distribution, depending on the state. If the calculator shows a steep hit, the first move is usually to check whether you qualify for an exception. That is the single highest-leverage action. If you do, the 10% penalty disappears and the remaining tax bill may be manageable, especially if the distribution fits into a lower bracket year. If no exception applies, a partial withdrawal is almost always cheaper than a full one. The progressive tax system rewards that. Taking $5,000 instead of $20,000 keeps you in a lower bracket and shrinks the penalty base simultaneously. A rollover is another option if you are leaving a job, but rollovers from a traditional IRA to another qualified plan do not erase the early withdrawal tax consequences if the receiving account is still a traditional arrangement and you are under 59½.
There is also the option of doing nothing. I know that sounds obvious, but it is worth stating plainly. An emergency fund, a personal loan, or a home equity line usually costs less than a premature IRA distribution when you factor in the compounding growth you give up inside the account. The lost growth from removing $20,000 at a modest 7% return over thirty years is roughly $160,000 in foregone value, not including the immediate tax and penalty hit.