Why You Probably Don't Need Fancy Software for This
I spent three years helping people restructure their debt at a credit counseling agency. The first thing I learned was that most mortgage payoff calculators online are built by people who have never actually sat down with a borrower who wanted to pay off their loan early. They throw numbers at a spreadsheet and call it done. The formulas are technically correct, but the real world doesn't work that way. So here's what I want you to know before you plug in your numbers and get excited about saving years of interest. An Early Mortgage Payoff Calculator is a tool that takes your current loan balance, interest rate, remaining term, and any extra payment amount, then tells you how much faster you'll pay off the loan and how much interest you'll save. That's it. Nothing mystical about it.
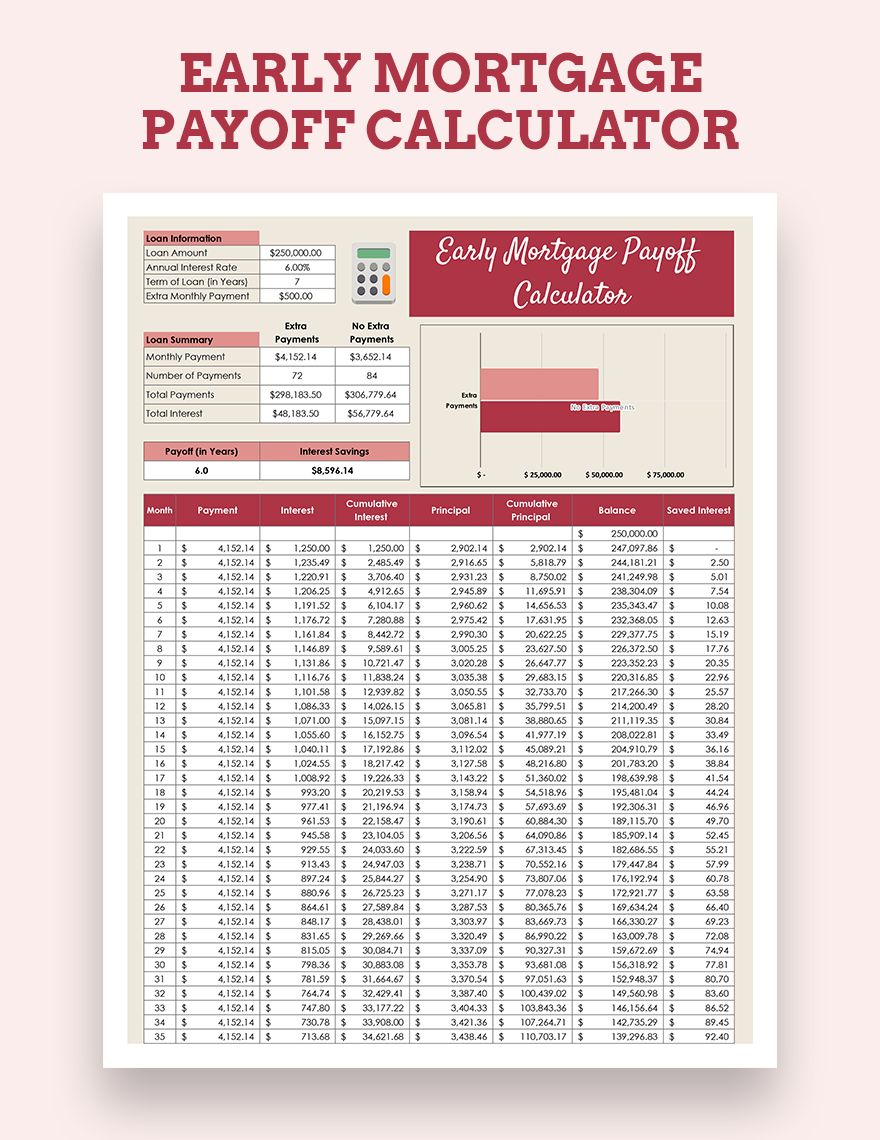
Early Mortgage Payoff Calculator
The standard approach uses what's called the amortization formula. You start with your monthly principal and interest payment, which your lender already calculated when they approved your loan. The trick is figuring out what happens when you add extra principal payments each month. Most online calculators assume you make one lump-sum extra payment or add a fixed amount every month. Neither of these matches how people actually behave with mortgages. Let me walk you through the math before we get into the tools. Your regular monthly payment goes toward interest first, then principal. In the early years of a 30-year loan at 6 percent, roughly 70 percent of your payment is interest. That percentage drops slowly over time. When you make an extra payment, every dollar of that extra payment goes straight to principal because it bypasses the interest calculation entirely. This is where people get confused. They think the extra payment reduces the interest on the next month's bill. It doesn't. It reduces the principal balance, which then reduces future interest charges. The effect compounds over time because your payment stays the same but your balance shrinks faster. I ran into a specific problem last year with a borrower named Teresa. She had a $280,000 loan at 5.75 percent with 22 years remaining. She wanted to throw an extra $500 at the principal every single month. The calculator she found online told her she'd save $47,000 in interest and pay off the loan in about 16 years. Everything looked fine on paper. But when I dug into her actual loan documents, I noticed something the calculator completely missed. Her loan had a prepayment penalty clause. Not a massive one, but it charged 2 percent of the remaining balance if she paid off more than 20 percent of the original loan amount in a single year. Teresa's strategy would have triggered this penalty in year three because she was ahead of schedule by so much. The extra $500-a-month plan would have actually cost her an additional $5,600 in penalties within the first four years. She adjusted to $200 extra per month instead, which stayed under the threshold and still shaved nearly six years off the loan. The lesson here is simple: read your actual loan documents before you trust any calculator output.
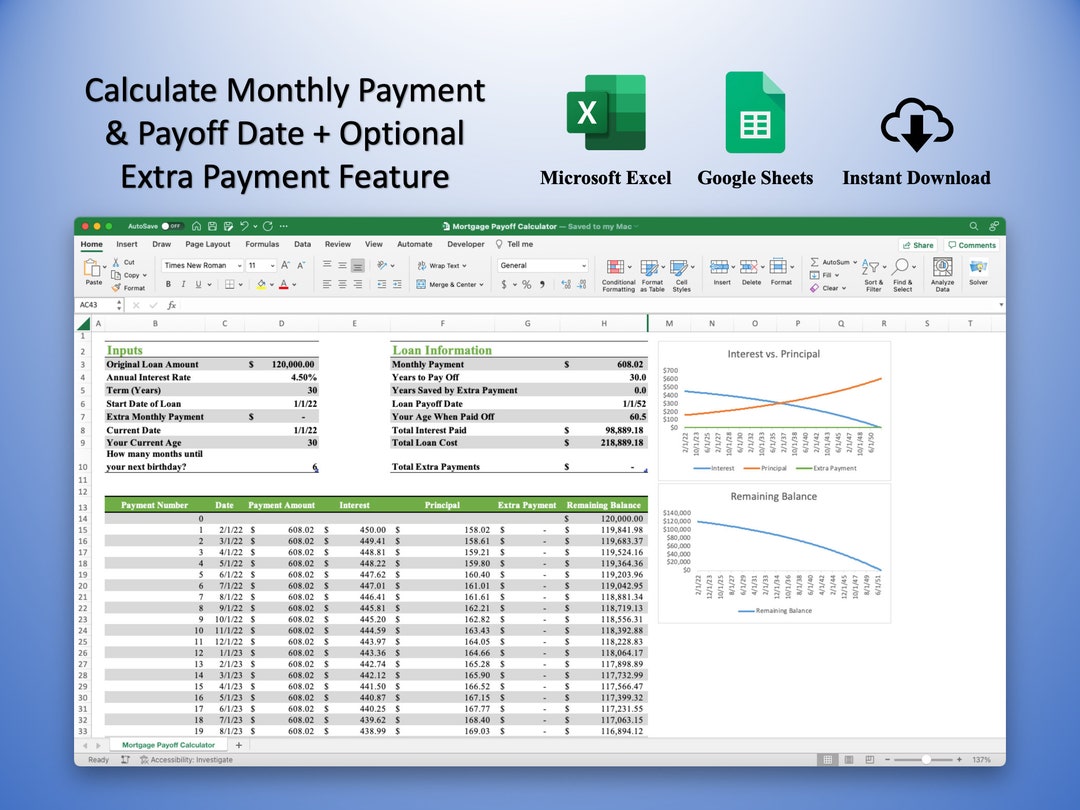
Now, the tools themselves. There are free calculators like the one on NerdWallet and the one from Bankrate. They're decent for a rough estimate but they treat every loan like a standard fixed-rate mortgage with no quirks. If you have an adjustable-rate mortgage, a loan with points prepaid at closing, or a balloon payment structure, those calculators will give you numbers that don't match reality. I've seen people walk away thinking they'd save $60,000 when the actual savings were more like $42,000 because the calculator didn't account for the way their loan's interest was calculated—some loans use a 360-day year method while others use a 365-day method, and that difference adds up over decades. If you want something closer to what a real loan officer would use, Excel or Google Sheets will get you there without much effort. Set up columns for payment number, beginning balance, interest portion, principal portion, ending balance, and cumulative principal paid. The formulas are straightforward. Interest for a given month equals the beginning balance times the annual rate divided by 12. Principal equals your total payment minus that interest amount. Ending balance is the beginning balance minus the principal portion. Repeat for each month. When you want to model extra payments, just reduce the ending balance by whatever amount you're adding and carry that forward. It takes about 15 minutes to set up and gives you complete control over the variables. I still use my own sheet for client work because I can plug in things like biweekly payment schedules, seasonal bonus payments, and refinance scenarios without dealing with a website that doesn't handle edge cases. There are some counter-intuitive things about early payoff that calculators rarely highlight. One is that the timing of your extra payments matters more than people think. If you make an extra payment in January of year one versus January of year five, the interest savings are dramatically different because of how amortization works. Money paid early has more time to compound against your principal. I had a client who made a $10,000 extra payment in year one and another identical $10,000 payment in year five. The first one saved him roughly $8,400 in interest. The second one saved him about $3,100. Same amount of money, totally different results. This is why most people focus on the wrong payments when they try to payoff early—they concentrate on the later years when the impact is smaller.
Get the Full Details
Another thing that catches people off guard: making extra payments doesn't always change your monthly payment amount. Some borrowers think that if they pay off their loan early, their monthly housing expense drops. It doesn't, unless they refinance or sell the house. Their property taxes and insurance stay the same. The principal and interest portion goes to zero, sure, but their total PITI payment doesn't decrease in the way people expect. I've had clients who stopped making extra payments because they thought the strategy wasn't working, when in fact it was working exactly as designed—they just didn't understand that their total monthly obligation wouldn't drop until they addressed the other components. There's also the matter of opportunity cost that no calculator will tell you. Paying down your mortgage early is a guaranteed return equal to your interest rate, minus whatever tax deduction you lose if you itemize. For someone in the 24 percent bracket with a 5.5 percent mortgage, the after-tax return is closer to 4.17 percent. That's a decent guaranteed return, but it's not automatically better than investing the same money in a diversified portfolio, especially over a long time horizon. I remember a case from 2021 where a borrower was pouring an extra $1,200 a month into their mortgage while their investment accounts were sitting nearly empty. They were so focused on being debt-free that they missed the fact they were taking on significant liquidity risk. If their job disappeared or they had a medical emergency, they'd have a paid-off house and no cash. That happened to someone I worked with, and it was a miserable few months. I always recommend keeping at least six months of expenses in liquid savings before aggressively paying down a mortgage. One more practical note about calculators and spreadsheets: they assume you'll actually stick to the plan. The moment you miss a month or scale back your extra payments, the timeline shifts. I've built payoff models for people who planned to pay off their loans in eight years and then life happened—kids, job changes, car repairs—and they ended up going back to minimum payments for two or three years. The damage to their payoff timeline from those gaps is real and irreversible. The best approach is to treat extra payments as something you do when you can, not as a rigid commitment that breaks everything if you miss it. A flexible strategy beats an ambitious one that falls apart.
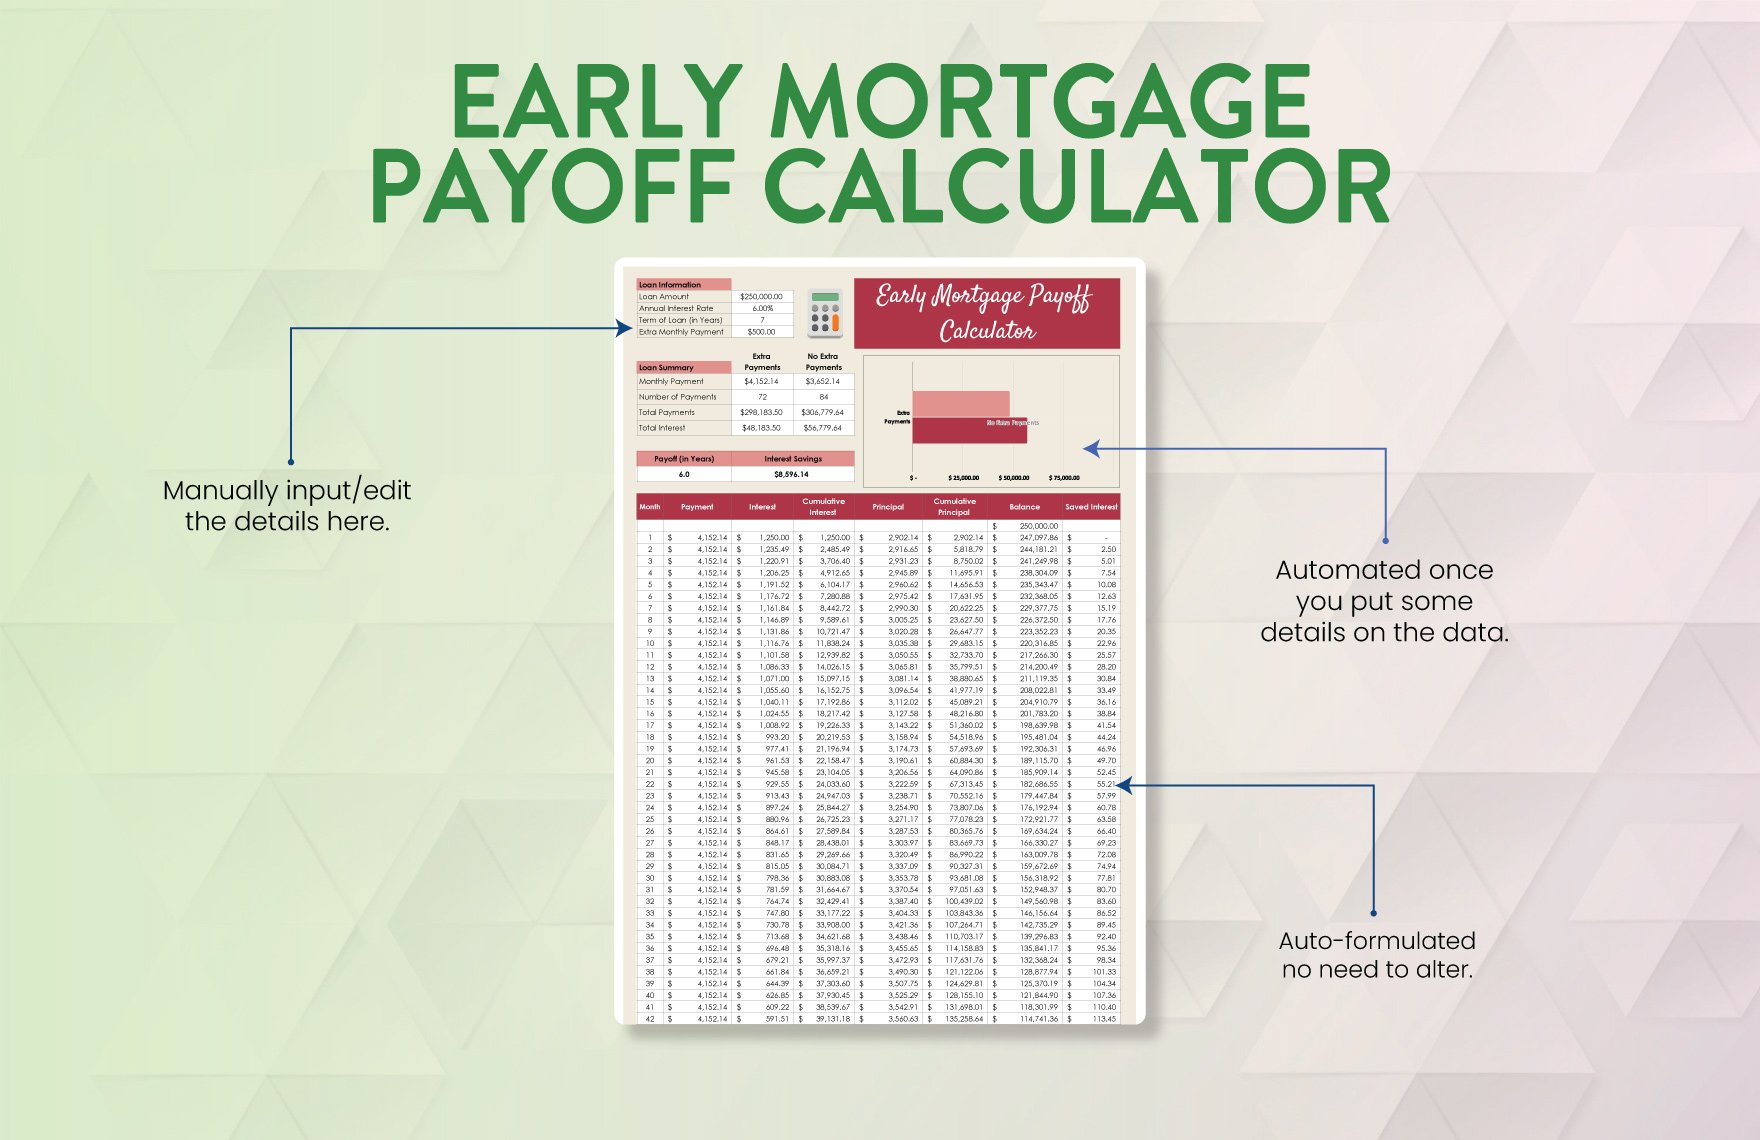
If you want to download something ready-made, there are several spreadsheet templates floating around from financial planning sites. Just make sure the template accounts for your specific loan terms before you fill in your numbers. The worst outcome is trusting a generic tool that doesn't match your loan's actual structure.