How to Actually Make These Work Instead of Letting Them Gather Dust
I printed my first budget worksheet three years ago and used it for exactly eleven days before I stopped. That is a normal outcome. The problem was never the worksheet itself, but the way it was set up. Most free printables you find online assume your income hits your account on the first of every month and that your bills arrive in neat, predictable order. That is not how most people's finances work. Easy Budget Planner Printable Worksheets can still be useful if you adapt them to real life instead of pretending your life matches the template. The trick is to print them, then modify them before you ever enter a dollar amount. Here is how I got it working for me after several failed attempts, and why the standard approach usually falls apart.
Getting Started With Easy Budget Planner Printable Worksheets
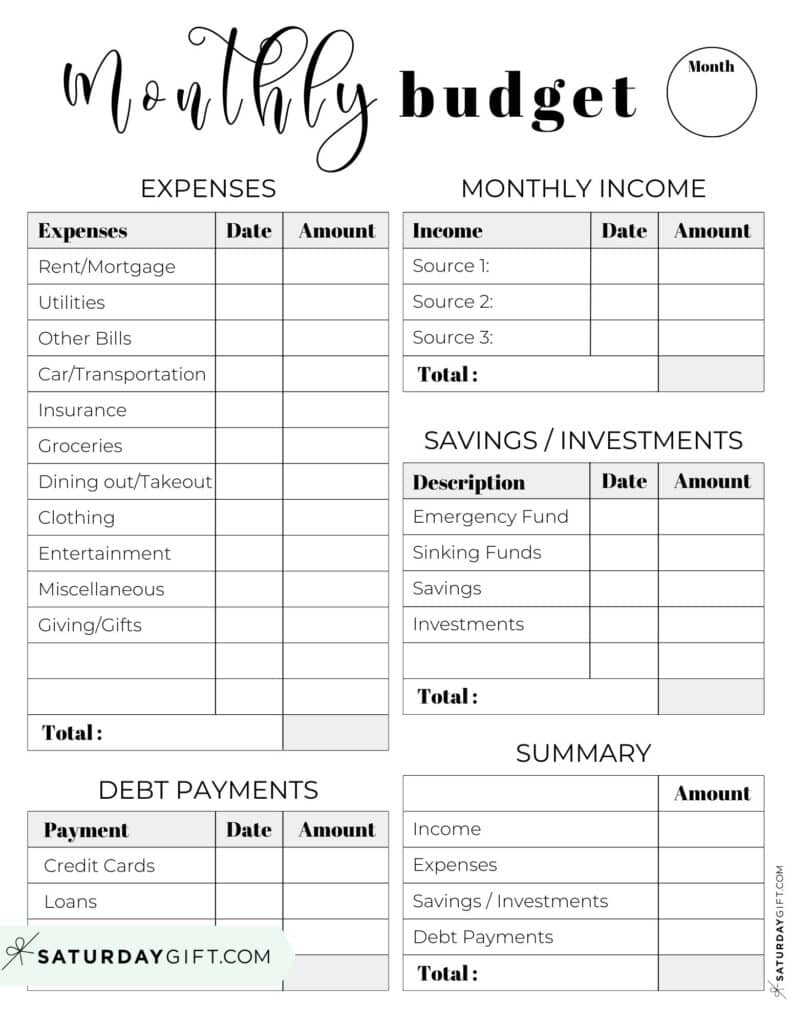
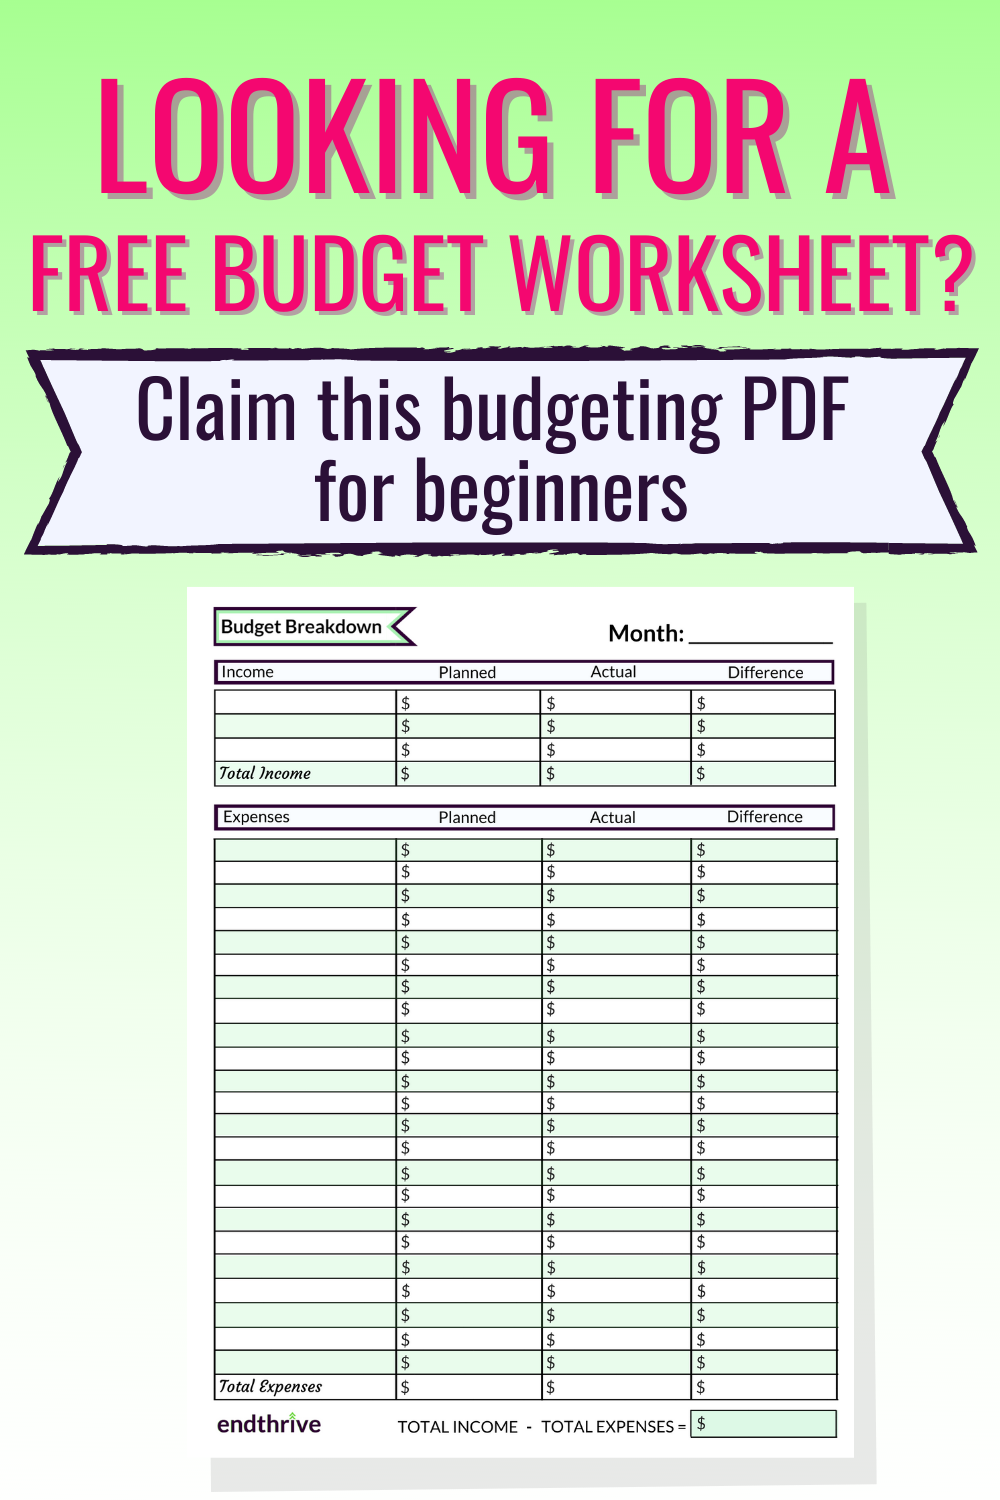
The basic workflow is straightforward. Download the worksheet, print it in color if you have access to a color printer since color coding makes reviewing weeks later significantly faster, and set up your tracking system before you fill anything in. Most printables use a monthly layout with columns for income, fixed expenses, variable expenses, savings, and a remainder category. The remainder is where everything goes wrong if you do not plan for it. I keep a simple system where I print four copies at the start of each quarter. One copy per month. I label the corner with the month and year immediately so I do not lose track later. Then I write in the actual pay dates from my employer instead of assuming biweekly or semimonthly. My employer pays on the 15th and the last day of the month, which means some months I get three paychecks and others I get two. A standard worksheet does not account for this, so I drew an extra column for it. This took about four minutes and prevented two months of confusion where I thought I had more money than I actually did. The key insight nobody mentions about these printables is that they are tracking tools, not forecasting tools. A printable worksheet tells you where your money went after the fact. It does not help you predict whether you will have enough for rent in a month where your car breaks down. For prediction, you need a rolling twelve-month view, which means keeping all your printouts together and drawing a line through each month as you complete it. This takes maybe ten extra minutes per month but gives you visibility into seasonal spending patterns that a single-month sheet completely hides.
Another detail that matters is how you handle cash transactions. If you pay for groceries or gas with cash, you need a separate envelope or jar system alongside the worksheet. The worksheet becomes unreliable the moment you have untracked spending because the remainder column will look healthy while your actual bank balance tells a different story. I started using a small receipts folder glued to the inside cover of my worksheet binder. This added maybe thirty seconds to my weekly review but eliminated the recurring problem of missing two hundred dollars a month in cash spending that I could never reconcile. When you fill in the categories, do not use broad labels like "shopping" or "food." Be specific. "Groceries at Trader Joe's" and "dining out atChipotle" serve different purposes in your analysis. You will notice patterns you would otherwise miss. I discovered through this method that I was spending roughly eighty dollars a month on lunch at a coffee shop near my office. That number came from a single column called "morning routine" and it took me four months to see it clearly. A generic category would have buried that figure inside a larger number and I would have kept spending it without understanding why. The main limitation of Easy Budget Planner Printable Worksheets is that they require consistent input. If you skip a week for three weeks in a row, the worksheet loses its value entirely and you end up with a stack of inaccurate records that are worse than nothing because they create false confidence. The alternative to this problem is either digital tracking with automated bank feeds or accepting that you need a different system during busy periods. I switched to a simple spreadsheet with bank import for a six-month stretch during a particularly chaotic work period and went back to printables when things stabilized. Both approaches work. The printable approach just demands more discipline.
Get the Full Details

The Setup Process
Start by gathering your last three months of bank statements and any bills you have recurring. You do not need perfect records. Approximate numbers are fine for the first pass. Write your total take-home pay across all sources at the top of the income section. Then list every fixed expense you can identify: rent, car payment, insurance premiums, subscriptions, minimum debt payments. Do not skip the small ones. The $4.99 streaming service and the $12.99 phone app matter when they add up to over one hundred dollars a year. Next, estimate your variable spending based on your actual history from those bank statements. Average the last three months for categories like groceries, utilities, gas, and entertainment. Round to the nearest five dollars. This gives you a realistic baseline instead of a hopeful one. Hope-based budgeting is the fastest way to make these worksheets fail within the first month. After that, allocate a portion of your income to savings and debt payoff beyond the minimums. Even twenty dollars a month counts. The printable format makes this visible in a way that automatic transfers sometimes do not because you have to physically decide where that money goes on the page. That small act of intention changes behavior more than most people expect.
Then calculate your remainder. Income minus fixed expenses minus variable estimates minus savings. If the remainder is negative, you have a structural problem that no worksheet will fix on its own. You need to either reduce expenses, increase income, or accept that your current spending level is unsustainable. The worksheet does not solve this. It reveals it. That is the actual function of these tools, which is why they feel useless to people who expect them to do something magical. Once the numbers are filled in, set a weekly review habit. Twelve minutes every Sunday is plenty. Check off bills paid, record any cash spending from your receipts folder, and note anything that deviates from your estimates. Deviations are more important than the numbers themselves because they tell you where your assumptions were wrong. Adjust the next month's estimates based on what you learned. This iterative process is what makes the system compound over time rather than degrade.
Advanced Adjustments for Irregular Income
If you are self-employed or your paycheck varies significantly month to month, the standard worksheet layout breaks down quickly. I ran into this when I started doing freelance consulting work alongside my salaried job. My income jumped from one month to the next in ways that made a fixed monthly budget meaningless. The workaround I use is a dual-track system. I keep the regular Easy Budget Planner Printable Worksheets for my salaried income, treating that portion as fixed and predictable. For the freelance portion, I use a separate rolling fund sheet where I allocate a percentage of each invoice to taxes, retirement, and operating expenses immediately upon receipt. This prevents the common mistake of spending freelance income as if it were permanent and then scrambling when tax season arrives. I also lowball my estimated freelance income by about fifteen percent. Freelance payments are unpredictable enough that even a conservative estimate feels uncomfortable at first, but it prevents the optimistic budget trap where you plan to spend money you have not actually received yet. I learned this the hard way after a client paid late in July and I had already committed that money to a quarterly insurance premium. The worksheet showed a healthy remainder. My bank account showed a overdraft fee. Those two numbers should never differ by more than fifty dollars in any given month.

The worksheets themselves cost nothing to produce, but the time investment is real. A complete monthly setup takes about twenty-five minutes for someone who has the system running smoothly. A new user should expect forty-five minutes to an hour for the first few cycles while they learn where their money actually goes. This is normal and the time decreases sharply after the third or fourth month as the categories become automatic. If it still takes more than thirty minutes after month four, you are probably overcomplicating the category structure. Seven to ten categories is the maximum most people can meaningfully track without burnout.
When This Approach Stops Working
There are honest situations where printable budget worksheets are the wrong tool. If you have significant debt with varying interest rates and are trying to optimize payoff strategies, a spreadsheet with formulas will save you dozens of hours compared to manual tracking. If you manage a household with multiple earners and shared accounts, the complexity exceeds what a single printable sheet can reasonably represent. If you have irregular income below forty thousand dollars annually, the mental overhead of maintaining a paper system may outweigh the benefits and an app with automated bank sync might be more appropriate despite its monthly subscription cost. The printable approach also assumes you have the discipline to engage with it weekly. Without that engagement, the sheets become decorative and the entire exercise produces no useful data. There is no automated reminder system. No transaction fetching. No alert when you exceed a category. You bring that accountability yourself, and that is the actual bottleneck for most people, not the quality of the worksheet design. I found that pairing the printables with a free banking app for daily balance checks gave me the automation I needed without abandoning the tangible benefits of a physical record. The app handles the transaction feed. The printable handles the categorization and planning. This hybrid approach cut my weekly review time from twenty-five minutes to about twelve minutes and made the system sustainable long-term. Most people skip the pairing step and either go all-in on apps or all-in on printables, and both extremes have clear tradeoffs that are worth acknowledging before you commit.