What the Easy Finance Workbook Actually Does
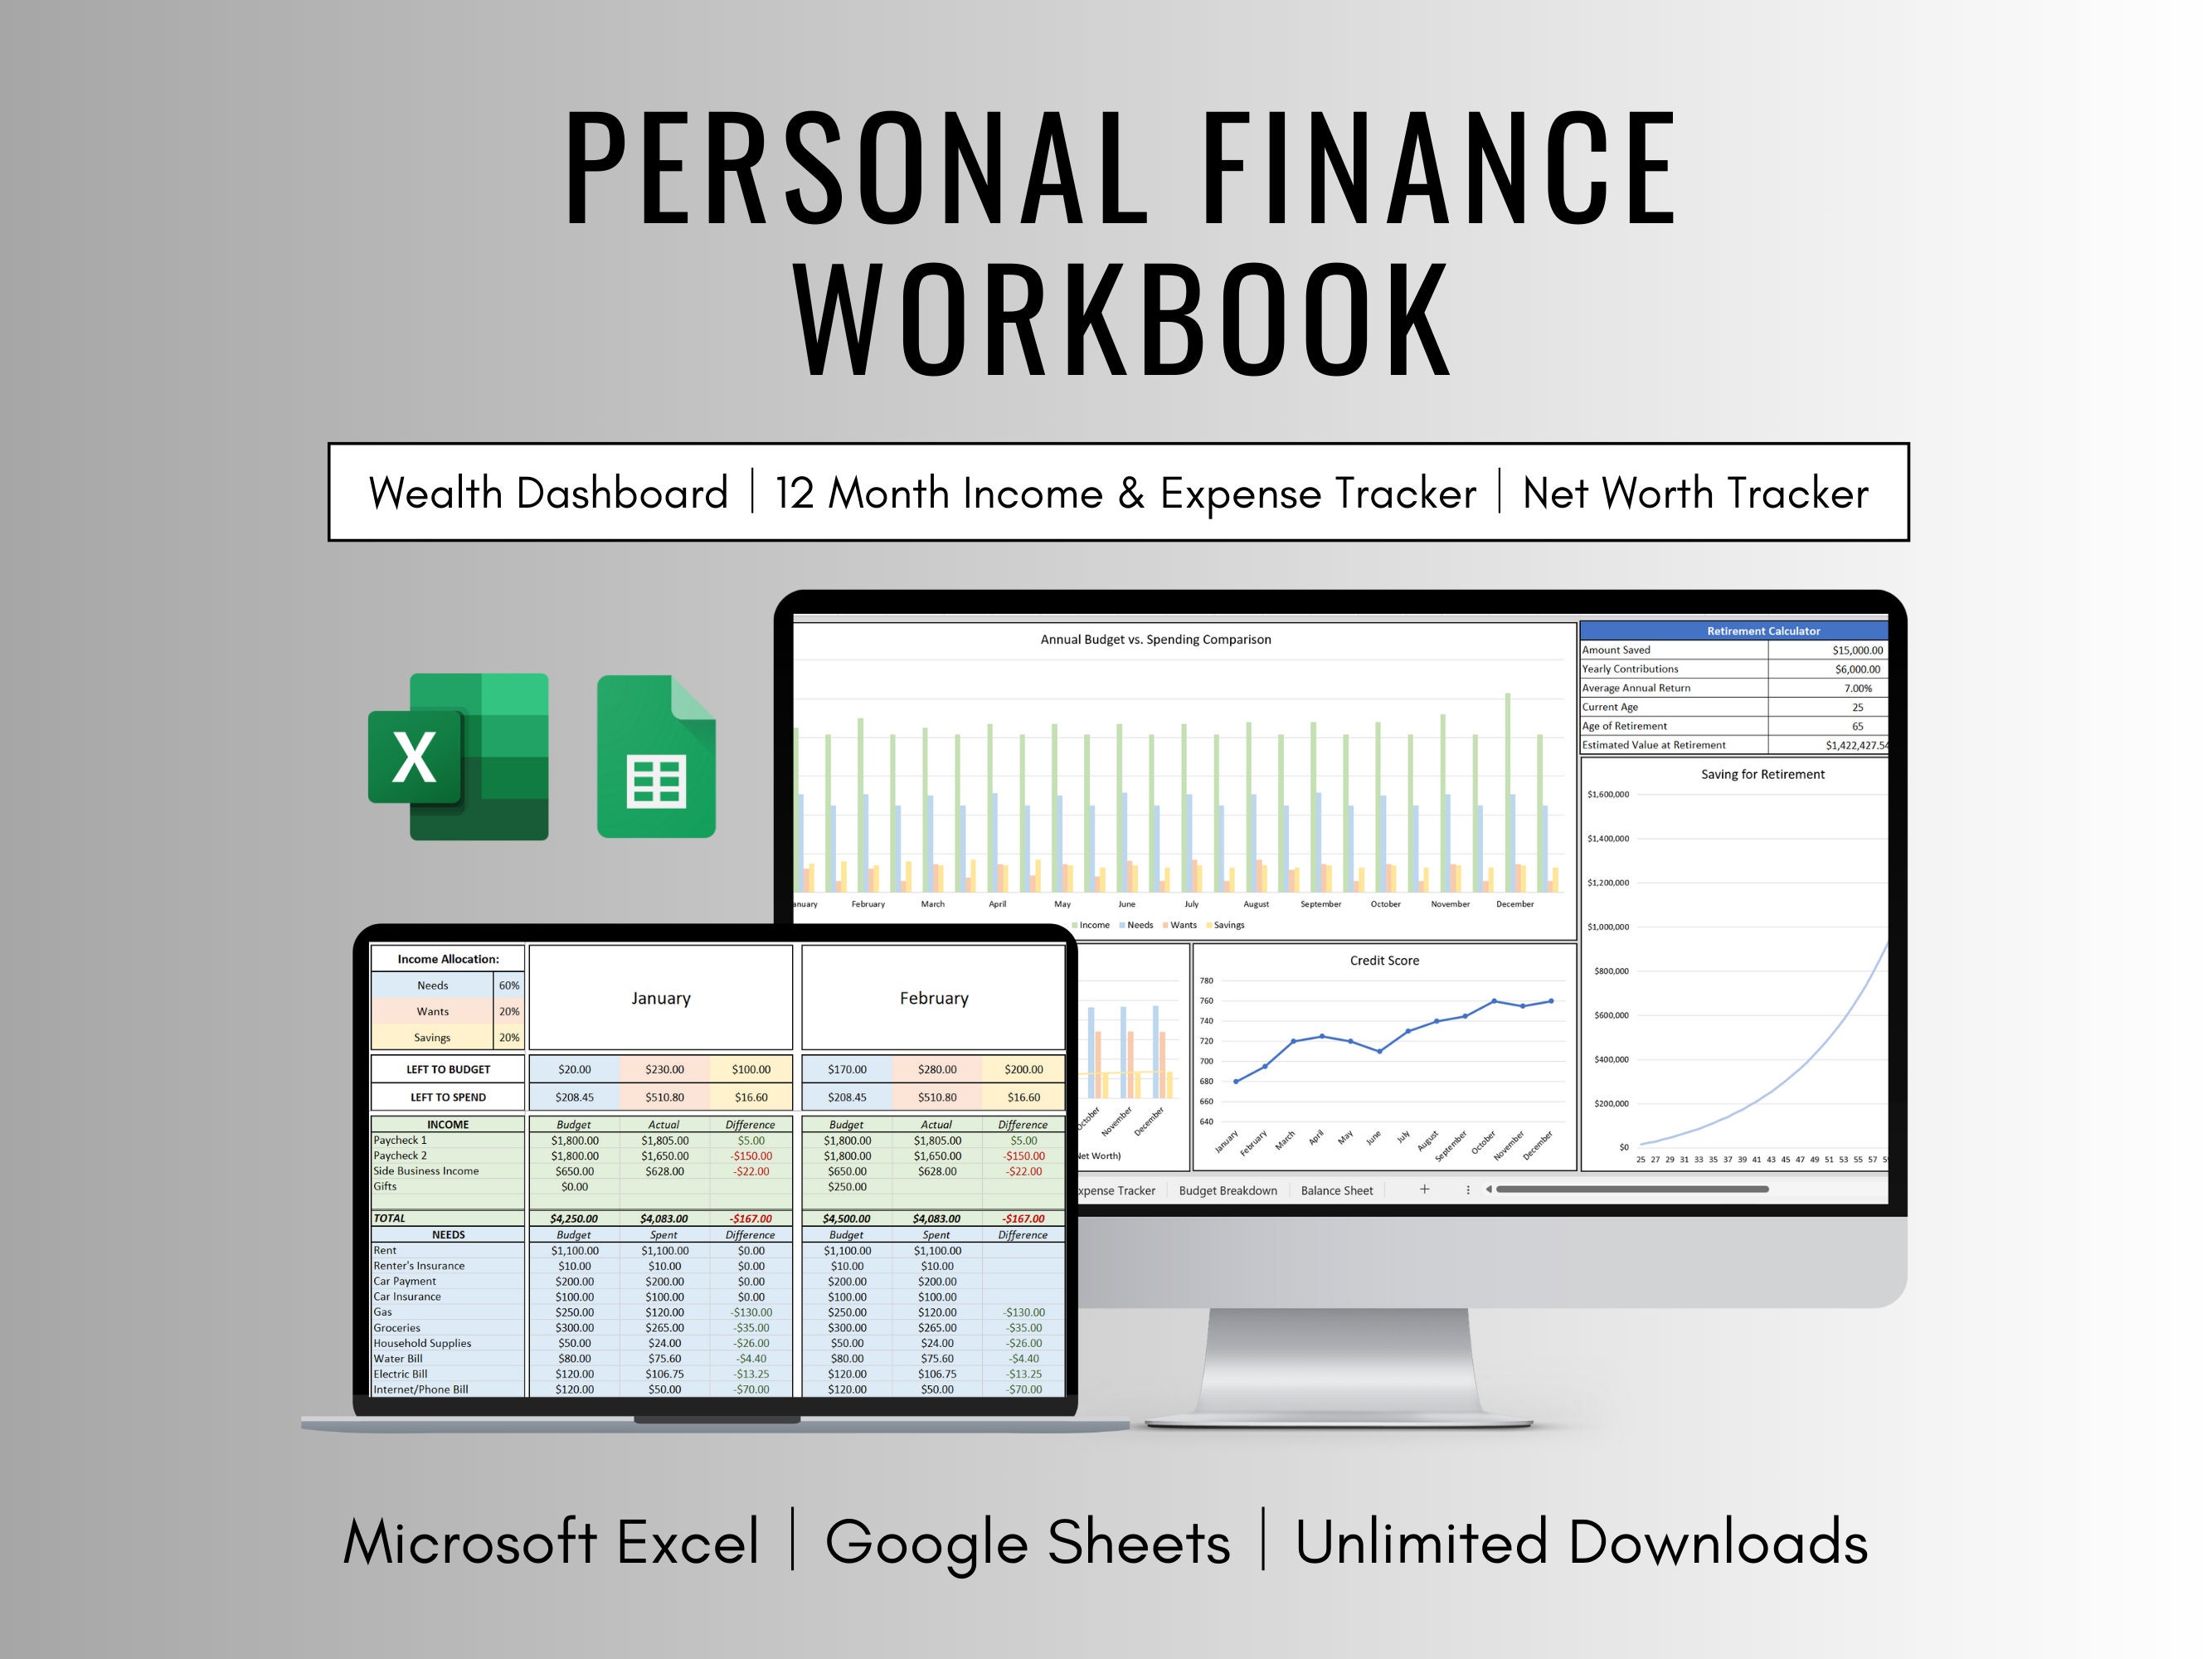
The Easy Finance Workbook is a spreadsheet-based personal finance management system. It organizes income, expenses, savings goals, and debt payoff tracking into a single file that updates automatically when you enter raw transaction data. Most people grab it from forums or finance sites and spend the first week trying to make it behave like a dedicated app. It doesn't do that. It's a workbook. You feed it data, it calculates balances, categories, and trends. Open the file and you'll see three or four main sheets depending on which version you downloaded. The Transaction Log is where you paste or type every entry. The Dashboard sheet pulls from that log and shows monthly totals, category breakdowns, and a savings rate calculation. A third sheet usually handles debt payoff schedules using the standard avalanche or snowball methods. Don't touch the formulas. Just fill in the input columns. I've watched at least two dozen people break their workbook in the first week because they moved columns, renamed headers, or accidentally deleted a sum range. The workbook uses INDEX-MATCH or XLOOKUP formulas that reference specific column positions. If you insert a column between two data fields, the lookup breaks and the Dashboard just shows blank cells. I learned this the hard way back in 2019 when I tried to add a "merchant" column between date and amount. The entire monthly summary turned to zeros. I had to rebuild the lookup table from scratch.
Here's the working method. Import your bank CSV exports directly into the Transaction Log. Don't manually type entries unless the amount is under fifty dollars. Most banks let you download a comma-separated file with date, description, and amount. Paste that into the log, align the columns to match the workbook's expected format, and hit calculate or refresh. The Dashboard updates within seconds.
How the Sheet Actually Calculates Your Numbers
The core logic is straightforward but not intuitive for someone who hasn't built spreadsheets before. Every transaction gets categorized by the workbook's preset list: housing, transportation, food, utilities, insurance, entertainment, debt payment, and savings. If a transaction doesn't match a category, it goes into "Uncategorized" and stays there until you sort it manually. The categorization happens through a combination of VLOOKUP tables and conditional formatting rules that flag recurring merchants. One thing beginners miss is that the workbook does not auto-categorize. It assigns transactions based on keyword matching against a predefined merchant map. So if your grocery store is listed as "Kroger" in the map but your bank statement says "KROGER #0412 Seattle WA," the match fails. You need to either add that variation to the merchant map or manually assign the category. I keep a running text file of every merchant name variation I encounter and merge it into the workbook's lookup sheet once a month. Takes about ten minutes and prevents the uncategorized pile from growing. The debt payoff section uses amortization formulas. You enter the balance, interest rate, and minimum payment for each debt, and the sheet projects when you'll be debt-free under different payment strategies. This is where the workbook actually earns its keep. Running these projections by hand takes twenty minutes per debt and half that if you don't mess up the formula. The sheet does it instantly and shows the interest savings between avalanche and snowball methods side by side.
Get the Full Details
The Parts That Actually Work Well
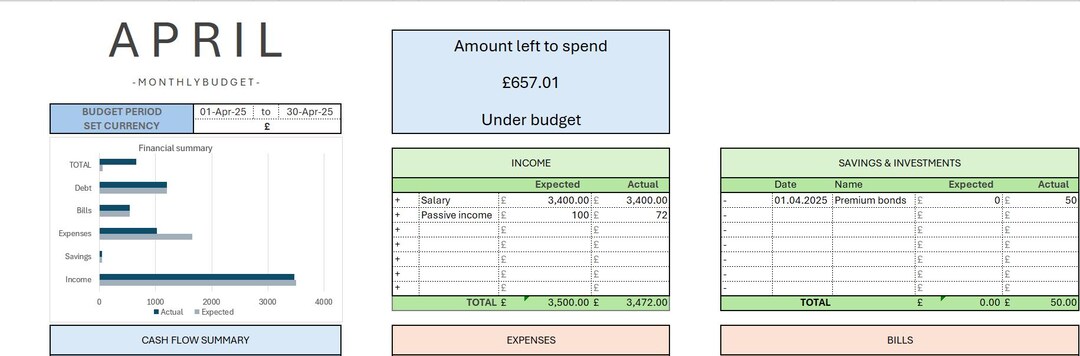
The monthly rollover feature is the strongest part. At the end of each month, you click a button that archives that month's transactions into a historical sheet and resets the current view. This keeps the active workspace fast and lets you pull up any past month for comparison. I've used this to spot spending drift that was invisible on a month-to-month basis. One year my dining out category jumped from an average of $220 a month to $410, and the historical view caught it before it became a quarter-long problem. The savings rate calculator is also useful because it uses actual deposited amounts rather than income minus expenses. Some people calculate savings as a percentage of take-home pay, which inflates the number if your expenses happen to spike in a given month. The workbook's method measures what actually moved into savings accounts each period, which is a more honest metric.
Where the Workbook Falls Apart
It doesn't connect to your bank. You have to import data manually. If you have more than fifteen transactions per day across all accounts, this becomes tedious after a few months. I got past this by using a simple power automate flow that emails my bank CSV attachments to a dedicated folder, then batch-importing them on weekends. That reduced my weekly data entry from about forty minutes to roughly fifteen minutes. Mobile access is another weakness. You can open the file on a phone but editing rows on a small screen is painful. I switched to using Google Sheets version of the same workbook structure so I could add transactions from my phone during the week and do the deeper review on my laptop on Sundays. The categorization system is also rigid. If your spending doesn't fit the preset categories, you either modify the category list (which can break existing formulas if you're not careful) or create custom columns outside the workbook's structure. I created a separate tag column for subscription services because the built-in categories lumped Netflix, Spotify, and my gym membership into different buckets that didn't reflect how I actually think about recurring costs.
A Practical Edge Case
Here's a scenario that isn't covered in the default setup. Let's say you pay rent with a credit card and get cashback rewards. The transaction appears as a credit purchase in your bank export, but the workbook treats it as a regular expense and ignores the cashback. Your net spending number is slightly wrong. The fix is to add a second entry for the cashback rebate as a negative expense in the same month, or to create a separate income category called "Rewards" and route all cashback there. Neither option is in the default workbook instructions. I discovered this after my calculated savings rate was consistently two percent lower than my actual bank balance growth, and it took me three weeks of line-by-line comparison to identify the cashback discrepancy. Another edge case involves joint accounts. If you and a partner share a checking account but track finances separately, the workbook's monthly summaries will include both incomes and expenses. The workaround is to add a "shared" flag column and filter the Dashboard by that flag, or maintain two separate workbooks and reconcile the shared account manually once a quarter. I went with the two-workbook approach because it kept the data clean and the reconciliation took maybe twenty minutes every three months.

Who Should and Shouldn't Use This
This works well if you want full visibility into your money without subscribing to a monthly service. It also works if you already live in spreadsheets and don't need mobile apps or automatic bank sync. It does not work if you want to set it up and forget it. The manual data entry is a real constraint, and people who skip a month tend to fall behind because catching up means re-entering thirty to sixty transactions at once. For people who fall into that category, a platform like Mint or Goodbudget might be more appropriate even though they cost money or have limitations of their own. The Easy Finance Workbook trades automation for transparency and control. You decide what gets tracked, how categories work, and what the calculations mean. That freedom has a price. The file is widely available across personal finance forums and download pages. Search for "Easy Finance Workbook Google Sheets" if you want the collaborative version that works better on mobile. The Excel version is more stable for complex debt calculations but harder to access outside your main computer. Pick the format that matches your workflow, not the one that sounds more professional.
Once you get past the initial setup friction, the workbook gives you a clear picture of where your money goes. It won't change your habits on its own. But it makes the numbers visible, and visibility is usually the first thing that actually changes spending behavior.