Opening a business is less romantic than people think
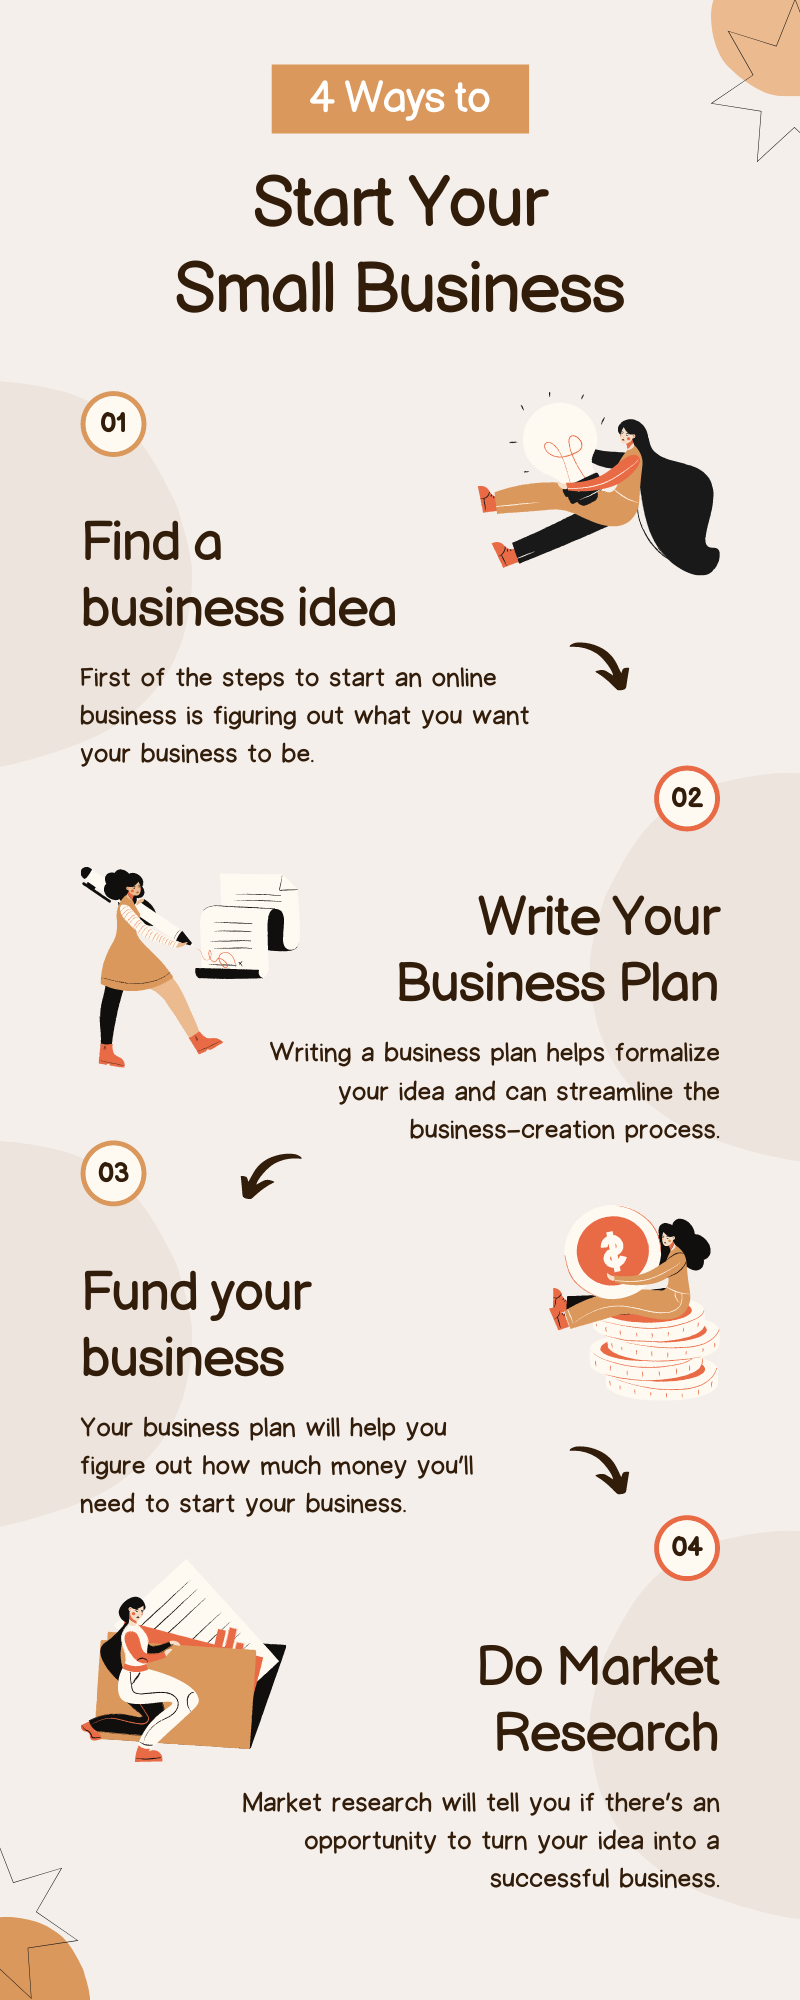
I opened a small consulting operation back in 2019, mostly because I was tired of explaining why my side projects didn't count as income on loan applications. The actual startup process took about three weeks from idea to first invoice, not including the two months I spent deciding what to call it. Naming takes way longer than paperwork. The legal side is straightforward if you don't overthink it. Register the entity, get an EIN, open a business bank account, set up basic bookkeeping. That's the skeleton. Everything else is noise until you have a customer.
Easy Ways To Start A Business Without Burning Through Savings
Most people I talk to who've been through this make the same mistake: they build inventory or software before validating demand. I saw a friend spend $8,000 on a custom e-commerce setup for a product he hadn't sold a single unit of. He was pre-selling on social media and had maybe 300 followers. The store went live with zero traffic and sat there for four months. The cheaper path is simpler. Pick a service you can deliver immediately with tools you already own. Write the offering down in plain language. Post it somewhere people in your target market actually hang out. Wait for the first inquiry. Once that happens, register the business, get the bank account, and invoice properly. Services scale slower than products but they also don't require upfront capital. A local handyman, a bookkeeper for small shops, a virtual assistant for real estate agents — these are boring businesses that work because they solve something people already pay strangers to do. The margin is in the repetition, not the innovation.
If you must sell a physical product, start with dropshipping or wholesale from suppliers who don't require minimum orders. I tried holding inventory once for a niche hobby product. The supplier raised prices 40% after six months, shipping took eight weeks, and I was eating the cost of returns because I hadn't priced them in. Now I only work with suppliers who let me cancel orders without penalty.
Get the Full Details

The paperwork nobody talks about
Here's what the YouTube tutorials skip: licenses. Depending on your city and industry, you might need a home occupation permit, a sales tax permit, a professional license, or all three. My first business required a local zoning check because I was working from home. The form was two pages but the response time from the clerk's office was three weeks. Factor that in. Insurance is another one people forget until something goes wrong. General liability is cheap if you shop around — I got a policy for about $40 a month covering a one-person operation. Skip it and one lawsuit wipes out the business and potentially your personal assets depending on how you structured things. Bookkeeping doesn't need to be fancy. A spreadsheet with date, description, amount, and category works fine for the first year. Upgrade to QuickBooks or Xero when monthly transactions hit roughly twenty per day. Before that, you're just wasting money on features you won't use.
Pricing is where most beginners lose money
I charged too little for years. Not out of strategy, just because I wasn't sure what the market would bear. The first client who paid my rate happily told me I was undercharging. It felt awkward to ask for more, but the math was clear: I was working forty hours a week for what amounted to minimum wage after taxes and expenses. Rate discovery is simple. Look at what competitors charge. Add fifteen percent. If nobody calls you in two weeks, you were still underpriced. If you get swamped and can't keep up, you were priced right or too low. The sweet spot is somewhere between those two signals. Don't offer discounts for early customers unless they're paying upfront for something that requires you to commit resources. First-ship discounts are fine. Lifetime discount locks are how you build a business that can't grow because everyone who walks in expects to pay half price.
Taxes and the structure question
Solo operators should look at S-Corp election once net income clears about sixty thousand a year. The self-employment tax savings usually outweigh the extra filing complexity. Before that threshold, a standard LLC or sole proprietorship is fine and cheaper to maintain. I learned this the hard way. Filed as a single-member LLC for three years while pulling in roughly eighty grand annually. The extra self-employment tax cost me about four thousand dollars I didn't need to pay. My accountant mentioned it during a quarterly review and I switched the election that month. Took two forms and a phone call to the IRS. Keep receipts for everything. Phone bill, internet, home office square footage, vehicle mileage if you drive for work. These compound over a year and the difference between itemized and unitemized can be significant at tax time. I stopped tracking mileage in 2021 because I was rounding to the nearest ten miles instead of logging actual trips. The audit trail matters more than convenience.

When to quit your day job
There's no universal rule. The standard advice is six months of living expenses saved and business revenue covering sixty percent of your overhead for three consecutive months. I followed that framework loosely and left a stable position when the numbers weren't quite there yet. It worked because the industry I was in was growing fast and clients were coming in faster than I could handle them. The version that didn't work for someone I know was exactly the opposite scenario: he left with solid savings but a niche service in a shrinking market. He lasted eleven months before winding down. Not a failure in the sense that he learned nothing, but the timeline was tighter than it needed to be. What matters is whether the business can sustain you without the safety net. Not whether it's profitable on paper. Profitable with client churn and late payments is a different thing than profitable with recurring revenue and clear margins.
The boring truth about growth
Most small businesses hit a ceiling around two to three million in revenue and stay there. That's not a bad thing. It means you're running a sustainable operation rather than a venture-scale machine that demands constant capital injection. The owners who break through usually do it by productizing their service or hiring people who can deliver the work without them involved in every detail. I stopped growing my own operation once I realized I was the bottleneck. Revenue could double if I hired two people, but I'd lose control over quality and my time would shift from delivery to management. The tradeoff wasn't worth it for where I was financially. Some people want that trajectory. That's fine. It's just not the only way a business can be successful. What most people need is a business that works. Not one that scales to IPO. The difference is smaller than startup culture makes it sound, and the stress level is dramatically lower when you're building something that funds your life rather than something that demands your life.