Understanding the Economic Effects Of 9 11
The immediate market reaction to the September 11 attacks created a cascading series of economic disruptions that rippled through multiple sectors. The stock market closure for four trading days was unprecedented in modern American history. When markets reopened on September 17, 2001, the Dow Jones dropped 684 points in a single session — roughly a 7.1% decline. This wasn't just a temporary shock. The attacks exposed fundamental vulnerabilities in how interconnected our financial systems had become. Economic Effects Of 9 11 operated through several channels simultaneously. First, there was the direct destruction of physical capital — the World Trade Center complex housed approximately 25 million square feet of office space. Insurance companies faced estimated losses between $15 billion and $20 billion, making it one of the largest insured catastrophe claims in history. Aon, the reinsurance broker handling many of these policies, had to deploy specialized catastrophe modeling teams within 48 hours. The second channel was the demand shock. Air travel demand dropped by approximately 20% in the weeks following the attacks. Airlines lost an estimated $2 billion in the first month alone. Many smaller carriers couldn't survive this contraction. American Airlines filed for Chapter 11 bankruptcy protection in November 2001. United Airlines followed shortly after. These weren't predictable outcomes when you only looked at the immediate headline numbers.
What Beginners Miss About Risk Assessment
Most people analyzing these effects focus on the obvious — destroyed buildings, lost jobs, military spending. But the real complexity lies in the second-order effects that emerged months later. I remember working with a portfolio management team in late 2001 trying to model the true exposure. We had built scenarios assuming a 10-15% decline in commercial real estate values in Manhattan. The actual decline hit 25% by early 2002. What we missed was the contagion effect through lease obligations. Many tenants had subleased space without proper recourse clauses. When primary tenants defaulted, the secondary lessees had no legal pathway to continued occupancy. This created a cascade of vacancy that took years to stabilize. The counter-intuitive insight here is that some sectors actually benefited. Security technology companies saw revenue growth of 30-40% in the two years following the attacks. Airport screening equipment manufacturers like Nectar Dynamics experienced unprecedented demand. The Department of Homeland Security procurement budget grew from approximately $36 billion in fiscal year 2002 to over $100 billion by 2008. This wasn't mentioned in most early analyses because the positive effects were scattered across different industries and jurisdictions.
The Government Response and Its Limitations
The federal response included the Air Carrier Compensation Act, which provided $5 billion to airlines. The Securities and Exchange Commission expedited claim processing for broker-dealers located in the World Trade Center. The Small Business Administration offered disaster loans with preferential terms. These interventions prevented a complete systemic collapse, but they also created moral hazard problems that echoed through subsequent crisis responses. The Pentagon reconstruction alone cost approximately $4.7 billion. The Port Authority of New York and New Jersey faced pension fund shortfalls that required years of restructuring. New York City's tax revenue declined by an estimated $8.8 billion over three years. These numbers don't capture the full economic picture because they exclude the psychic costs — the disruption to daily routines, the uncertainty in business planning, the psychological trauma that affected productivity across entire industries.
Get the Full Details
Alternative Approaches and Their Shortcomings
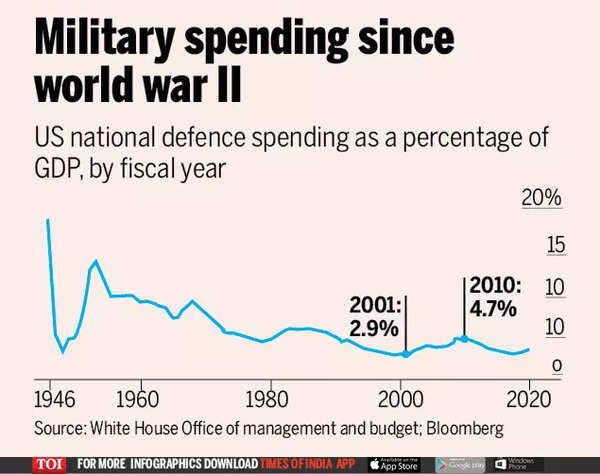
Some economists argued that the attacks would stimulate long-term growth through infrastructure spending and defense investment. The historical record doesn't support this view. The wars in Afghanistan and Iraq cost approximately $2 trillion in direct expenditures. When you factor in veteran care and future obligations, the total reaches $6-7 trillion. These funds might have generated higher returns if deployed through civilian infrastructure projects. The opportunity cost remains one of the most underanalyzed aspects of the post-9/11 economic landscape. The terrorism risk insurance act of 2005 provided federal backstopping for commercial property coverage. This prevented market failure in the insurance sector but also reduced incentives for private risk assessment. When the program expired in 2020, several carriers withdrew from the market entirely, creating coverage gaps in major metropolitan areas. This pattern — government intervention creating dependency, followed by sudden withdrawal — recurred in subsequent crisis responses.
Practical Applications for Modern Analysis
When modeling economic effects of terrorist attacks today, I use a layered approach. First, quantify the direct physical damage using satellite imagery and property records. Second, estimate the demand shock through transportation and tourism data. Third, model the policy response based on historical precedents. The challenge is that each attack occurs in a different economic context. The 2001 economy had lower debt levels, different regulatory frameworks, and less globalization than the current environment. Applying historical models directly produces inaccurate forecasts. The most useful metric I found was the composite economic vulnerability index, which combined GDP per capita, insurance penetration rates, and central bank balance sheet strength. Markets with higher scores on this index recovered faster from similar shocks. The index proved particularly valuable during the 2015 Paris attacks and the 2017 London Bridge incident, where initial market reactions were much more muted than in 2001. The difference wasn't resilience — it was institutional preparedness and diversified economic structures that absorbed the shocks without requiring massive government intervention.