Dealing With Foreign Currency Risk in Real Business
I spent about six years working corporate treasury for a mid-size manufacturing firm that exported heavily into Southeast Asia. The first time we got burned by economic exposure, it wasn't a dramatic market crash. It was a slow drift in the rupiah over three quarters that ate roughly 4.2% off our margins on contracts we'd already priced. Nobody on the floor had actually called it "economic exposure" at the time. We just called it "why are our Indonesian jobs losing money despite the sales staying flat." That's the thing about economic exposure refers to a category of risk that sounds simple when you read the textbook definition but feels completely different when your procurement costs move in a currency you didn't hedge and your revenue sits in another one. It's not the same as transaction exposure, which is straightforward. Transaction exposure hits you when you have a specific payable or receivable locked in a foreign currency and the rate moves before settlement. Economic exposure is broader and harder to pin down because it shows up in your competitive positioning, your cost structure, and your future cash flows all at once.
What Economic Exposure Actually Means in Practice
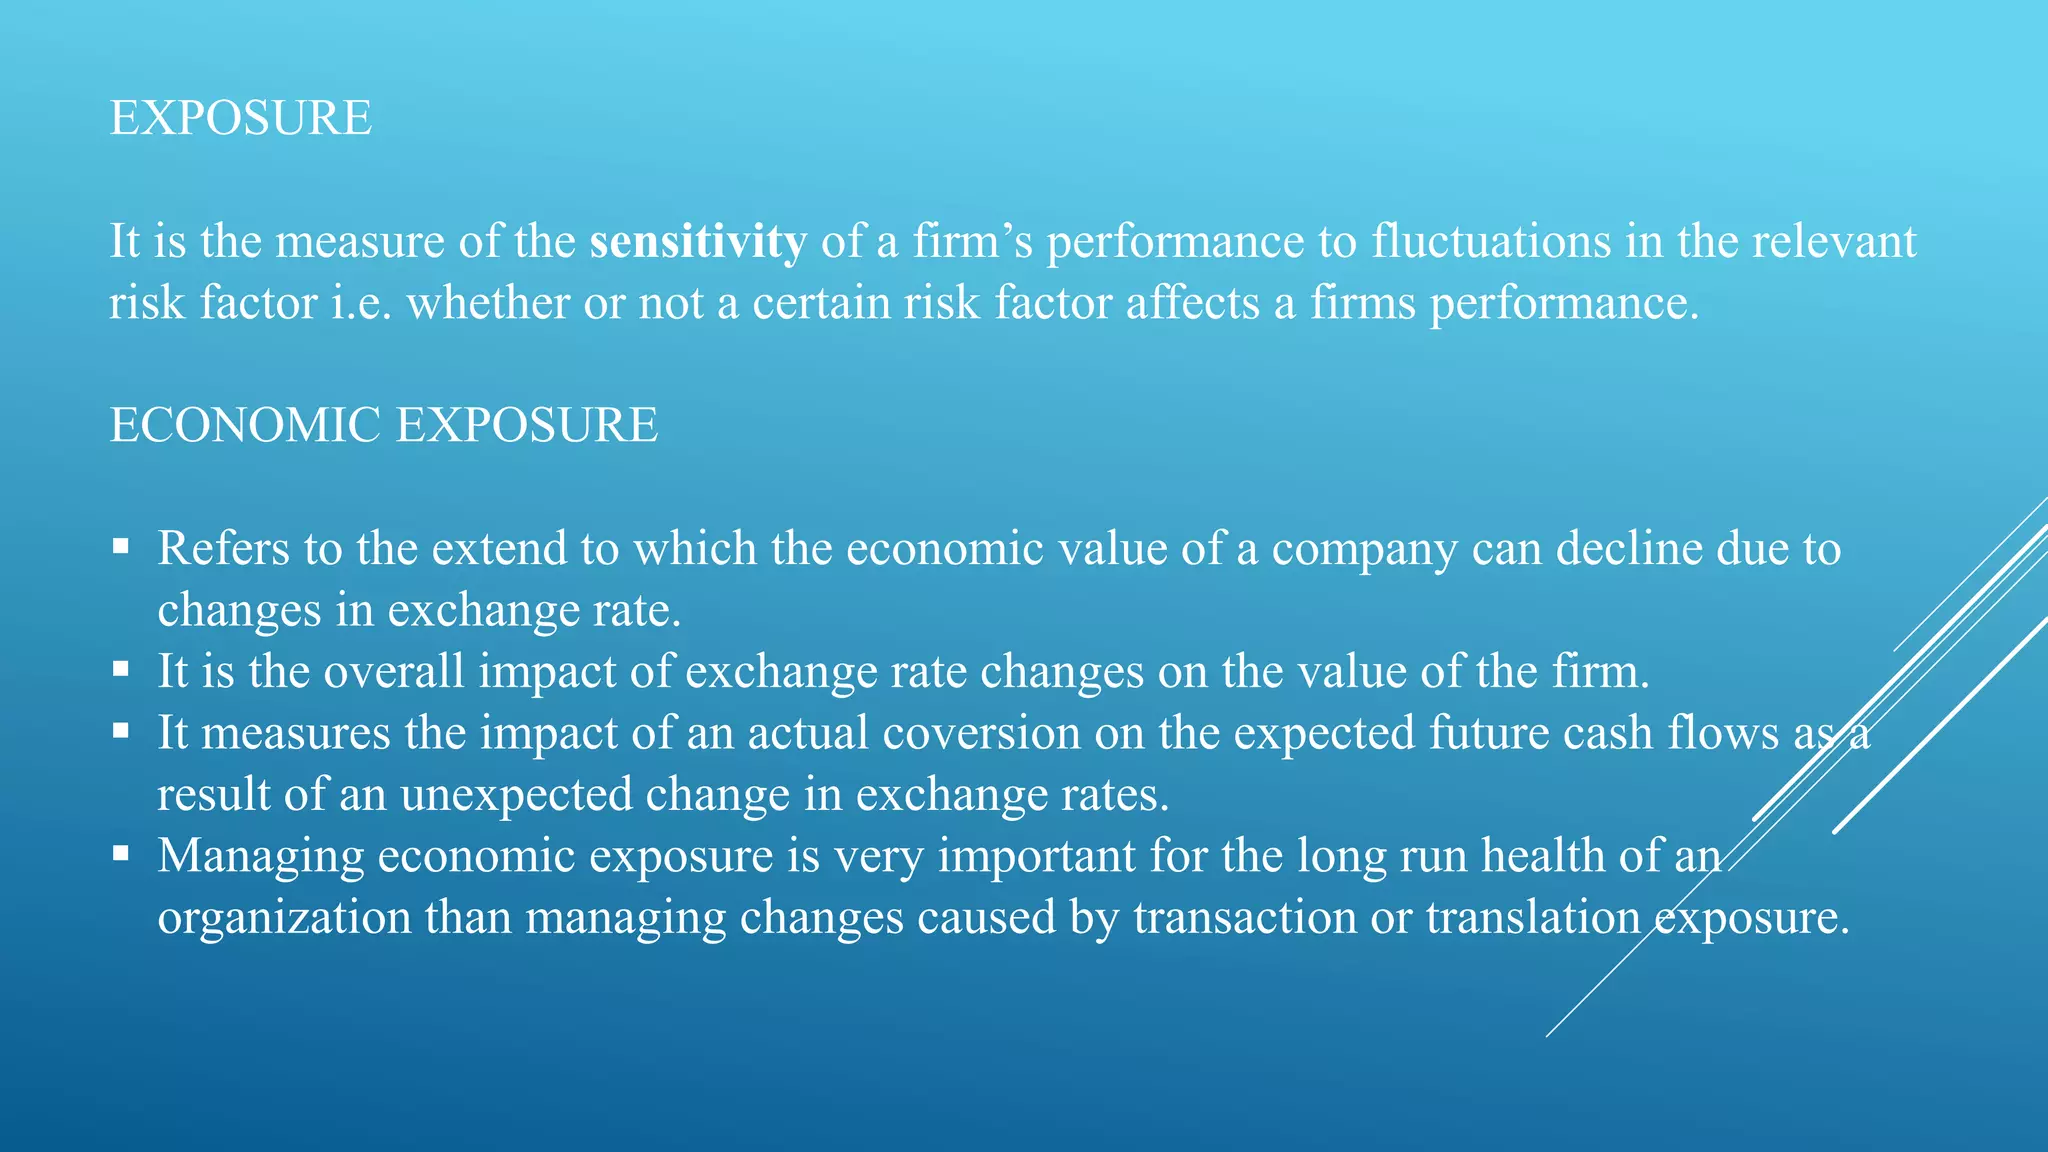
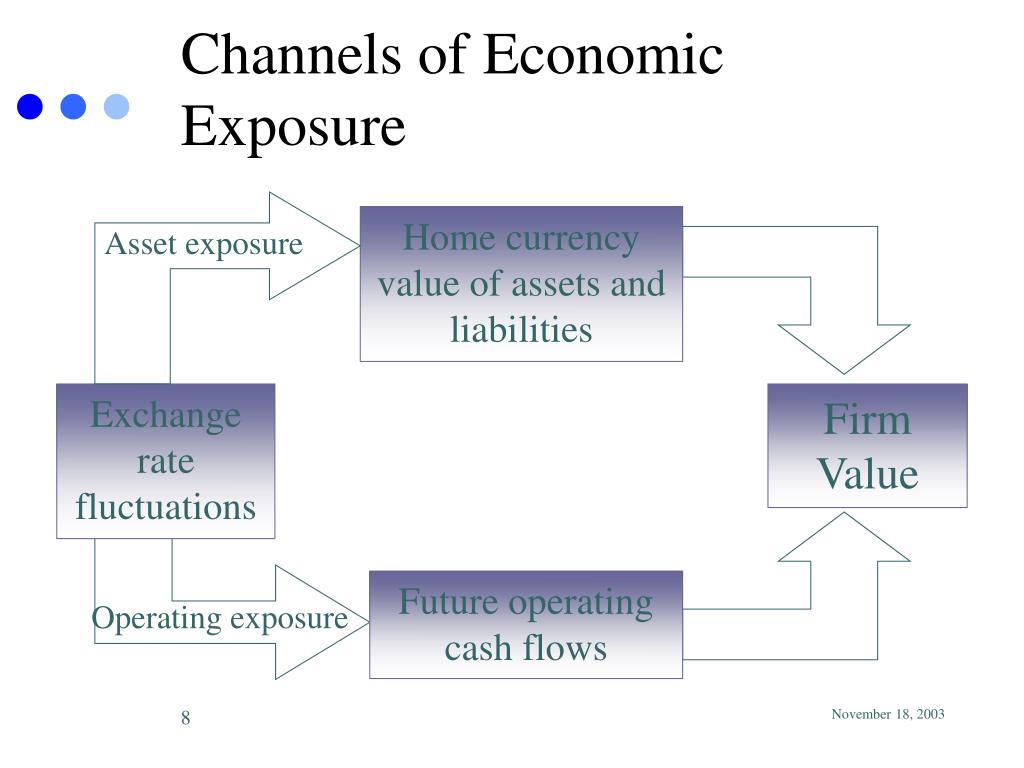
Economic exposure refers to the change in the present value of a firm's cash flows caused by unanticipated movements in exchange rates. It's forward-looking. It's not about a single invoice. It's about how your entire business model reacts when currencies shift in ways nobody predicted. The key word there is unanticipated. If the market already expects the yen to weaken and your competitors have already adjusted their pricing, the exposure has partly priced in. The real danger comes from moves that catch you flat-footed. There are three main channels through which it operates. The operating channel is the most important. This is where your revenues and costs are denominated in different currencies and they don't naturally offset each other. A classic example is a company that manufactures in China but sells primarily in the US market. When the yuan strengthens against the dollar, your production costs go up in dollar terms while your selling price either stays competitive or has to rise, which depresses volume. That margin squeeze is operating exposure in motion. The competitive channel is less obvious but just as damaging. Let's say you're a European automaker and the euro weakens significantly. Your Japanese competitors now find it cheaper to sell in Europe than they did before. They can undercut your pricing without sacrificing margin. You didn't lose money on a specific transaction. You lost market share because the currency shift changed the competitive landscape. That's economic exposure through the competitive channel. It doesn't show up on your income statement right away. It shows up six months later when you're wondering why your order book dropped.
The translation channel is the easiest to measure but often the least consequential for actual business decisions. This is when you consolidate foreign subsidiaries and the accounting exercise creates paper gains or losses. Treasury teams track this closely because it affects reported earnings, but it rarely drives real operational changes unless management is making decisions based purely on GAAP numbers rather than cash flow reality.
Get the Full Details
How to Measure It Without Getting Lost in Models
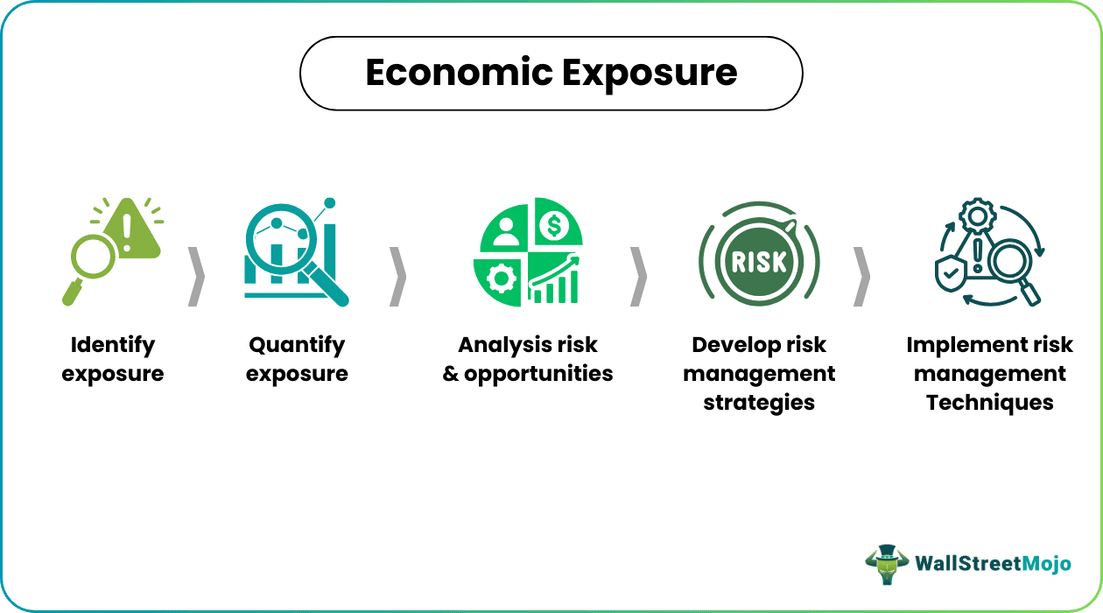
The academic approach uses regression analysis. You regress your firm's stock price or cash flows against changes in relevant exchange rates and isolate the sensitivity coefficient. The beta you get out of that regression tells you roughly how much value you lose or gain for a one percent move in the currency pair. It's useful. It's also often misleading if you apply it blindly. The problem with the regression approach is that it assumes relationships are stable over time. They aren't. A beta estimated from five years of data in a low-volatility period might look reassuring. Then a central bank announces an unexpected policy shift and that beta becomes irrelevant overnight. I learned this the hard way when our model predicted a 0.3 million dollar impact from a five percent rupiah move. The actual impact came in at 1.8 million because the move triggered secondary effects: our suppliers in Thailand repriced their components, our Indonesian distributor demanded contract renegotiation, and we had to expedite shipments from our Chinese factory at premium freight rates. The model captured the direct currency effect. It missed the network effects rippling through the supply chain. A more practical approach starts with mapping. Write down every revenue stream and every cost line item. Flag which currency each one is denominated in. Then calculate the net exposure for each currency pair. If you earn euros and pay costs in dollars, your net exposure is positive euro. If you earn dollars and pay costs in euros, it's negative euro. This gives you a first-order estimate that's usually good enough for initial hedging decisions.
From there, stress test the exposure against plausible scenarios. Not wild hypotheticals. Plausible ones. A 10 percent move in a major currency over six months. A 15 percent move against an emerging market currency over the same period. Run these scenarios through your budget model and see which lines of the P&L break first. The ones that do are where your actual economic exposure lives.
The Hedging Problem Nobody Talks About
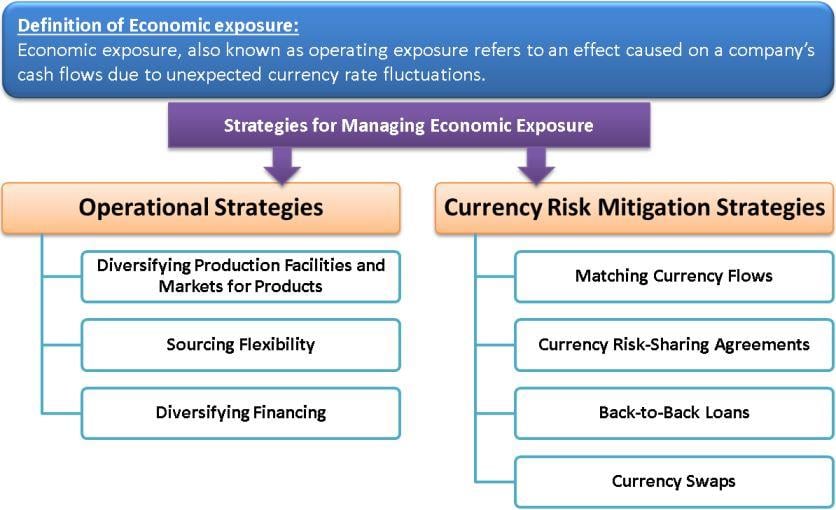
You can hedge transaction exposure with forwards, options, and swaps. That's standard treasury work. Hedging economic exposure is fundamentally different and most companies handle it badly because they try to use the wrong tools for the job. Financial derivatives hedge financial exposures. Economic exposure is operational. If you want to reduce it, you adjust operations. Diversify your sourcing. Move production. Renegotiate pricing contracts. Change the currency denomination of your sales invoices. These are real business decisions that take time and money but they address the root cause rather than just offsetting the symptom on a balance sheet. I've seen companies waste significant resources trying to hedge operating exposure with currency options. A six-month option on a currency pair gives you protection against a specific timeframe. Economic exposure doesn't expire in six months. It's structural. Buying derivatives to hedge it is like putting a bucket under a leaky roof instead of fixing the roof. It might help in the short term. It won't solve the underlying problem and the cost compounds over time.
The workaround I ended up using at my old company was a combination of natural hedging and strategic pricing. We matched revenue and cost currencies where possible by sourcing locally in markets where we sold. We built currency adjustment clauses into long-term contracts so prices could shift with the underlying exchange rates. We diversified our manufacturing footprint across three countries in two currency zones so no single move could destabilize our cost base. It wasn't elegant. It took about fourteen months to implement properly. But it reduced our quarterly earnings volatility from currency moves by roughly sixty percent without any derivative hedging costs.
Common Mistakes That Cost Us Money
The first mistake is confusing economic exposure with transaction exposure and treating them identically. They require different responses. Transaction exposure gets a financial hedge. Economic exposure gets an operational strategy. Mixing them up leads to overhedging on transactions and underhedging on the broader business risk that actually matters. The second mistake is assuming that because a currency has been stable for a while, economic exposure is zero. Stability is not the same as absence of risk. The moment you decide you don't need to manage exposure because the rate has been range-bound for eighteen months is usually the moment before a meaningful move. I've watched treasurers get complacent during calm periods and then scramble when volatility returns. The rupiah in 2018 and 2019 looked well-behaved. It wasn't. The third mistake is measuring exposure at the aggregate corporate level and missing the segment-level detail. A company might look neutral on the euro-dollar pair at the consolidated level. But if one division earns euros and spends dollars and another division earns dollars and spends euros, those positions offset on paper. In reality, they may face different competitive dynamics, different pricing power, and different ability to pass through currency movements to customers. The offset is accounting fiction. The risk is real at the operating unit level.
When Economic Exposure Is Basically Unmanageable
Some businesses face structural exposure that can't be hedged away. A company that imports nearly all its inputs from a single currency zone and sells into multiple currencies has a fundamental mismatch. No amount of operational tweaking eliminates it entirely. The best you can do is minimize the gap and accept that some baseline risk will always exist. Small firms without dedicated treasury function face the same problem differently. They lack the scale to diversify sourcing meaningfully. They can't negotiate currency adjustment clauses into customer contracts. They can't afford sophisticated modeling. Their economic exposure is often larger relative to their cash reserves than it would be for a bigger competitor, which means a single adverse currency move can be existential rather than merely inconvenient. For these companies, the most practical tool is sometimes just keeping pricing flexible and maintaining enough cash buffer to absorb a reasonable shock.
Bottom Line on What This Actually Requires
Economic exposure is real. It's not accounting noise. It's not something you can ignore because it doesn't appear on a single invoice. But it's also not something you solve with a single financial instrument or a quarterly review. It requires ongoing operational awareness, regular stress testing, and the willingness to make business decisions that improve your natural hedging position even when the currency environment looks calm. The companies that handle it well don't eliminate exposure. They understand it, monitor it, and adjust their operations faster than the market adjusts to the same moves. I spent about six years working corporate treasury for a mid-size manufacturing firm that exported heavily into Southeast Asia. The first time we got burned by economic exposure, it wasn't a dramatic market crash. It was a slow drift in the rupiah over three quarters that ate roughly 4.2% off our margins on contracts we'd already priced. Nobody on the floor had actually called it "economic exposure" at the time. We just called it "why are our Indonesian jobs losing money despite the sales staying flat." That's the thing about economic exposure refers to a category of risk that sounds simple when you read the textbook definition but feels completely different when your procurement costs move in a currency you didn't hedge and your revenue sits in another one. It's not the same as transaction exposure, which is straightforward. Transaction exposure hits you when you have a specific payable or receivable locked in a foreign currency and the rate moves before settlement. Economic exposure is broader and harder to pin down because it shows up in your competitive positioning, your cost structure, and your future cash flows all at once.
What Economic Exposure Actually Means in Practice
Economic exposure refers to the change in the present value of a firm's cash flows caused by unanticipated movements in exchange rates. It's forward-looking. It's not about a single invoice. It's about how your entire business model reacts when currencies shift in ways nobody predicted. The key word there is unanticipated. If the market already expects the yen to weaken and your competitors have already adjusted their pricing, the exposure has partly priced in. The real danger comes from moves that catch you flat-footed. There are three main channels through which it operates. The operating channel is the most important. This is where your revenues and costs are denominated in different currencies and they don't naturally offset each other. A classic example is a company that manufactures in China but sells primarily in the US market. When the yuan strengthens against the dollar, your production costs go up in dollar terms while your selling price either stays competitive or has to rise, which depresses volume. That margin squeeze is operating exposure in motion. The competitive channel is less obvious but just as damaging. Let's say you're a European automaker and the euro weakens significantly. Your Japanese competitors now find it cheaper to sell in Europe than they did before. They can undercut your pricing without sacrificing margin. You didn't lose money on a specific transaction. You lost market share because the currency shift changed the competitive landscape. That's economic exposure through the competitive channel. It doesn't show up on your income statement right away. It shows up six months later when you're wondering why your order book dropped.
The translation channel is the easiest to measure but often the least consequential for actual business decisions. This is when you consolidate foreign subsidiaries and the accounting exercise creates paper gains or losses. Treasury teams track this closely because it affects reported earnings, but it rarely drives real operational changes unless management is making decisions based purely on GAAP numbers rather than cash flow reality.
How to Measure It Without Getting Lost in Models
The academic approach uses regression analysis. You regress your firm's stock price or cash flows against changes in relevant exchange rates and isolate the sensitivity coefficient. The beta you get out of that regression tells you roughly how much value you lose or gain for a one percent move in the currency pair. It's useful. It's also often misleading if you apply it blindly. The problem with the regression approach is that it assumes relationships are stable over time. They aren't. A beta estimated from five years of data in a low-volatility period might look reassuring. Then a central bank announces an unexpected policy shift and that beta becomes irrelevant overnight. I learned this the hard way when our model predicted a 0.3 million dollar impact from a five percent rupiah move. The actual impact came in at 1.8 million because the move triggered secondary effects: our suppliers in Thailand repriced their components, our Indonesian distributor demanded contract renegotiation, and we had to expedite shipments from our Chinese factory at premium freight rates. The model captured the direct currency effect. It missed the network effects rippling through the supply chain. A more practical approach starts with mapping. Write down every revenue stream and every cost line item. Flag which currency each one is denominated in. Then calculate the net exposure for each currency pair. If you earn euros and pay costs in dollars, your net exposure is positive euro. If you earn dollars and pay costs in euros, it's negative euro. This gives you a first-order estimate that's usually good enough for initial hedging decisions.
From there, stress test the exposure against plausible scenarios. Not wild hypotheticals. Plausible ones. A 10 percent move in a major currency over six months. A 15 percent move against an emerging market currency over the same period. Run these scenarios through your budget model and see which lines of the P&L break first. The ones that do are where your actual economic exposure lives.
The Hedging Problem Nobody Talks About
You can hedge transaction exposure with forwards, options, and swaps. That's standard treasury work. Hedging economic exposure is fundamentally different and most companies handle it badly because they try to use the wrong tools for the job. Financial derivatives hedge financial exposures. Economic exposure is operational. If you want to reduce it, you adjust operations. Diversify your sourcing. Move production. Renegotiate pricing contracts. Change the currency denomination of your sales invoices. These are real business decisions that take time and money but they address the root cause rather than just offsetting the symptom on a balance sheet. I've seen companies waste significant resources trying to hedge operating exposure with currency options. A six-month option on a currency pair gives you protection against a specific timeframe. Economic exposure doesn't expire in six months. It's structural. Buying derivatives to hedge it is like putting a bucket under a leaky roof instead of fixing the roof. It might help in the short term. It won't solve the underlying problem and the cost compounds over time.

The workaround I ended up using at my old company was a combination of natural hedging and strategic pricing. We matched revenue and cost currencies where possible by sourcing locally in markets where we sold. We built currency adjustment clauses into long-term contracts so prices could shift with the underlying exchange rates. We diversified our manufacturing footprint across three countries in two currency zones so no single move could destabilize our cost base. It wasn't elegant. It took about fourteen months to implement properly. But it reduced our quarterly earnings volatility from currency moves by roughly sixty percent without any derivative hedging costs.
Common Mistakes That Cost Us Money
The first mistake is confusing economic exposure with transaction exposure and treating them identically. They require different responses. Transaction exposure gets a financial hedge. Economic exposure gets an operational strategy. Mixing them up leads to overhedging on transactions and underhedging on the broader business risk that actually matters. The second mistake is assuming that because a currency has been stable for a while, economic exposure is zero. Stability is not the same as absence of risk. The moment you decide you don't need to manage exposure because the rate has been range-bound for eighteen months is usually the moment before a meaningful move. I've watched treasurers get complacent during calm periods and then scramble when volatility returns. The rupiah in 2018 and 2019 looked well-behaved. It wasn't. The third mistake is measuring exposure at the aggregate corporate level and missing the segment-level detail. A company might look neutral on the euro-dollar pair at the consolidated level. But if one division earns euros and spends dollars and another division earns dollars and spends euros, those positions offset on paper. In reality, they may face different competitive dynamics, different pricing power, and different ability to pass through currency movements to customers. The offset is accounting fiction. The risk is real at the operating unit level.
When Economic Exposure Is Basically Unmanageable
Some businesses face structural exposure that can't be hedged away. A company that imports nearly all its inputs from a single currency zone and sells into multiple currencies has a fundamental mismatch. No amount of operational tweaking eliminates it entirely. The best you can do is minimize the gap and accept that some baseline risk will always exist. Small firms without dedicated treasury function face the same problem differently. They lack the scale to diversify sourcing meaningfully. They can't negotiate currency adjustment clauses into customer contracts. They can't afford sophisticated modeling. Their economic exposure is often larger relative to their cash reserves than it would be for a bigger competitor, which means a single adverse currency move can be existential rather than merely inconvenient. For these companies, the most practical tool is sometimes just keeping pricing flexible and maintaining enough cash buffer to absorb a reasonable shock.
Bottom Line on What This Actually Requires
Economic exposure is real. It's not accounting noise. It's not something you can ignore because it doesn't appear on a single invoice. But it's also not something you solve with a single financial instrument or a quarterly review. It requires ongoing operational awareness, regular stress testing, and the willingness to make business decisions that improve your natural hedging position even when the currency environment looks calm. The companies that handle it well don't eliminate exposure. They understand it, monitor it, and adjust their operations faster than the market adjusts to the same moves.
