What Actually Drives Economic Growth
Most people think economic growth is just about GDP going up. It's more complicated than that, and honestly, the standard textbook definition doesn't help you understand what's actually happening on the ground. Incomplete sentence, I know. But that's kind of the point. Economic growth doesn't take place when a country just "does stuff." It takes place when a country increases its productive capacity over time. Output rises. Incomes rise. The economy gets bigger in real terms, not nominal. The basic mechanism involves capital accumulation, labor force participation, and technological progress. That's the Solow model in a nutshell. But the Solow model is a simplification. It assumes perfect competition, constant returns to scale, and frictionless markets. None of that exists in the real world.
Here's what I've seen in practice: countries often chase GDP targets without building the infrastructure that actually supports sustainable growth. I worked with a government advisory team in Southeast Asia a few years back. They were hitting their growth numbers, but the data looked wrong. Turns out they were counting informal sector activity in ways that doubled certain transactions. A simple supply chain good would get counted three times. The GDP growth figure was solid but essentially meaningless for policy purposes. The fix was building a proper input-output table that could track intermediate goods separately from final goods. This usually takes about six weeks of data collection and another four weeks for analysis. Most governments skip this step entirely because it requires cooperation from agencies that don't want to share data with each other. Productive capacity is the key phrase here. Growth without capacity building is just inflation in disguise. You can print money, devalue your currency, and temporarily boost nominal GDP. The real test is whether the economy can produce more goods and services with the same or fewer inputs.
The Components You Actually Need to Track
Investment matters. But not just any investment. I've seen entire economies absorb massive capital inflows and still stagnate because the investment went into non-tradable sectors like real estate speculation rather than manufacturing or infrastructure. The distinction between tradable and non-tradable sectors is critical and almost always overlooked. Labor force quality matters more than labor force size. A country can have a growing population but stagnant or declining productivity per worker. Education systems, healthcare access, and skills training all feed into this. The correlation between median years of schooling and GDP per capita growth is roughly 0.6 across developing economies. That's a meaningful relationship but far from deterministic. Technological adoption drives most of the variance in growth rates between similar economies. Two countries can start at the same income level with the same institutions and diverge significantly over twenty years based on how quickly they adopt existing technologies. This isn't about inventing new technology. It's about implementation speed and the institutional framework that enables it.
Get the Full Details

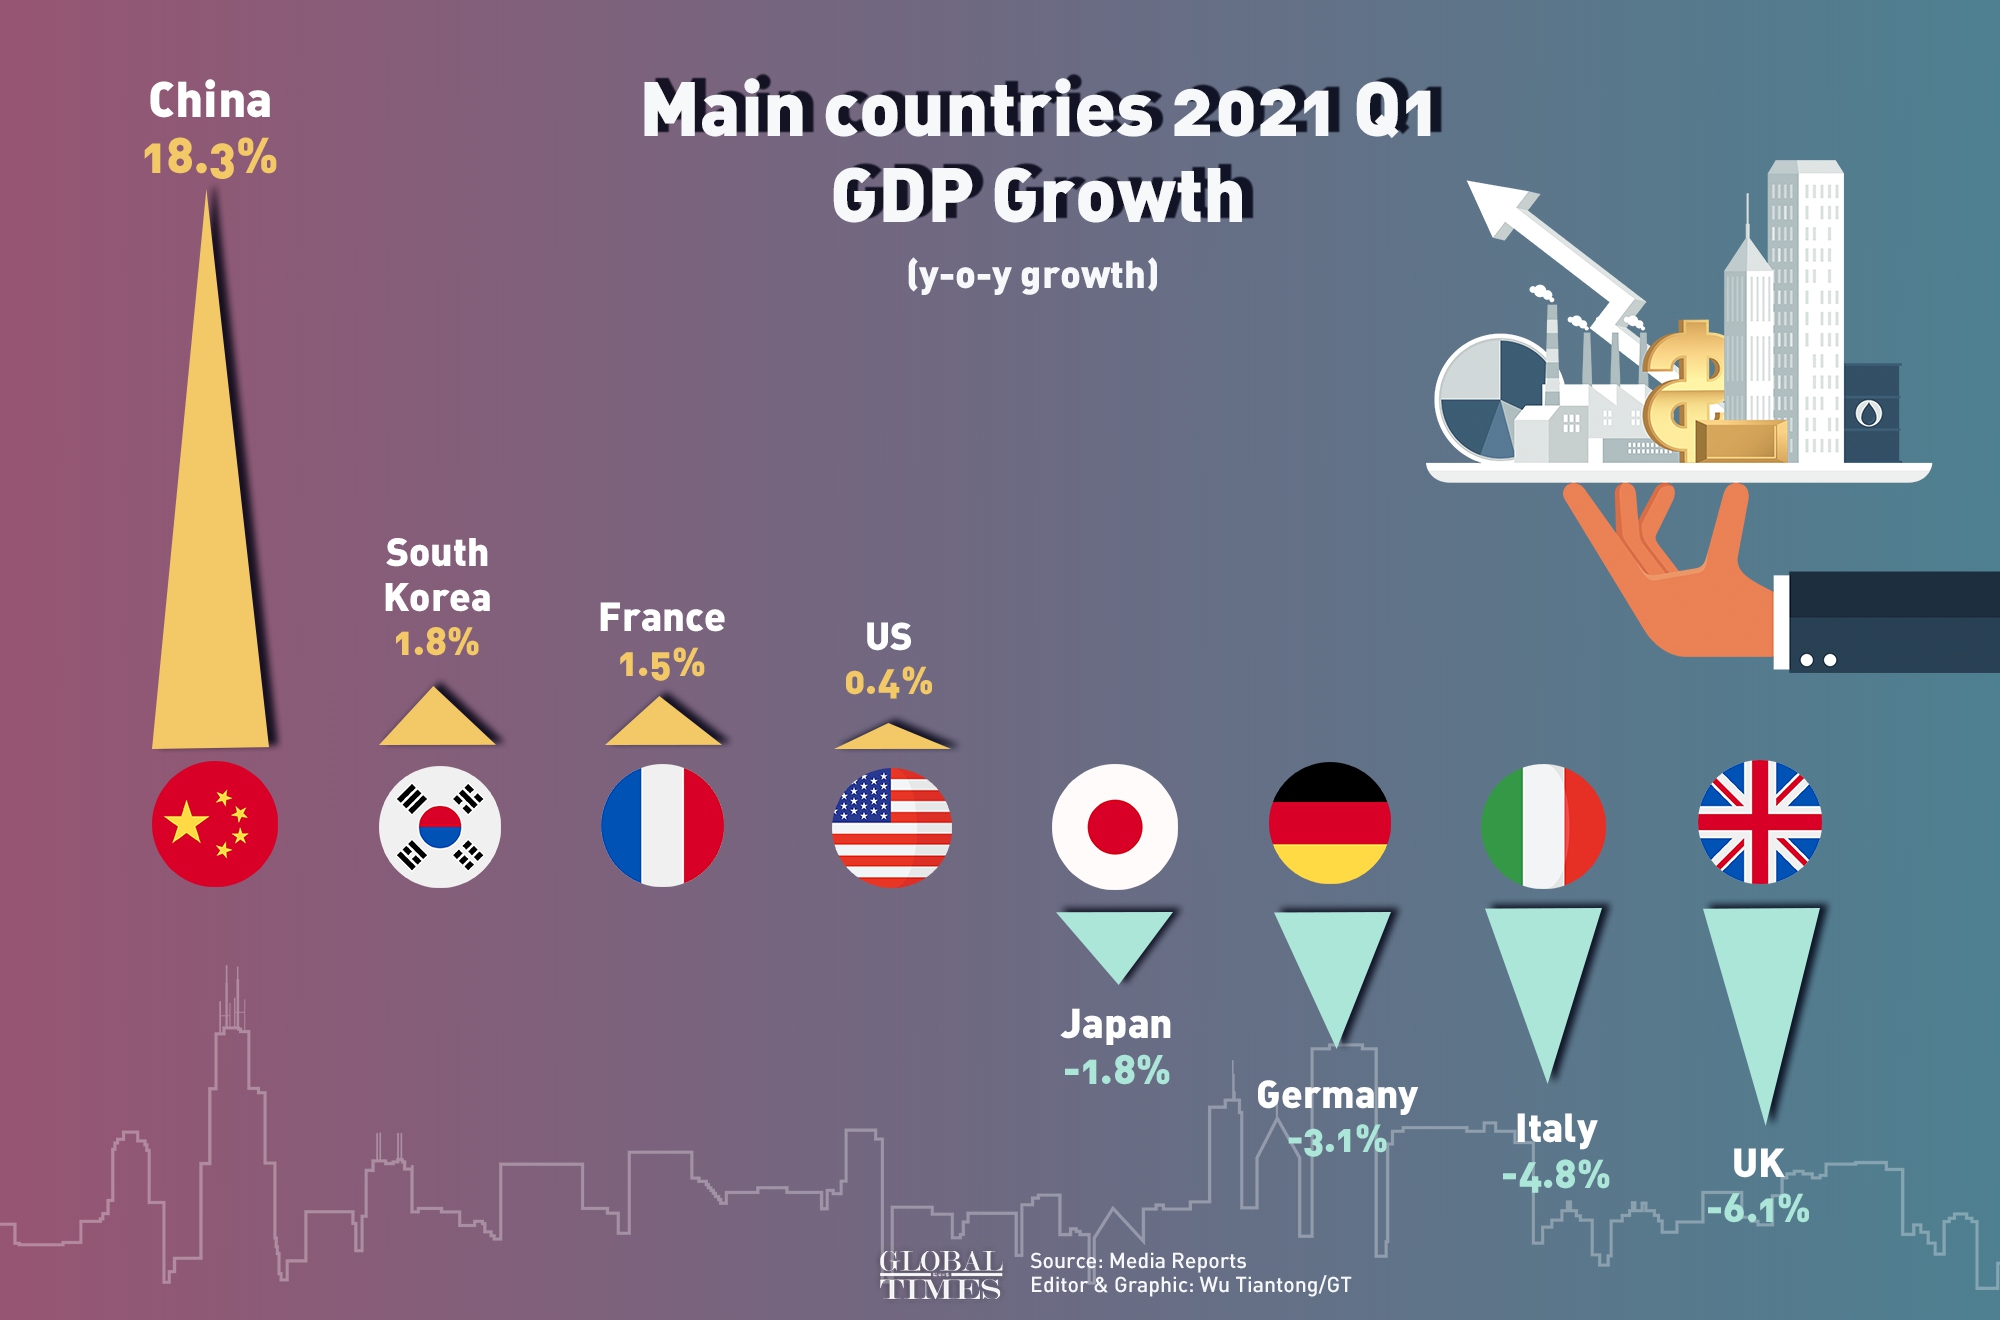
One counterintuitive insight: high-growth periods often come with declining growth rates over time, not accelerating ones. As economies get larger, each percentage point of growth represents an enormous absolute increase in output. The mathematics work against you. China's growth rate has slowed from double digits to around five percent, but five percent of a much larger economy still means more absolute growth than a ten percent rate on a smaller base. Another thing beginners miss: growth accounting decomposes growth into contributions from capital, labor, and total factor productivity (TFP). TFP is the residual. If you can't explain the growth with inputs, it shows up in TFP. TFP is supposed to capture technological progress, but it also captures measurement error, institutional improvements, and resource reallocation effects. When someone tells you TFP is zero growth, it doesn't mean nothing happened. It means you can't account for it with your data.
When Growth Doesn't Work the Way You Expect
Dutch disease is a real phenomenon. Countries that discover natural resources often see their currency appreciate, which makes other export sectors uncompetitive. The resource sector booms while manufacturing declines. Growth in GDP looks fine, but the economy becomes less diversified and more vulnerable to commodity price shocks. Resource curse is related but different. It's about governance and institutions deteriorating when resource wealth flows in. The growth rate might be positive, but the quality of institutions declines, which undermines future growth potential. I've seen this play out in multiple African economies over the past decade. The data looked strong during the commodity boom. Five years later, the same countries were struggling with recession and fiscal crises. Debt-fueled growth is another trap. Borrowing to finance consumption doesn't create growth. Borrowing to finance productive investment can, but only if the returns exceed the cost of debt. The problem is that political cycles encourage consumption spending because the benefits are immediate while the costs appear later. Most developing country debt distress cases follow this pattern.
There's also the issue of growth without development. GDP can rise while inequality worsens, environmental quality degrades, and social cohesion breaks down. The standard growth metrics don't capture any of this. I once reviewed a country's growth projections that looked excellent on paper. When we adjusted for environmental degradation and inequality, the net welfare gain was negative. The projections were technically correct but practically misleading.

What Actually Moves the Needle
Trade openness generally correlates with growth, but the relationship is conditional. Countries that integrate through export-oriented industrialization tend to grow faster than those that rely on import substitution. The East Asian tigers demonstrated this repeatedly. The evidence is mixed for commodity exporters, which makes sense given the volatility of prices and the Dutch disease effect. Institutional quality is probably the single most important factor. Property rights, contract enforcement, regulatory efficiency, and control of corruption all matter. But measuring institutions is hard. The Worldwide Governance Indicators aggregate many dimensions into composite scores that can obscure important distinctions. A country might score well on control of corruption but poorly on regulatory quality, which has very different implications for growth. Infrastructure investment has a clear growth impact when it addresses binding constraints. A country with terrible roads will grow faster per dollar of road investment than a country that already has decent roads. The marginal returns to infrastructure decline rapidly after a certain threshold. This is why the same infrastructure project can be transformative in one country and marginal in another.
Financial development matters, but only up to a point. Beyond a certain level of credit-to-GDP ratio, additional financial deepening shows diminishing or even negative returns to growth. The relationship is nonlinear. Some research suggests the threshold is around 100 to 120 percent of GDP, but this varies by country and depends on regulatory quality. Weak financial systems with poor regulation can amplify boom-bust cycles rather than smooth them.
Practical Measurement Issues
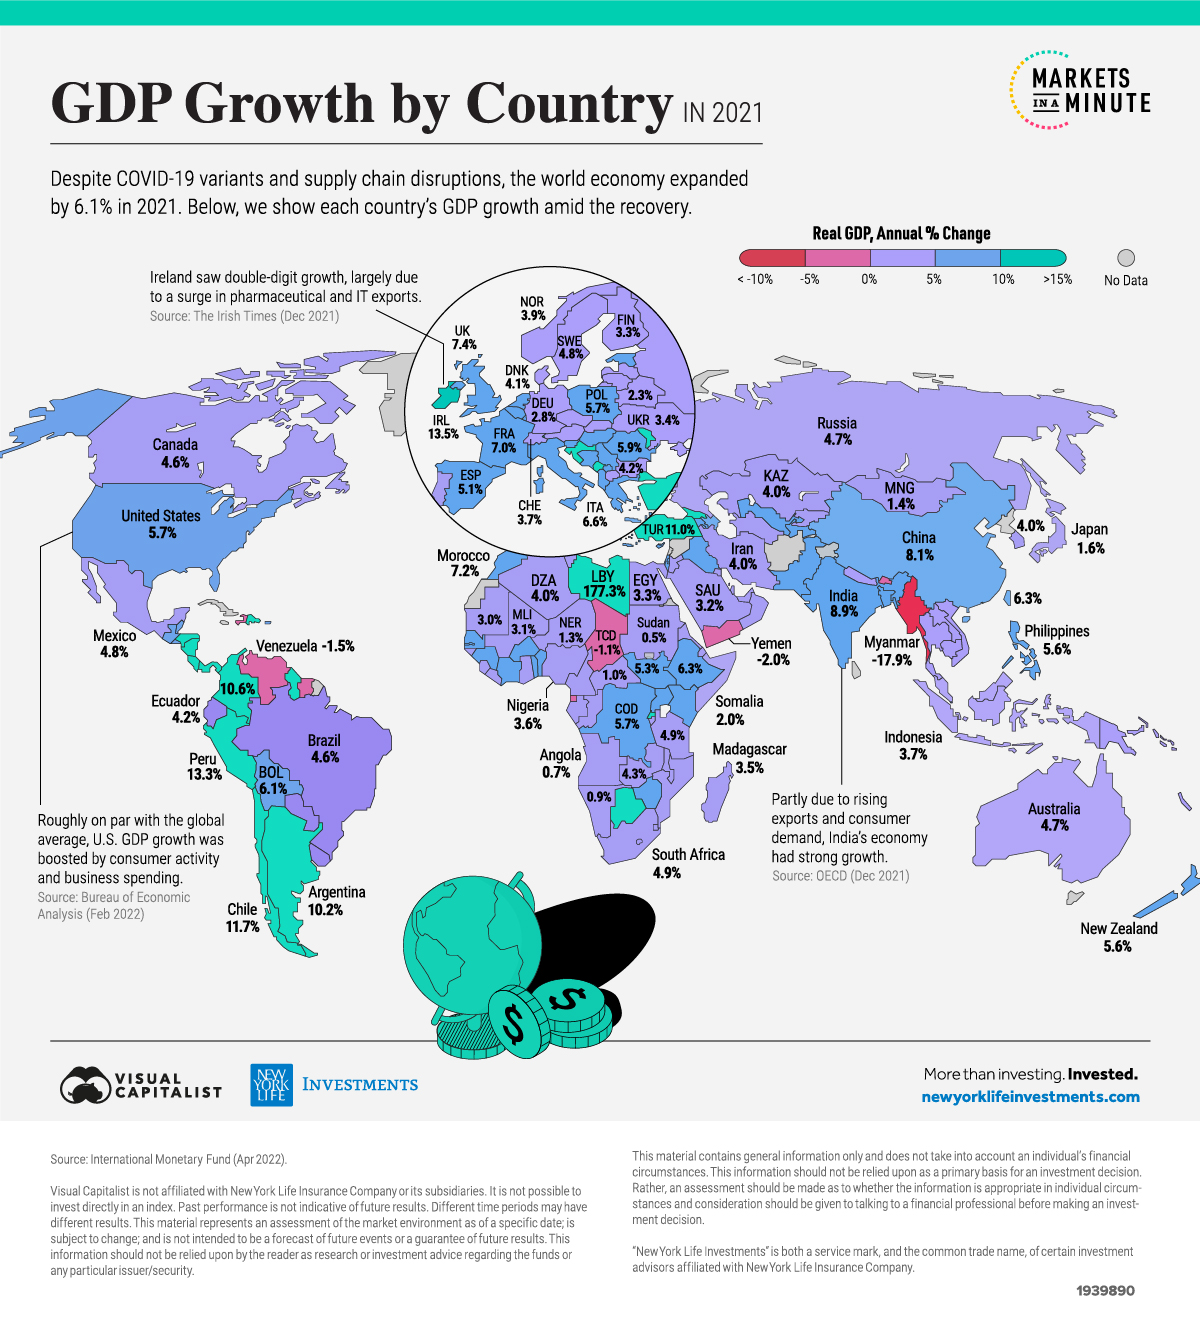
GDP measurement has limitations that most people don't understand. It doesn't capture unpaid work, underground activity, or environmental costs. Adjusted for these factors, some developing countries would show significantly lower growth rates. The World Bank has tried to create inclusive wealth measures that account for produced, human, and natural capital. The results are eye-opening but data-intensive. Exchange rate movements can distort cross-country growth comparisons. A country might grow at three percent in local currency but appear to grow at negative percent in dollar terms if its currency depreciates sharply. This happens frequently in emerging markets during global risk-off periods. The real economy might be fine, but the headline numbers look terrible. Purchasing power parity adjustments help but have their own problems. PPP exchange rates are based on price surveys that are conducted infrequently and cover limited baskets of goods. The Penn World Table updates periodically, but there are gaps and revisions that can change historical comparisons. If you're doing rigorous work, you need to understand the methodology behind the data, not just use the numbers at face value.

I learned this the hard way when advising a regional development bank. They wanted to compare growth rates across ten countries using IMF data. The comparison was flawed because different countries used different base years and seasonal adjustment methods. The apparent convergence in growth rates disappeared once we aligned the methodologies. This took about two weeks of work and completely changed their analysis.
Common Mistakes in Policy Design
Focusing on short-term stimulus without structural reform is a recurring error. Governments will pump money into the economy during downturns, which is fine for stabilization, but then fail to implement the reforms needed for long-term growth. The fiscal deficit becomes permanent, the structural bottlenecks remain, and the next downturn hits with less policy space. Another mistake is assuming that growth automatically leads to development. Infrastructure projects, industrial parks, and special economic zones sound good on paper but can fail if the underlying conditions aren't met. Local workforce skills, supplier networks, logistics chains, and market access all matter. Without these complementary factors, growth incentives become expensive failures. Copying successful models from other countries without adapting to local conditions is a third common error. The East Asian model works in contexts with particular institutional features, cultural norms, and geopolitical circumstances. Importing the policies without understanding the context usually produces disappointing results. I've seen this repeatedly in Latin America and Africa where governments adopted trade liberalization and deregulation without the institutional capacity to manage the transition.
What Actually Works
Sequencing matters. Countries that liberalize trade gradually, build institutions alongside growth, and manage financial opening carefully tend to perform better than those that move fast. The shock therapy approach has mixed results at best. The evidence from post-Soviet states shows that institutional collapse during rapid transition can wipe out decades of growth. Investment in human capital pays off with long lags. Education and health improvements from today won't show in growth data for ten to fifteen years. This time horizon is incompatible with political cycles, which is why governments underinvest in these areas despite the strong evidence. The ROI is high, but the timing is wrong for the people making the decisions. Industrial policy has a questionable reputation in mainstream economics, but selective, time-bound intervention can work when properly designed. The key is having clear performance benchmarks and exit strategies. When governments support industries indefinitely without accountability, the programs become rent-seeking vehicles. But when they're designed as temporary scaffolding with real conditions, they can help economies climb the value chain.
Regional integration can boost growth by expanding market size and enabling specialization. The European Union is the most advanced example, but Mercosur, ASEAN, and the African Continental Free Trade Area are all working toward similar goals. The evidence suggests that regional trade agreements boost trade volumes by roughly thirty percent on average, though the growth impact depends on how much trade they divert from outside partners.
When Standard Models Break Down
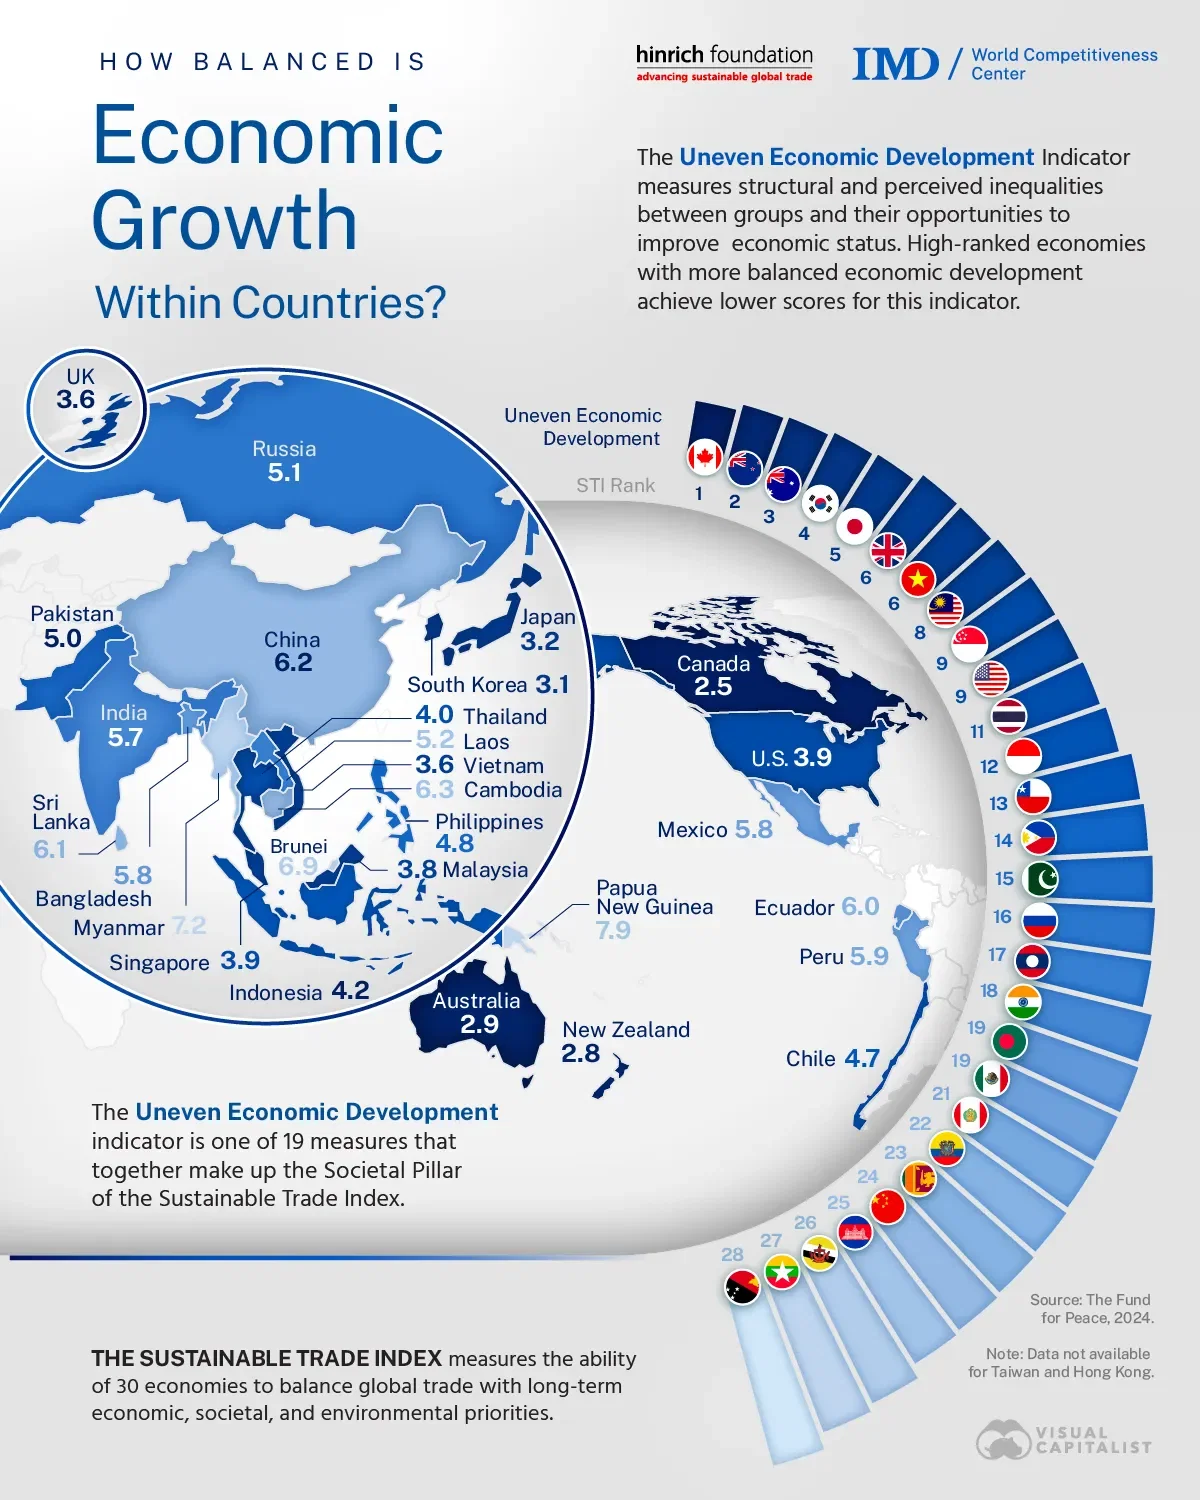
Small island developing states face growth constraints that standard models don't capture. Limited land area, isolation from major markets, vulnerability to climate change, and dependence on a few sectors create a different set of challenges. The standard growth models assume factors can move freely within an economy and that markets are large enough to support specialization. Islands violate both assumptions. Landlocked countries face higher trade costs, which act as a tax on exports and a subsidy on imports. Being landlocked increases trade costs by roughly twenty percent according to World Bank estimates. This doesn't make growth impossible, but it requires compensating investments in transportation infrastructure and trade facilitation that landlocked countries often can't afford. Conflict-affected countries present another challenge. Growth in these contexts is often violent and unsustainable. I worked on a assessment in a country where GDP grew at eight percent annually for three years. The growth came from reconstruction spending after a civil war ended. When the spending tapered off, growth collapsed. The data showed progress, but the underlying economy was still fragile.
Climate change is increasingly a growth constraint. Countries that depend on agriculture face rising risks from changing precipitation patterns and temperature increases. The economic losses from climate impacts are already showing up in growth data for some tropical economies. Projections suggest these losses will increase unless adaptation investments keep pace, which most affected countries can't afford without international support. The intersection of demographics and growth deserves more attention. Aging populations in developed economies constrain growth through shrinking labor forces and rising dependency ratios. Meanwhile, some developing countries have demographic dividends coming, with large young populations that could accelerate growth if properly educated and employed. The difference in outcomes between these two groups will likely widen in the coming decades.
Bottom Line
Economic growth isn't a simple equation. It's the result of interacting factors operating at different speeds and with different time horizons. The data can be misleading if you don't understand how it's constructed. The models are useful but limited. The policies that work in one context often fail in another. What works is honest assessment of your starting conditions, realistic sequencing of reforms, and patience with the time lags involved. Growth doesn't happen when you declare it. It happens when you build the capacity for sustained expansion. That's harder than it sounds and takes longer than politicians want to admit.
