The Real Numbers Behind Legal Cannabis Markets
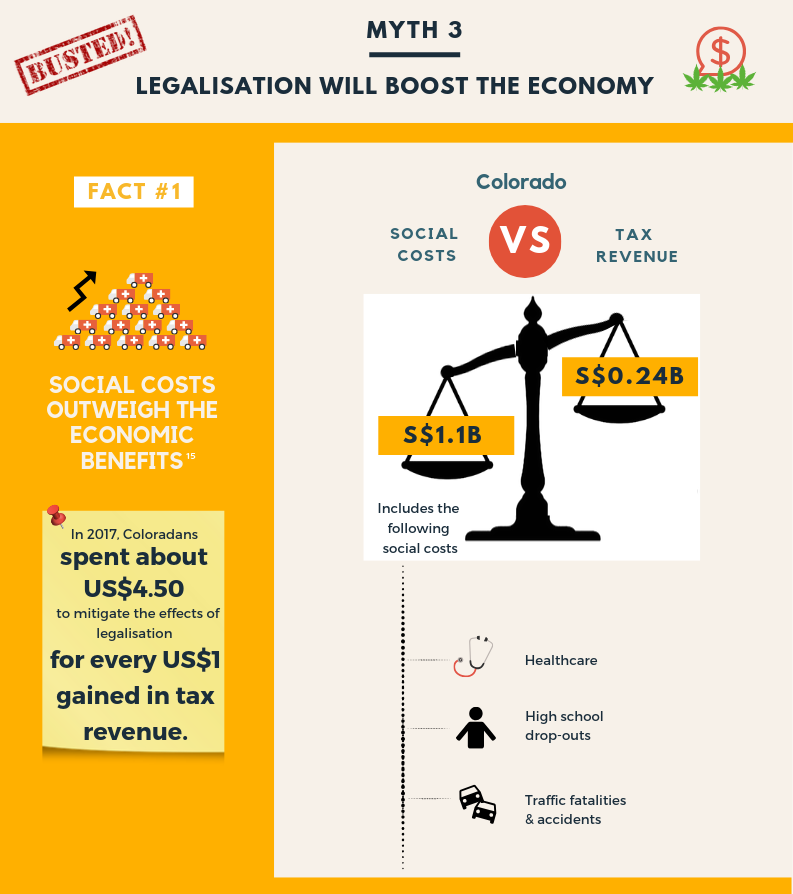
The first thing anyone needs to understand about the Economic Impact Of Legalizing Weed is that the revenue projections from industry trade groups are almost always inflated. The numbers are calculated before a single plant is harvested. What actually happens is usually different and less dramatic than the glossy reports predict. Tax revenue is the headline metric that gets cited, and it's real, but it's not infinite. Colorado, which legalized in 2014, collected roughly $165 million in total cannabis taxes in its most recent full year. That sounds substantial until you account for the costs of regulation. The state spends millions annually on licensing, inspection, compliance enforcement, and administrative oversight. After those deductions, the net fiscal contribution is materially smaller than raw tax receipts suggest. The retail price decline in mature markets is another factor people don't talk about enough. In Colorado, the average price per ounce of flower dropped from roughly $1,100 at legalization to around $700 within the first three years. That deflation directly compresses tax revenue over time because most states tax cannabis by weight or retail price, not by profit margin. Operators absorb margins. Tax receipts shrink. States either raise tax rates to compensate or accept lower revenue than originally projected.
This is a structural issue that repeats in nearly every mature market. Washington State saw a similar price erosion pattern. New Jersey, still in its earlier phases, has already warned legislators that initial revenue forecasts may need adjustment downward as competition intensifies.
Banking Access and Cash Operations
The biggest operational headache in cannabis isn't farming or retail. It's banking. Federal prohibition under the Controlled Substances Act means most traditional banks won't touch cannabis money. The Safer Banking Act has passed the House but hasn't been enacted into law as of my last update. Until then, operators function as cash businesses in a system that wasn't designed for them. I worked with a dispensary operator in Colorado who couldn't get a standard merchant account. Payment processors classified cannabis as high-risk and charged transaction fees of 8 to 12 percent, compared to the 2 to 3 percent typical for other retail. For a store doing $2 million in monthly revenue, that's an extra $120,000 to $180,000 per month in processing costs that doesn't exist in any other legal retail sector. The workaround was straightforward but expensive. They moved to a specialized cannabis-friendly payment processor that offered debit-style card transactions with lower surcharges, bringing their fees down to around 4 percent. Still far above mainstream retail rates, but significant savings at scale. This cost differential is rarely factored into economic impact analyses. The federal banking restriction effectively acts as a hidden tax on the entire industry.
Get the Full Details
Municipal Opt-Outs and Regulatory Fragmentation
State-level legalization doesn't guarantee local access. Many states allow cities and counties to ban dispensaries entirely through zoning ordinances. This creates uneven markets where demand concentrates in permit-friendly areas while neighboring jurisdictions see no legal supply and retain active illicit markets. Tennessee legalized medical cannabis but allowed municipalities to opt out, resulting in fewer than two dozen licensed facilities across the entire state despite a population of over seven million. The economic consequence is measurable. Markets with fragmented access show lower tax collection, higher enforcement costs, and persistently elevated black market activity. A study of California's regulatory landscape found that counties allowing dispensary operations had 40 percent lower violent crime rates associated with drug transactions compared to counties that banned them, while generating consistent local tax revenue that supporting schools and emergency services.
What the Literature Actually Shows
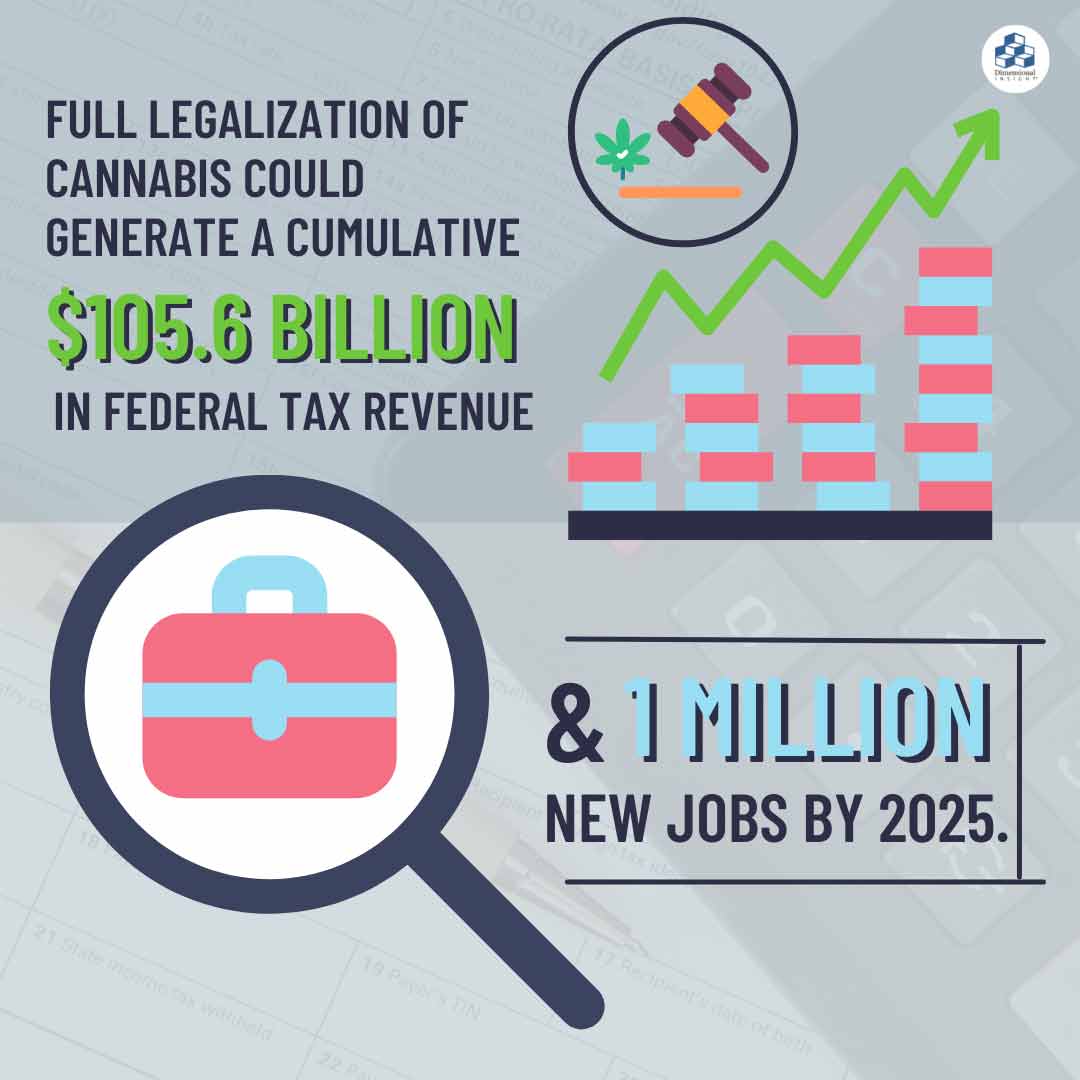
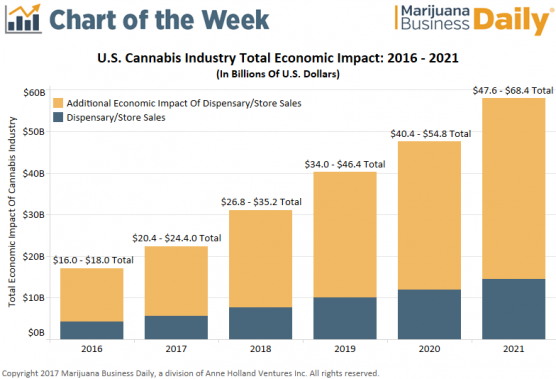
Research on the broader economic impact of legal cannabis has become more rigorous in recent years. The National Bureau of Economic Research published a paper in 2021 analyzing traffic fatalities and found no statistically significant increase in fatal car accidents following recreational legalization. This contradicted early warnings from anti-legalization groups that road safety would deteriorate sharply. Employment effects are more ambiguous. Colorado added an estimated 10,000 to 15,000 direct cannabis jobs in the first five years of legalization. Most of these are low-wage positions with limited benefits. The indirect job creation—security, consulting, equipment suppliers, marketing—is harder to measure and likely smaller than industry projections suggest. A University of Denver analysis placed the total economic output of Colorado's cannabis industry at approximately $4 billion annually at peak, which is significant for a single state but represents a tiny fraction of the state's overall economy. Public health spending is another category that gets overlooked. Colorado reported a modest but measurable increase in emergency department visits related to cannabis in the years following legalization, particularly among adolescents. The cost burden on the healthcare system is small relative to tobacco-related expenses but not zero. Any serious economic impact analysis should include this line item, and most don't.
A Practical Framework for Estimating Impact
If you're evaluating the economic impact of legalizing cannabis for a specific jurisdiction, here's the approach I use rather than relying on industry-funded studies. Start with population data and estimate addressable market size. A common rule of thumb is that adult cannabis consumers represent roughly 8 to 12 percent of the adult population in a given area. Multiply that by average annual spending per user, which in mature markets ranges from $500 to $1,200 depending on price levels. Then apply a realistic tax rate. Most states land between 10 and 25 percent when you combine excise, sales, and specialty taxes. Subtract regulatory costs, which typically run 15 to 30 percent of gross tax revenue in the early years as infrastructure builds. What remains is your best estimate of net fiscal impact. It's usually less optimistic than the projections you'll see from lobbyists, and more accurate than the doom scenarios from prohibition advocates. The market also matures differently than early predictions assumed. Within five to seven years of legalization, most mature markets see consolidation. Smaller operators exit, prices stabilize or decline, and tax revenue plateaus. Colorado's tax receipts peaked around 2019 and have trended sideways since. Revenue growth in the first three years is exciting. Sustained growth beyond that point is uncommon unless a state continuously raises tax rates, which then accelerates the shift back to illicit markets.

There's no single clean answer to the economic impact question. The numbers are real, the trade-offs are measurable, and the political incentives on both sides make honest analysis difficult. But the data that exists is clearer than either side wants to admit.