How to Assess Flood Risk Without Being Misled by Outdated Maps
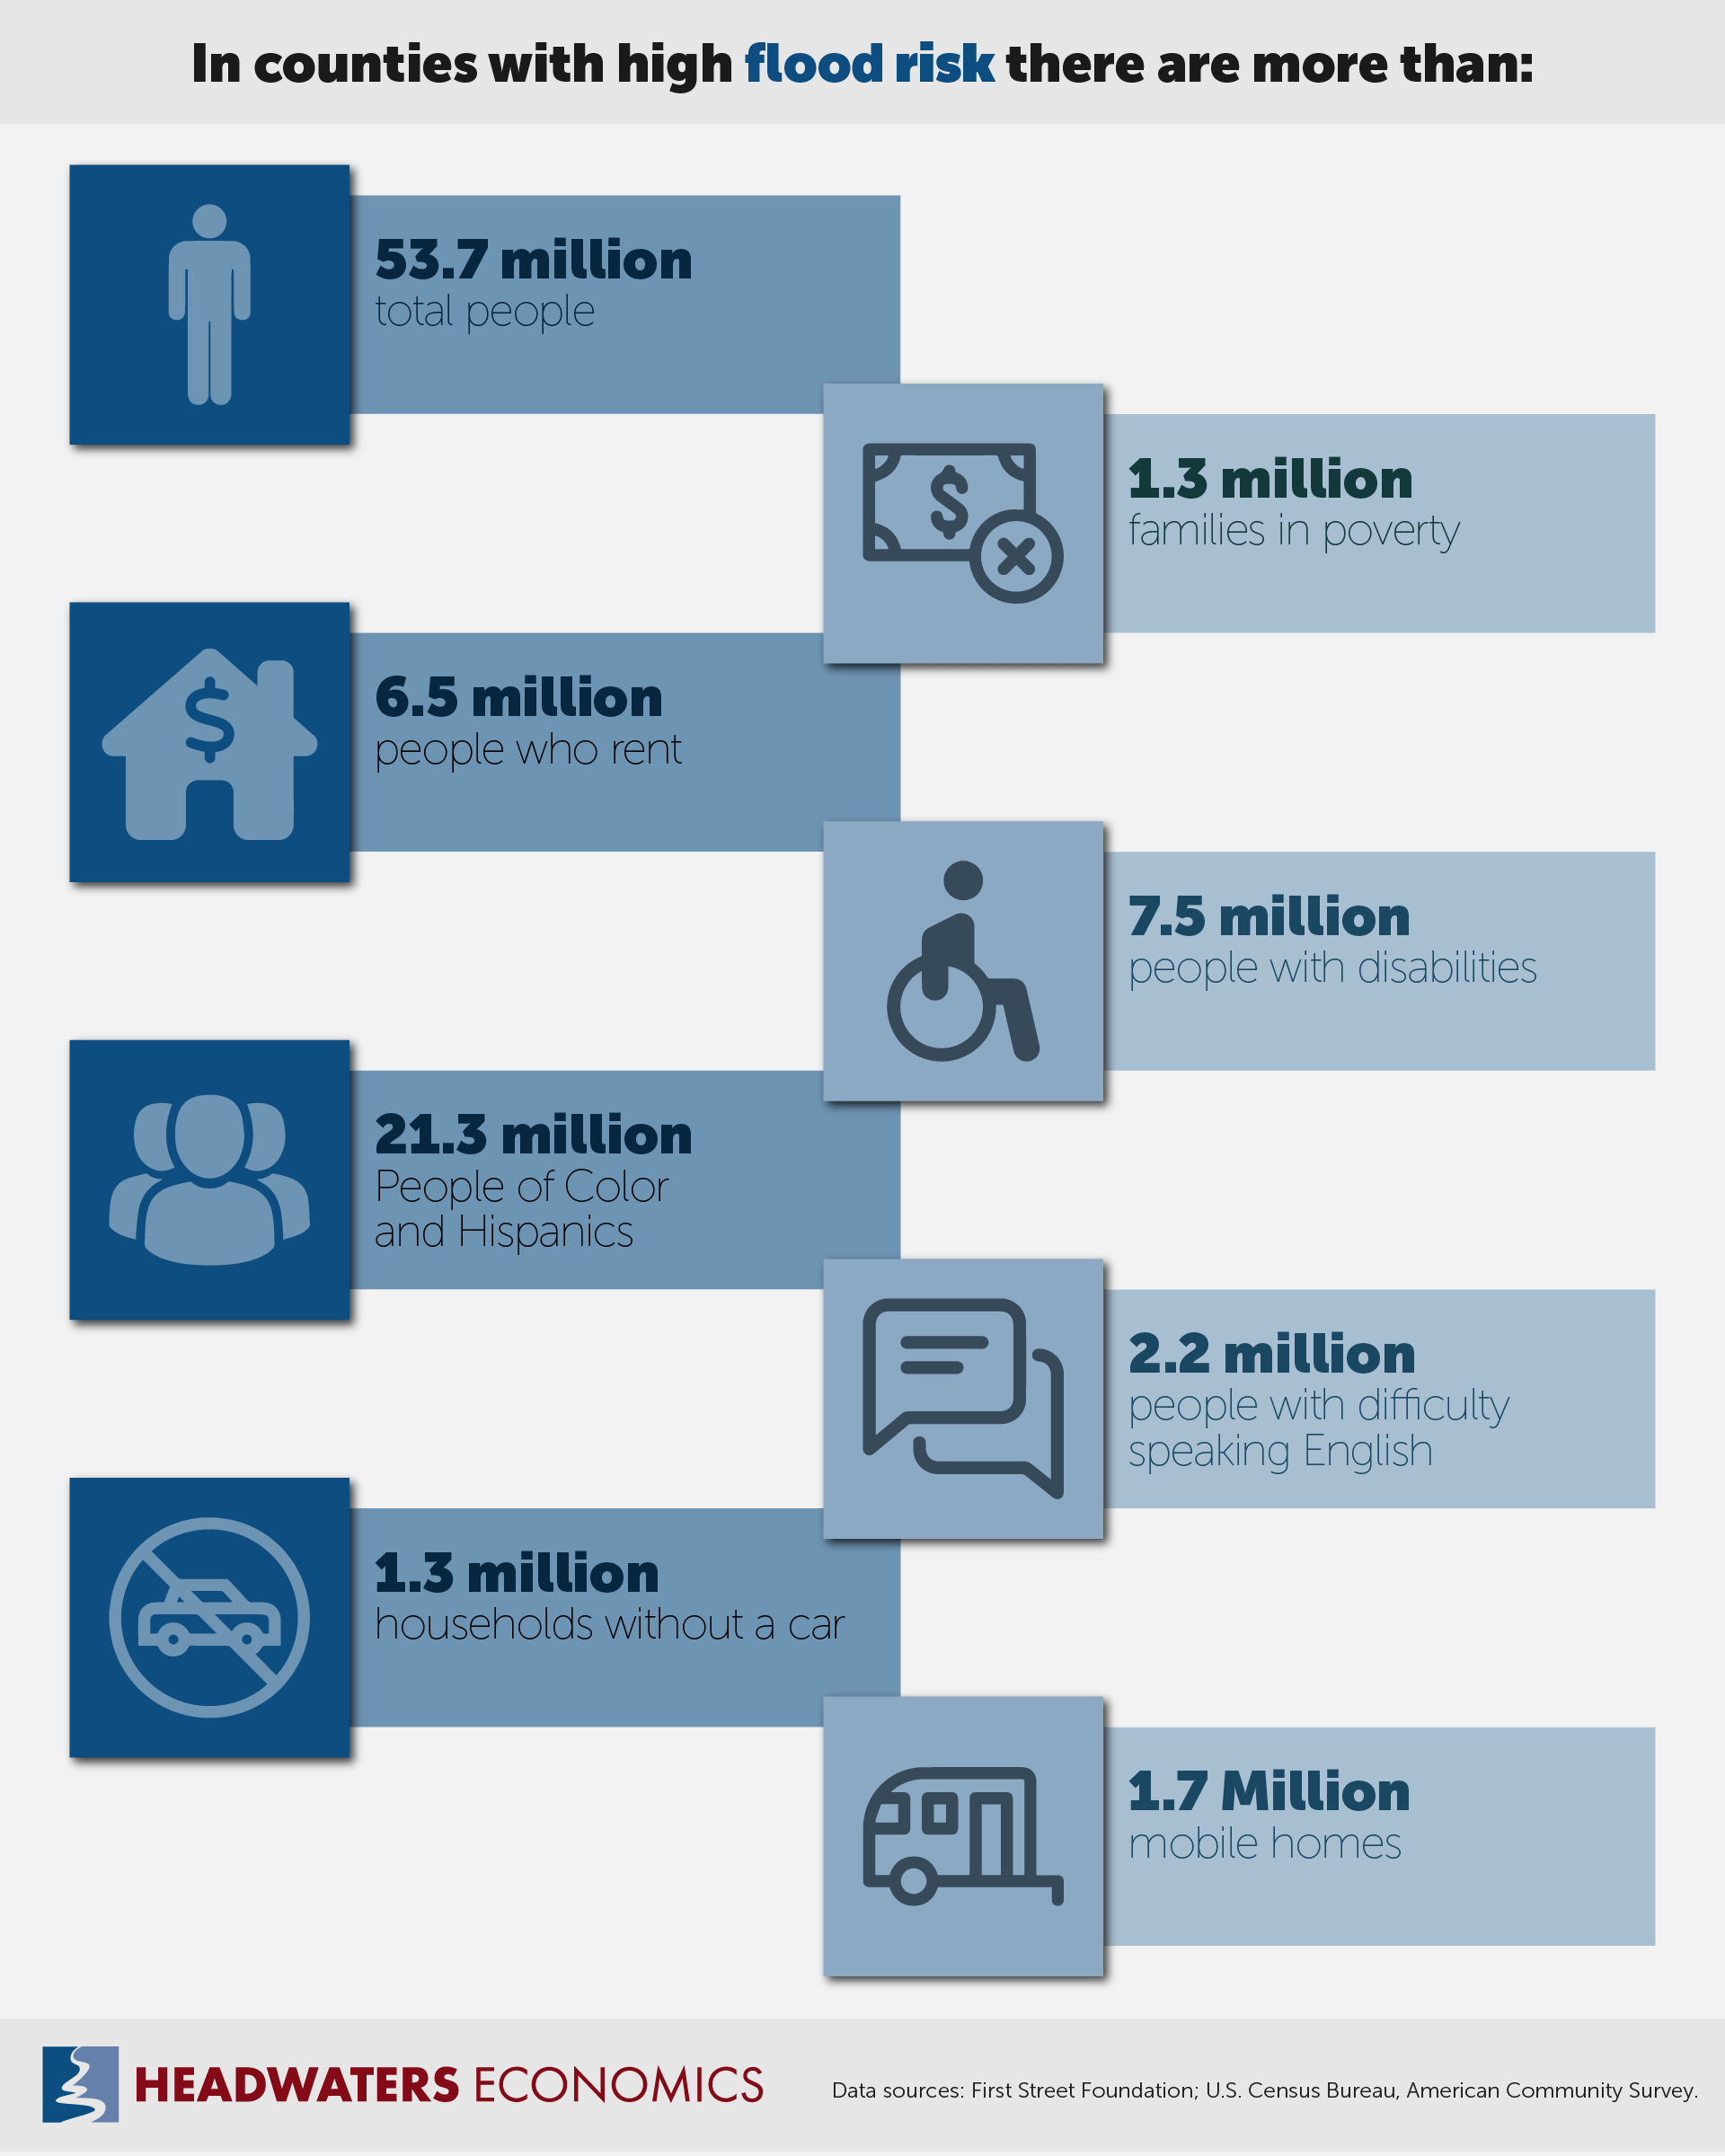
Flood risk assessment isn't a single calculation. It's a stack of assumptions layered on top of each other, and most of them are wrong in predictable ways. I've spent enough years looking at flood damage reports and insurance adjuster documents to know that the numbers on paper rarely match what actually happens when water moves through a watershed. Here's how to do it in a way that doesn't waste your time or get you sued. When people talk about the Economic Impacts Of Flooding, they're usually referring to a narrow set of metrics—property damage, repair costs, business interruption, insurance payouts. That's incomplete. The real picture includes things that don't show up on any spreadsheet until years later. A manufacturing plant gets flooded, the owner files an insurance claim, gets paid 78 percent of what they expected, and then closes six months later because their supply chain partners can't deliver replacement parts. That closure affects three restaurants within a mile, two auto shops, and the local school district's property tax base. None of that is in the original flood model. It shows up in county revenue reports from two fiscal years later. The most useful metric I've found is the cost-per-square-foot-of-insurable-loss ratio. Most assessments stop at gross replacement cost. That's a trap. Net replacement cost after deductibles, depreciation, and coverage limits is the number that actually matters for financial planning. I calculate it this way: take the insured value, subtract the average deductible percentage for that zone (usually 1 to 5 percent depending on policy type), apply the actual cash value depreciation factor based on asset age, then cross-reference with regional construction cost indices from RSMeans or similar databases. It takes about twenty minutes per property if you have clean data. An hour if you're pulling from municipal records that haven't been digitized.
Where Most Assessments Break Down
FEMA flood zones are based on historical data, and that's the first problem. The 100-year floodplain was mapped using rainfall and river gauge data from roughly 1950 through 1990. Climate patterns have shifted since then. The 2-percent-annual-chance flood event in many midwestern counties now has a probability that's 15 to 30 percent higher than what the maps show. You need to apply a climate-adjustment factor. I use a 1.25 multiplier on depth values for areas within 500 meters of a major river basin, and a 1.15 multiplier for coastal pluvial flood zones. It's not perfect. It's better than using unadjusted FEMA data, which will systematically underestimate your exposure by 20 to 40 percent in most regions. Here's a specific problem I ran into last year. A client in Illinois wanted me to assess flood risk for a proposed warehouse development near the Kankakee River. The FEMA map showed the site in Zone X—minimal flood hazard. Standard procedure would have been to give them a clean bill of health and move on. But the 2018 and 2019 flood events had already reshaped the local hydrology. I pulled USGS stream gauge data from the nearest station, ran a HEC-RAS model using the post-2018 channel geometry, and found that what FEMA called Zone X was actually a shallow-sheet-flow zone that hadn't been properly classified after sediment deposition changed the overland flow paths. The actual flood risk at that site was equivalent to a 500-year event, not a 10-year event. My workaround was to get a letter of map revision from FEMA based on the new data, which required a full engineering study. The process took about eleven weeks and cost roughly $18,000. Cheaper than being wrong.
Business Interruption: The Hidden Multiplier
Property damage gets all the attention in flood impact studies. Business interruption is where the real economic damage hides. A 2021 study by the National Bureau of Economic Research found that business interruption costs from flooding average 1.8 to 2.4 times the direct property damage in small and medium enterprises. For large facilities, the ratio drops to about 1.2 to 1.5 because bigger companies have redundancy. But small businesses don't. When a restaurant floods, the damage to kitchen equipment might be $80,000. The lost revenue during the six-week closure, plus lost customers who find other places and never come back, could be $200,000. Most standard flood impact assessments don't model this at all. To capture business interruption properly, you need industry-specific downtime curves. Food service averages 45 to 90 days to full recovery from moderate flooding. Retail is faster—21 to 45 days. Manufacturing varies wildly depending on how specialized the equipment is. I build these into my models using historical claims data from Insurance Services Office reports and cross-reference with Small Business Administration recovery statistics. The formula is straightforward: estimated daily revenue multiplied by average recovery time multiplied by customer attrition factor (typically 0.15 to 0.30, meaning 15 to 30 percent of customers don't return). This part alone can add 60 to 120 percent to your total economic impact estimate.
Get the Full Details
Infrastructure Cascading Failures
This is the part most people miss, and it's the part that turns a bad flood into an economic catastrophe. Flood damage to one piece of infrastructure doesn't stay contained. It cascades. A flooded transformer substation takes out power for a commercial district. That forces grocery stores to close. Closed grocery stores mean delivery trucks stop coming. Trucks not coming means restaurants run out of ingredients. Restaurants closing means employees lose income. Employees losing income means the retail strip next door loses customers too. This cascade effect typically extends the economic damage by 2 to 4 kilometers from the original flood zone and adds another 30 to 60 percent to total losses. I track these cascades using a node-and-link model. Each critical infrastructure asset—power substation, water treatment plant, major road intersection, telecommunications hub—becomes a node. The roads and power lines connecting them are the links. When a node goes down, I simulate the failure propagation through the network using graph theory algorithms. The computation is fast once the model is built. The hard part is getting accurate infrastructure data. Municipal GIS databases are usually incomplete or years out of date. I've learned to verify critical nodes against utility company maps and state transportation department records before trusting any automated dataset. This verification step adds about two hours to a standard assessment but prevents the kind of gross errors that come from assuming a backup road exists when it's actually been decommissioned.
Insurance Market Dynamics
After a significant flood event, insurance markets don't just adjust premiums. They retreat. In high-frequency flood zones, primary carriers pull out entirely. Coverage shifts to state-backed flood insurance programs or excess-and-surplus markets. Premiums in those markets can be 3 to 8 times higher than standard policies, and deductibles can reach 5 to 10 percent of the insured value. This creates a feedback loop: higher costs drive property values down, lower property values reduce the tax base, smaller tax bases mean less investment in flood mitigation infrastructure, weaker infrastructure means more damage next time, and more damage means the insurance market retreats further. Accounting for this in economic impact models requires looking at insurance availability, not just premium costs. I include an insurance accessibility score in my assessments—rated on a scale of 1 to 5 based on the number of available carriers, average policy terms, and historical premium escalation rates in the area. Areas scoring 2 or below get flagged as insurance-migration risk zones, and I adjust the long-term economic impact projections upward by 15 to 25 percent to account for the compounding effect of reduced coverage over a 10 to 20 year horizon. This isn't standard practice in most flood risk assessments, but it's one of the most important factors for understanding long-term economic resilience.
Reconstruction Cost Volatility
Post-flood construction costs don't stay flat. They spike. When a major flood hits a region, demand for contractors, materials, and equipment surges locally while the supply base stays the same. I've seen reconstruction cost indices jump 22 to 40 percent within six months of a significant flood event in a given market. This means that the cost to rebuild after the second flood in the same area is almost always higher than the cost to rebuild after the first, even if the second flood is smaller. The economic impact assessment needs to account for this escalation curve. I model it as a geometric progression. First flood reconstruction at baseline cost. Second flood in the same area at 1.25 to 1.40 times baseline. Third flood at 1.55 to 1.85 times baseline. The exact multiplier depends on regional labor market conditions and material supply chain proximity to manufacturing centers. This is counter-intuitive to most people who assume flood damage scales linearly with water depth and area. It doesn't. It scales with the existing damage history of the region.
Property Value Depreciation Patterns
Flooded properties don't just lose value equal to the damage amount. They lose additional value from stigma. A property that has been flooded once sells for 5 to 15 percent less than a comparable non-flooded property, even after full restoration. Two flood events compound this—each event adds another 3 to 8 percent in stigma depreciation. By the third event, the stigma effect can exceed the physical damage effect in terms of total value loss. This is especially pronounced in residential markets where buyer perception matters more than objective risk data. I calculate this using a hedonic pricing model adjusted for flood history. The formula weights physical damage at 0.85 and stigma depreciation at 0.15 for the first event, then shifts to 0.70 and 0.30 for subsequent events. The physical damage component comes from your reconstruction cost estimate. The stigma component is region-specific—I've found that stigma effects are roughly twice as strong in Sun Belt markets compared to Midwest markets, likely because flooding is less expected and therefore more psychologically impactful to buyers. Applying the wrong regional multiplier here can swing your property value estimate by 4 to 8 percent.
A Note on What This Doesn't Cover Well
These methods work well for commercial and industrial properties with clear financial records. They break down for informal economies, subsistence agriculture, and rural communities where economic activity isn't captured in standard business databases. In those contexts, flood impact estimates tend to understate real losses by 30 to 60 percent because the damage to social capital, subsistence food production, and informal labor markets doesn't show up in any quantitative model. If you're working in a rural or developing region context, supplement your analysis with qualitative field surveys and community-level economic activity assessments. The numbers will still be incomplete, but they'll be closer to reality. The biggest limitation across all of these methods is data quality. Every model I've described depends on accurate, current input data—stream gauges, property records, infrastructure maps, insurance claim histories, construction cost indices. If your data is stale or incomplete, the model output will be precise-looking but wrong. I always recommend spending 30 percent of your project time on data validation before running any analysis. Garbage in, garbage out applies especially hard to flood economics.


