Understanding Economic Obsolescence in Property Valuation
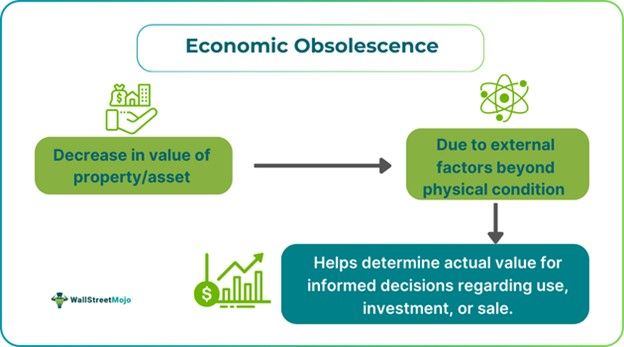
Economic obsolescence is one of those concepts that sounds straightforward until you actually have to quantify it during an appraisal. It is economic obsolescence is a type of depreciation that results from external forces beyond the property owner's control. The building itself might be fine. The roof could be new. The HVAC replaced last year. But the value takes a hit anyway because something changed in the surrounding environment or market. The triggers are almost always external. A new highway interchange gets built two blocks away and noise levels make the property nearly unusable for its intended purpose. A major employer closes down in town and the whole commercial district slides. Zoning changes restrict what you can do with a parcel. Environmental contamination shows up on a neighboring site and nobody wants to lease adjacent space anymore. These are not problems you can fix by renovating. That is the whole point of this category of depreciation. In practice, there are two flavors to deal with. Curable economic obsolescence exists when a cost-effective remedy is available, even if the remedy is not something the property owner would normally pay for. An example would be a government program to remediate nearby contamination. Uncurable economic obsolescence is the far more common and frustrating situation, where the external factor is permanent and there is no realistic path to reversal.
How to Quantify It in an Appraisal
Most appraisers reach for either the paired sales technique or the yield capitalization method. Paired sales involves finding two similar properties that differ only because one is subject to the external factor and one is not. The difference in sale price gets attributed to the obsolescence. This sounds clean on paper. In reality, finding clean comparables is nearly impossible because markets rarely present perfect pairs. The yield capitalization approach is usually more practical. You estimate the annual income loss caused by the external factor and capitalize it back to a present value. Say a warehouse near a new landfill loses twenty thousand dollars per year in rental income because tenants will not locate there anymore. Capitalizing that at a ten percent rate gives you a depreciation figure of two hundred thousand dollars. Simple enough in theory. The hard part is justifying the income loss number and picking the right capitalization rate. I once worked on a light industrial property where a nearby manufacturing plant had received permit variances allowing them to run overtime shifts. Nighttime noise and truck traffic dropped the occupancy of our subject property from ninety-five percent down to about sixty percent over a three year period. The paired sales approach kept giving me garbage because every comparable sale was somehow affected by different external conditions. What actually worked was analyzing lease rates in the submarket and comparing them to a clean benchmark area. The rent differential was roughly eight dollars per square foot annually. Applied across the building and capitalized at nine percent, that came to about three hundred and forty thousand in economic obsolescence. It was tedious and required three weeks of lease abstraction work, but it held up under review.
Common Mistakes That Cost Appraisers Trouble
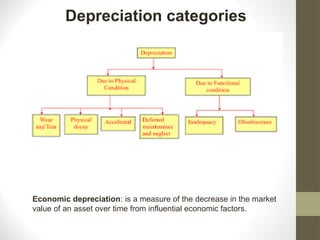
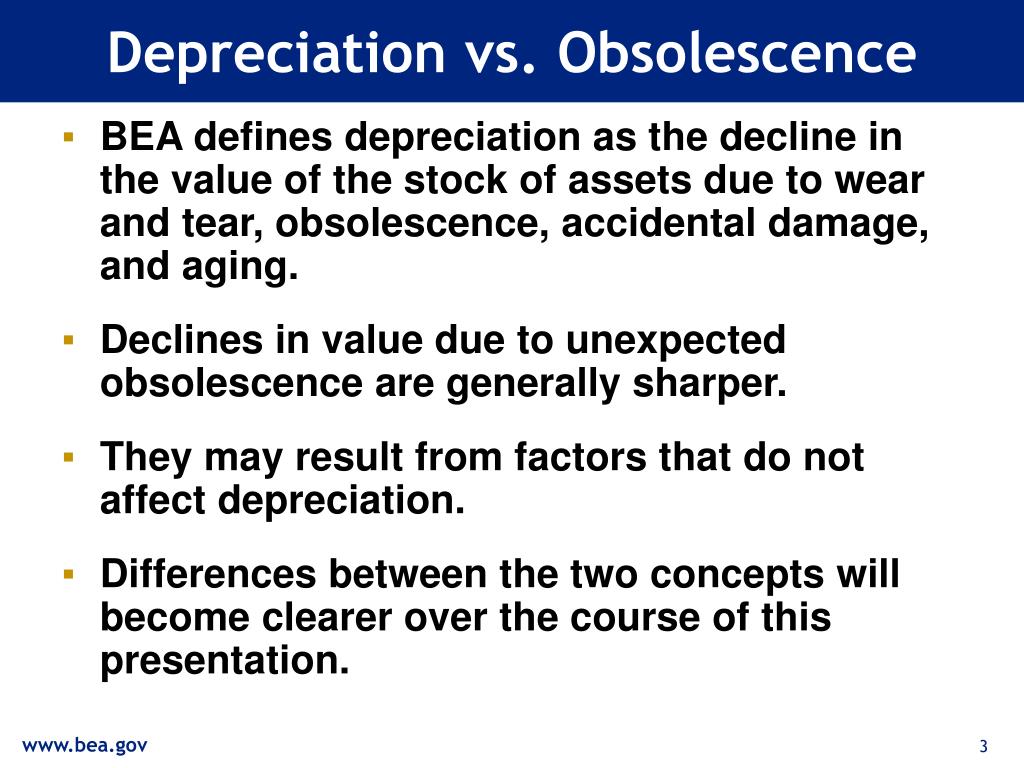
The biggest pitfall I see is conflating physical deterioration or functional obsolescence with economic obsolescence. A roof that leaks because it is thirty years old is physical depreciation. A floor plan that cannot accommodate modern equipment is functional obsolescence. Economic obsolescence has nothing to do with the condition or design of the improvements. It is purely about the external environment. Mixing these categories up will distort your valuation and invite criticism from anyone who actually reads the report. Another mistake is double counting. If you have already adjusted comparable sales for the external factor, you should not also apply a separate economic obsolescence deduction in the cost approach. That charges the buyer twice for the same problem. I have seen reports do exactly this, usually because the appraiser was working from two different data sets without checking for overlap. There is also a tendency to treat all external factors as permanent when some are actually temporary. A new competitor opening across the street might tank occupancy for eighteen months, then get acquired or go under. If you apply a permanent obsolescence adjustment to a transient problem, your value estimate will be too low. I learned this the hard way on a retail appraisal where a big-box store next door was undergoing a temporary closure for renovation. Occupancy dropped, rents slipped, and my initial instinct was to mark it down hard. After tracking the lease terms and renovation timeline, I concluded the dip would recover within a year and reduced the obsolescence adjustment accordingly. The final opinion of value ended up roughly one hundred and fifty thousand dollars higher than my first pass.
Get the Full Details
When the Method Breaks Down
Economic obsolescence measurement is not a precise science. It is judgment-heavy and heavily dependent on whatever market data you can dig up. In thin markets with few transactions, paired sales analysis becomes essentially useless. In emerging neighborhoods where external conditions are changing rapidly, historical data may not predict future losses accurately. And in cases of severe stigmatization, like a property near a known contamination site, the income loss may be so catastrophic that the remaining value approaches zero regardless of how carefully you build your model. If you are dealing with a highly specialized property in a declining industry, such as a coal processing facility after the plant closes, the economic obsolescence is likely total and uncurable. No amount of income modeling will save that valuation. In those situations, the most honest answer is often to note the obsolescence qualitatively and rely on whatever market-derived evidence exists, even if it is sparse. The cost approach is also the primary vehicle for capturing economic obsolescence, which means it only works well when you have a reliable replacement cost figure to start from. If the improvements are highly customized or outdated, your cost estimates will carry their own errors, and layering obsolescence on top amplifies them. In those cases, the sales comparison approach may actually be more reliable despite its own limitations, because it captures the market's aggregate judgment of all factors including economic obsolescence in a single number.