How To Identify Industries With Sustainable Economic Profits
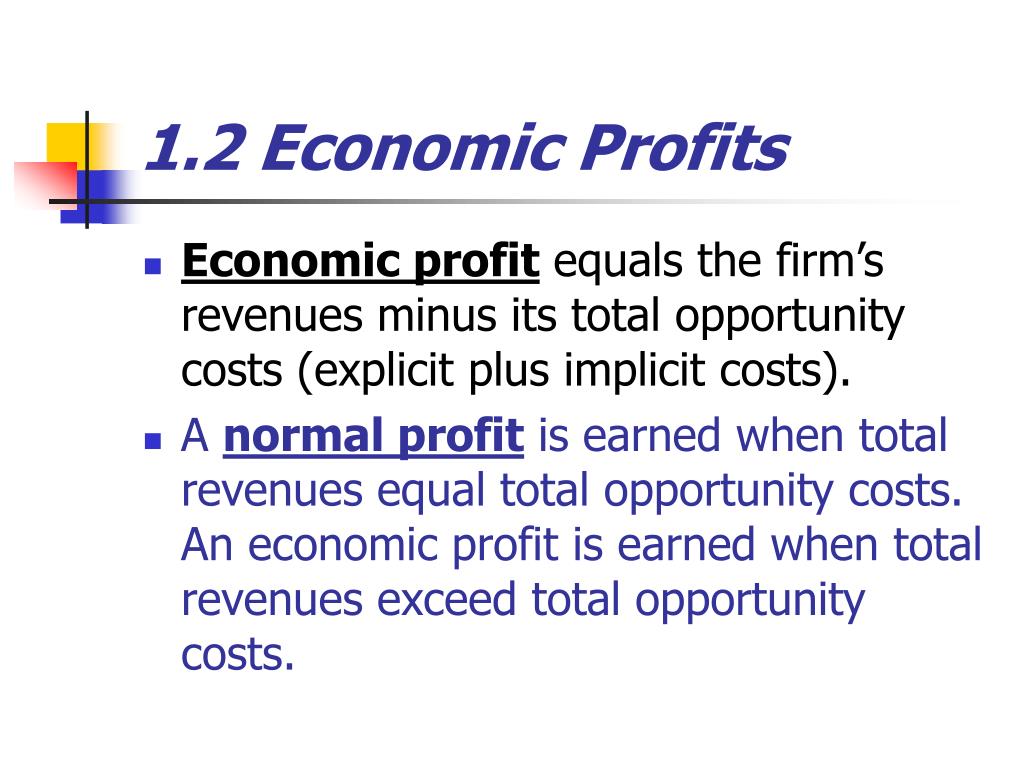
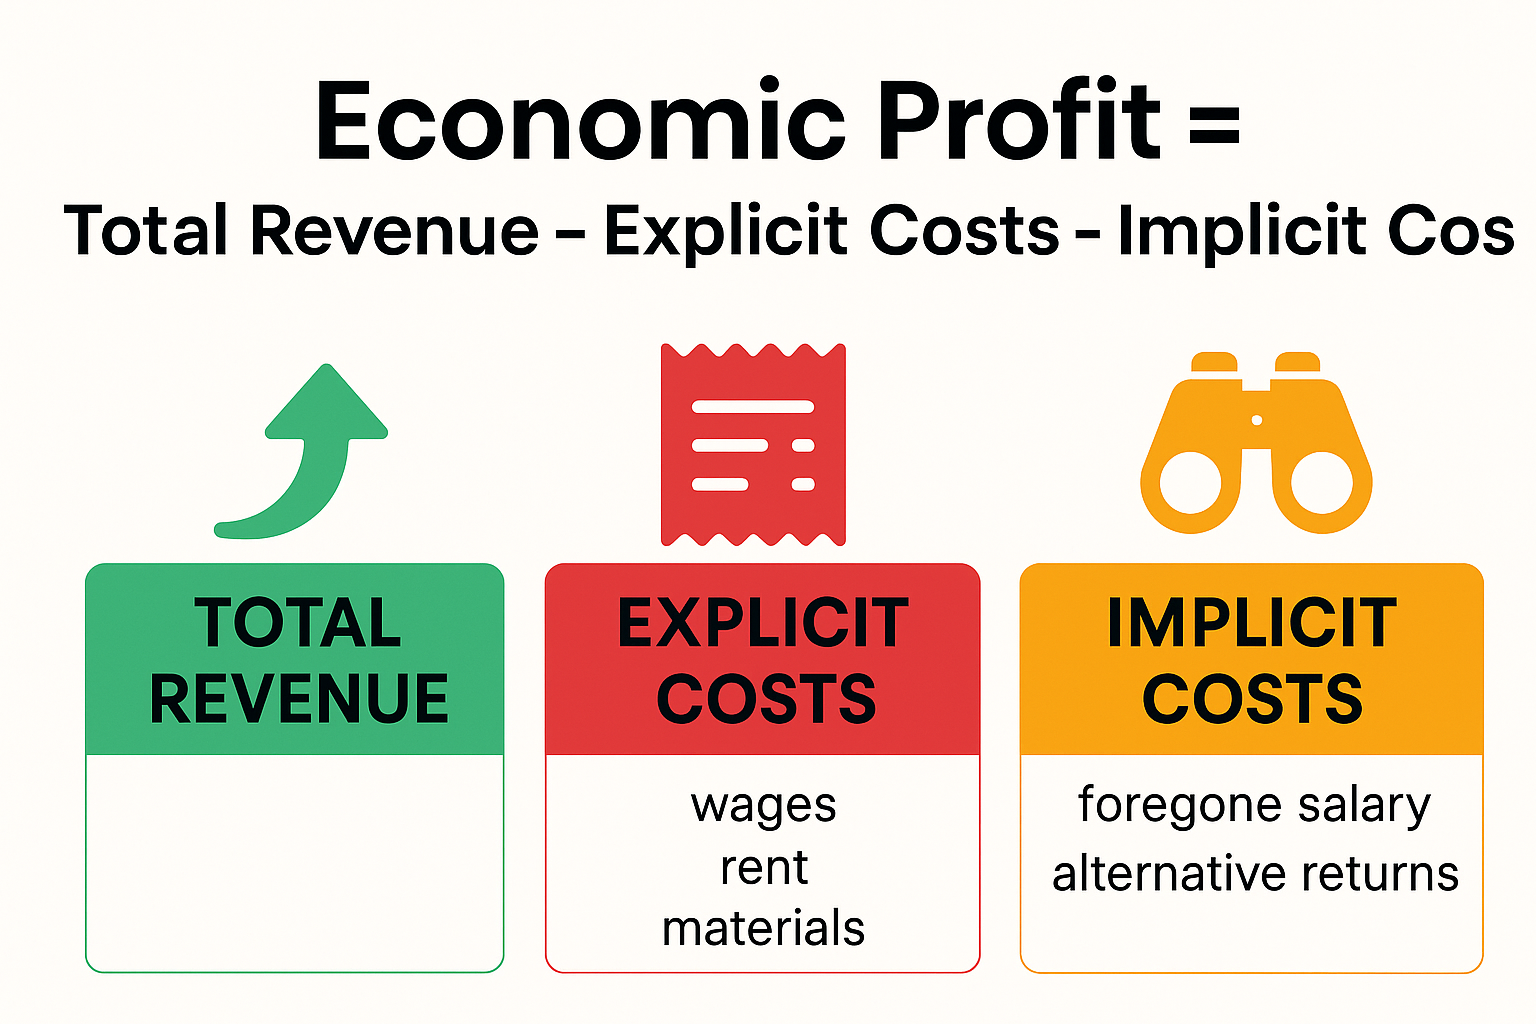
I spent years watching capital chase hot industries only to realize most of the time the returns were being eaten alive by competition. The trick isn't finding where money is flowing now, it is figuring out whether the barriers to entry are real or just temporary. Economic profits exist when a company earns more than its weighted average cost of capital plus equity risk premium. That formula sounds simple on paper, but the practical application requires digging into moat durability, regulatory capture, and how fast new entrants can replicate the value creation. In my experience tracking industry returns over a decade, the industries that consistently produced economic profits shared three characteristics: barriers that took years to build, assets that could not be easily copied, and customer switching costs that were high enough to suppress price competition.
Economic Profits In An Industry Suggest The Industry
When you see sustained economic profits across multiple years, it is telling you something specific about competitive dynamics. The first signal is concentration. Look at herfindahl-hirschman indices for the space, but do not treat them as gospel. The real story lives in pricing power, market share stability, and whether incumbents can raise prices without losing meaningful volume. Here is a practical framework I use when evaluating whether an industry generates economic profits and whether those profits will persist: Step one: Calculate return on invested capital over at least five years. If ROIC consistently exceeds the cost of capital by two percentage points or more, you have a candidate. I track this quarterly for any sector I am serious about, and I look for consistency, not spikes. One good year means nothing.
Step two: Audit the barrier types. Are they structural, regulatory, technological, or network-based? Structural barriers like capital intensity and economies of scale tend to be durable. Regulatory barriers like licenses and patents are durable until they are not, and I have seen entire industries collapse when a single court decision changed the landscape. Network effects are the strongest moat but also the most fragile. When users hit a tipping point, the whole dynamic flips quickly. Step three: Test switching costs. Run a simple model. If a customer leaves, what does it cost them? Data migration, retraining, contract penalties, workflow disruption. When switching costs exceed five percent of annual customer revenue, price competition softens noticeably. I calculated this for a mid-market ERP provider once and found that even though their product was mediocre, switching costs kept their retention above ninety-two percent. That retention rate explained most of their economic profit margin. Step four: Look for margin expansion, not just margin level. Industries with rising operating margins over time are usually gaining pricing power. Flat or declining margins despite revenue growth suggest commoditization is setting in. I track gross margin trends alongside free cash flow conversion to spot when profits become earnings quality vs. accounting illusion.
Get the Full Details

Step five: Simulate entry. Pick a profitable subsegment and ask what it would take for a competitor to enter. Estimate the capital required, the time to reach efficiency, and the likely pricing response from incumbents. If your calculation shows a rational entrant breaking even within three years, the profits are sustainable. If entry drives everyone to zero, the profits are temporary and probably already reflected in valuations. I ran this process on the specialty chemicals sector a few years back and found something counterintuitive. The companies with the highest economic profits were not the ones selling commodity products at scale. They were the niche players making custom intermediates for pharmaceutical manufacturers who could not afford supply chain disruption. The barrier was not technology, it was validation. Getting a new supplier approved by a big pharma buyer takes eighteen to twenty-four months of testing and documentation. That timeline creates de facto lock-in even without long-term contracts. The counter-intuitive part was that these niches looked unattractive to most analysts. Revenue was small, growth was slow, and the companies lacked glamour. But the economic profit sustainability was real because the switching cost calculation favored the incumbent. The pharma buyers would rather pay a ten percent premium than risk a batch failure that could delay a drug launch by months. That risk premium showed up consistently in the margins.
Another thing most people miss when evaluating economic profits is timing. Industries cycle. Capital flows in when profits look attractive, which eventually erodes the very margins that attracted the capital in the first place. The trick is identifying where you are on the cycle, not just whether profits exist today. In my work, I map industry capacity additions against historical profit cycles to estimate how much runway economic profits have left. A company reporting fifteen percent ROIC today might be earning six percent five years from now if the barrier erodes faster than expected. Here is where the method breaks down. Some industries generate economic profits that look sustainable on paper but depend on a regulatory regime that could change overnight. I tracked a regional utility once where the moat was a state-approved rate base. The numbers were clean, the cash flows were predictable, and the returns exceeded cost of capital by a comfortable margin. Then a regulatory shift allowed retail competition, and the entire profit model inverted within eighteen months. The lesson is that no barrier is permanent, and the ones that feel permanent are usually the ones you should scrutinize most. Another limitation is that economic profit calculations assume rational capital allocation by competitors. In reality, strategic rivals sometimes enter to secure market position rather than maximize returns. I saw this in the early days of European broadband rollouts, where incumbents accepted negative economic profits for several years just to block new entrants. Those losses showed up clearly in capital expenditure data even though short-term profitability looked terrible.
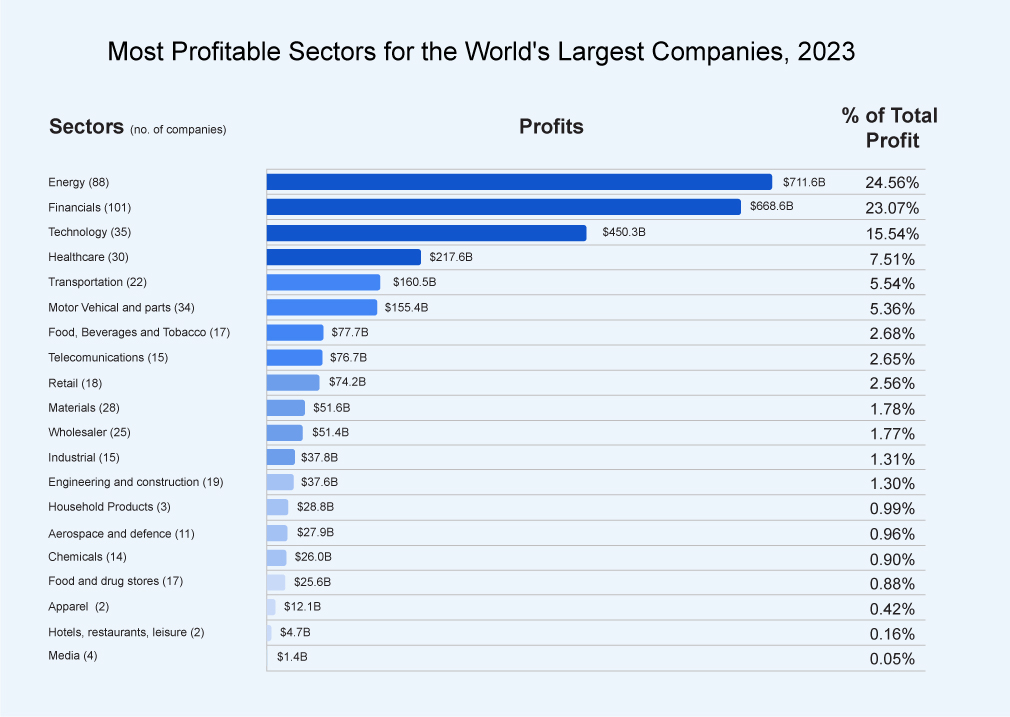
If you want a simpler approach than the full framework, start with the concentration-plus-moat screen. Filter for industries where the top four firms hold more than sixty percent of revenue, where at least one structural barrier exists, and where operating margins have expanded over the past three years. This will surface candidates quickly. It will not catch every opportunity, but it will filter out the industries where profits are ephemeral. The industries that tend to produce durable economic profits are usually narrow in scope. Software platforms with network effects, regulated utilities with captive customer bases, specialty pharmaceuticals with patent protection, and niche industrial suppliers with high switching costs. These spaces attract less attention, which is why they persist. Broad consumer markets and low-differentiation industries rarely sustain above-cost returns because competition erodes them faster than capital can reorganize. When evaluating an industry yourself, remember that the hardest part is not the calculation, it is the discipline to walk away from sectors that look profitable but lack real barriers. I have made that mistake several times, pouring analysis effort into industries where the profitability was already priced in and the moat was thinner than the headlines suggested. The screening steps above will save you that pain if you apply them consistently.
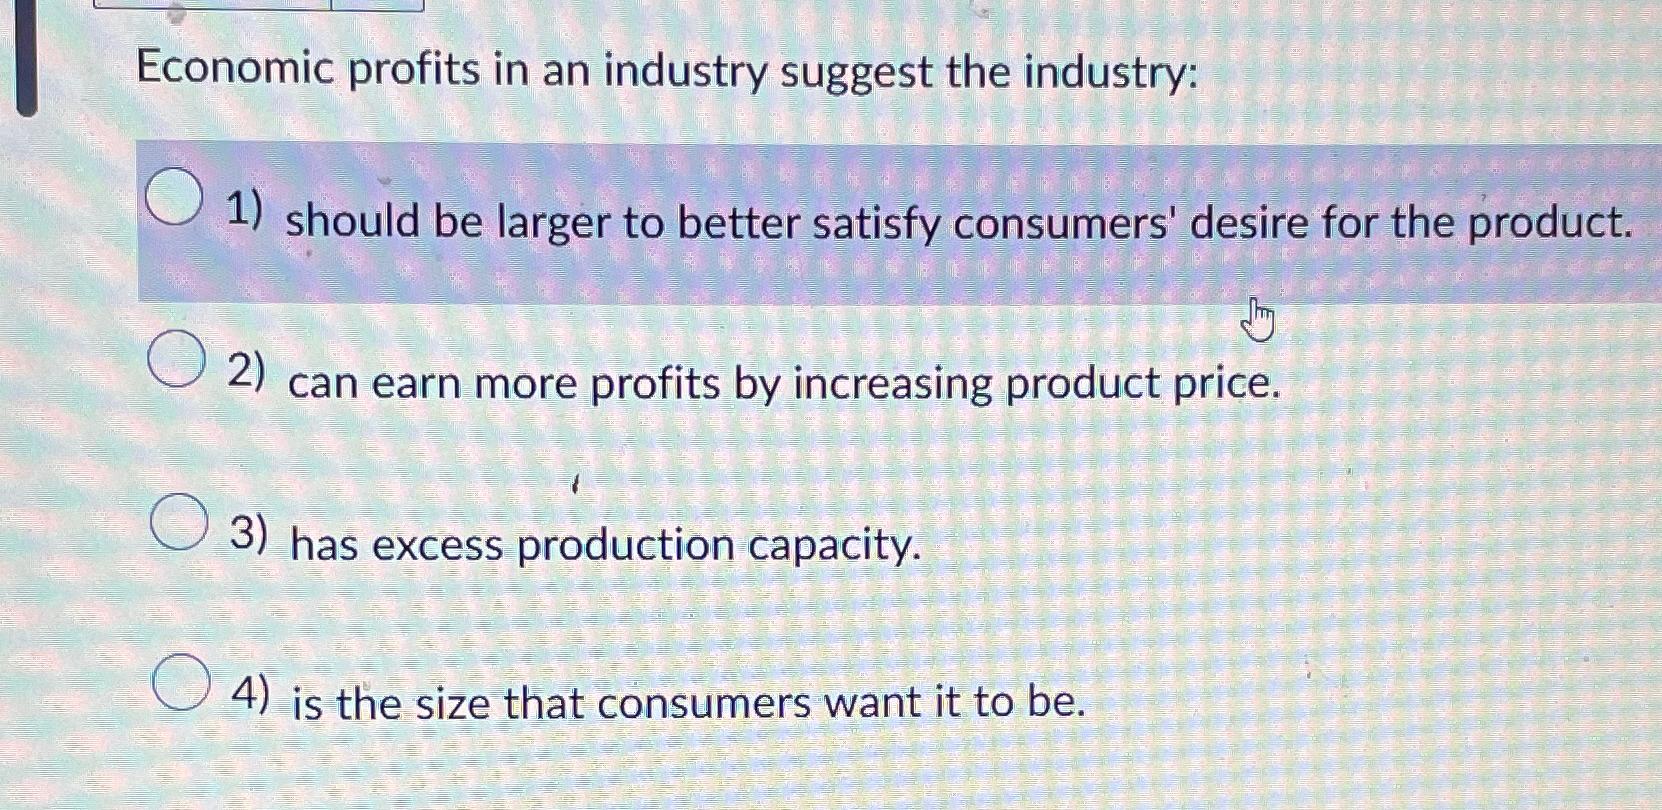
The takeaway is straightforward. Economic profits in an industry suggest the presence of durable competitive advantages, but durability varies widely across barrier types. Your job is to distinguish between profits that will persist and profits that are just noise before the competition catches up. The framework I described gives you a way to do that, even if it requires more effort than simply checking a stock screener.