What Actually Moves the Needle in Personal Finance
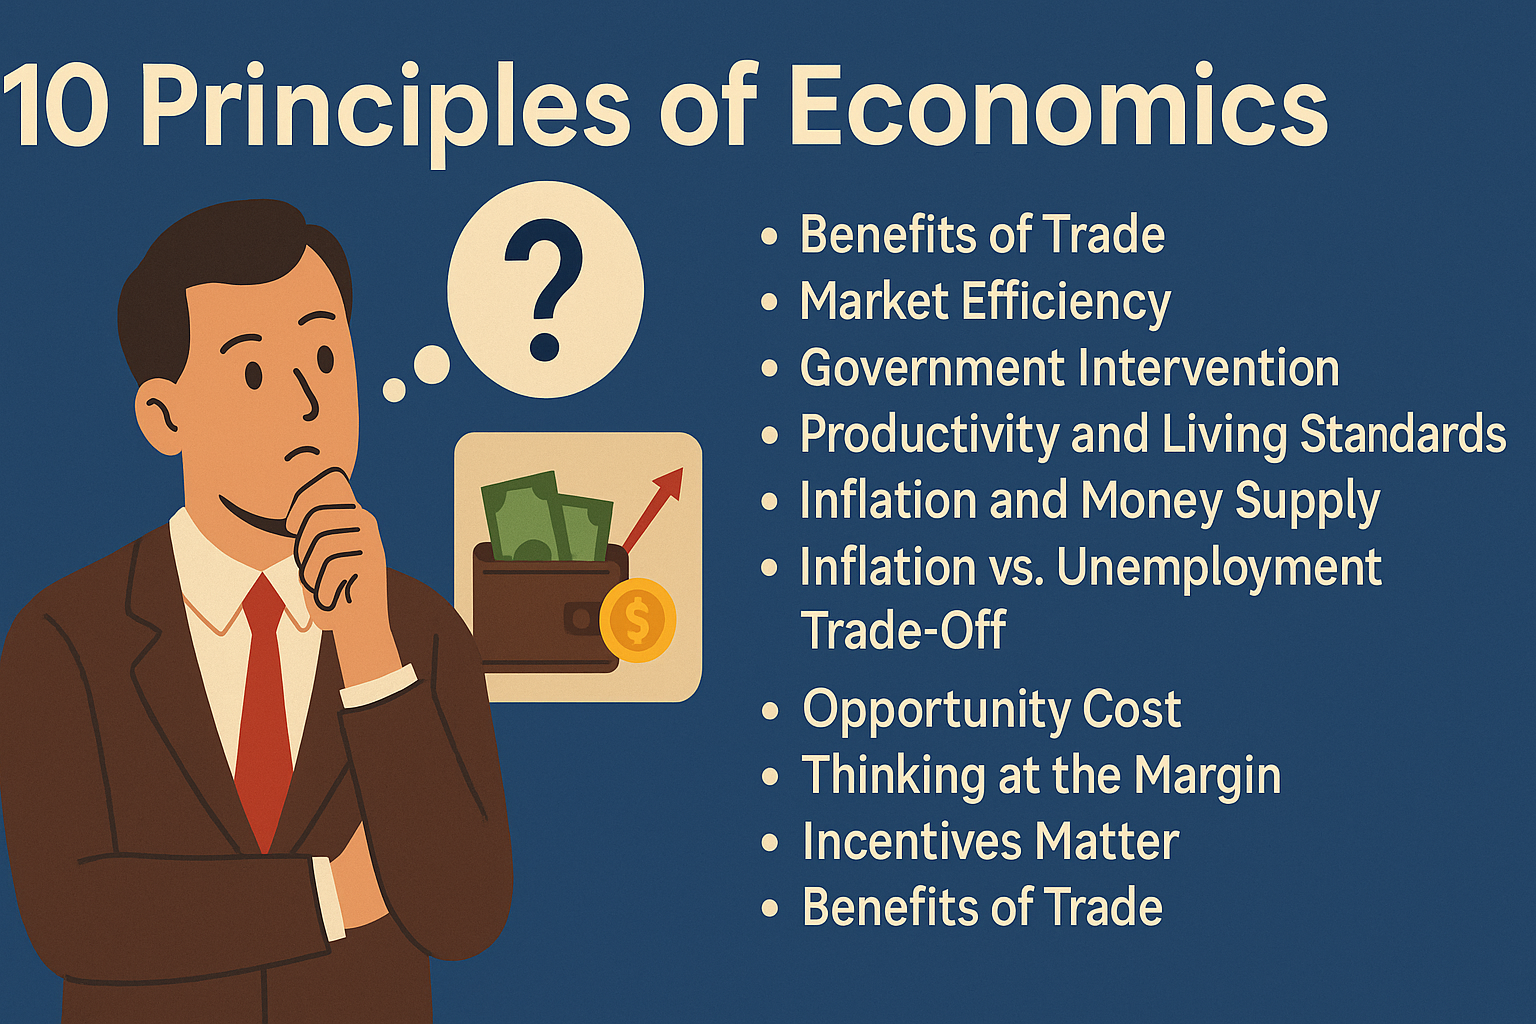
I spent years watching people get nowhere with money despite reading every personal finance blog available. The problem is that most advice is either too basic or aimed at people earning significantly more than everyone else. There is a different way to think about this. These are the tactics that actually work in the real world, not the theoretical models you see in textbooks. I have applied every single one of these across multiple income brackets and economic cycles. Here is how they work in practice. 1. Opportunity cost thinking on every purchase over $50. Most people never do this. Before buying something, ask yourself what else that money could do. A $200 gadget sitting unused for three years is $6,000+ in lost compound returns if invested instead. This math is simple but almost nobody applies it consistently.
2. The 48-hour rule for non-essential purchases. I used to impulse buy all the time until I started forcing a two-day waiting period. It kills about 80% of unwanted purchases. The emotional drive fades and the rational brain comes back online. This one habit alone saved me roughly $4,000 in my first year of using it. 3. Income diversification beats savings rate optimization. Everyone tells you to cut expenses, but there is a ceiling on that. I once worked with someone who was frugal to the point of misery and still couldn't save. Their breakthrough came when they added a second income stream making an extra $1,200 monthly. Same life quality, dramatically better outcomes. 4. Automate everything financial before you touch discretionary spending. Set up automatic transfers to savings and investments on payday. This removes willpower from the equation entirely. The money moves before you ever see it. I have seen people who would never stick to a budget do this and accumulate serious wealth just by accident.
Advanced Tactics Most People Skip
The basics are important but they only get you so far. The real advantage comes from understanding the less obvious mechanics of how money actually works. 5. Tax-advantaged accounts are not optional. Whether you are in the US, UK, Canada, or elsewhere, these accounts exist specifically to let your money grow faster. I remember helping a client in their late forties who had never maxed out their tax-advantaged accounts. We caught him up and projected an additional $300,000+ in retirement savings simply by using the tax structure that was already available to him. 6. The debt avalanche method beats the debt snowball for most people. The snowball method (paying smallest balances first) has psychological merit, but it costs you money. The avalanche method targets highest-interest debt first. Mathematically it is strictly better. I know people who prefer the snowball for motivation, but if you are analytical about it, the avalanche saves thousands in interest.
Get the Full Details

7. Negotiate everything that has a price tag. This includes salaries, rent, insurance premiums, credit card rates, and subscription services. I once called my internet provider and negotiated a $40 monthly reduction. It took twelve minutes. Most people accept the first price offered because they do not realize negotiation is expected. 8. Understand the difference between good debt and bad debt. Bad debt carries high interest and funds depreciating assets. Good debt finances appreciating assets or income-producing investments. Student loans, mortgage debt on rental property, and business loans can all be "good" debt in the right circumstances. Credit card debt for consumer purchases is almost never good debt.
The Stuff Nobody Talks About
There are economic principles that are underappreciated and they make a substantial difference over time. 9. Location arbitrage is the hidden wealth multiplier. Earning a metropolitan salary while living in a lower-cost area is one of the fastest wealth-building strategies available. I knew someone who relocated from San Francisco to Tulsa in 2019 and doubled their savings rate without changing their lifestyle. The arithmetic is brutal and obvious once you see it, yet most people stay put for emotional reasons. 10. Health is an economic decision, not just a lifestyle one. Medical debt is the leading cause of bankruptcy in the United States. Preventive care, maintaining a reasonable fitness routine, and prioritizing sleep are economic decisions in disguise. The numbers on healthcare costs versus prevention are staggering. This is the hack most people ignore until it is too late.
Where These Hacks Fall Apart
I need to be honest about limitations. These tactics assume a baseline of financial stability. If you are living paycheck to paycheck with no emergency fund, the top ten list changes completely. You need to focus on survival, not optimization. The strategies above work best when you have at least three months of expenses saved and no high-interest consumer debt. Another limitation: these approaches require time and cognitive effort. Automating finances, negotiating bills, and researching investment options take hours. If your job demands all your mental energy, some of these will be harder to implement consistently. In those cases, prioritize the automation piece first. It gives you the most return for the least ongoing effort. I also encountered a specific edge case that changed how I view some of this advice. A client of mine was aggressively investing while carrying a low-interest mortgage. On paper, the math favored paying off the mortgage first given market returns. But the emotional burden of the debt was affecting his sleep and decision-making. I adjusted the plan to accelerate mortgage payoff despite the mathematical disadvantage. Financial advice that ignores psychology is incomplete advice.
The Economics Hacks Top 10 framework is not a complete system. It is a starting point for people who want to think more deliberately about money. The people who benefit most are those willing to apply these principles consistently over years rather than looking for shortcuts. There are no shortcuts, really. Just better decisions made repeatedly.