The Definition Most Professors Get Wrong
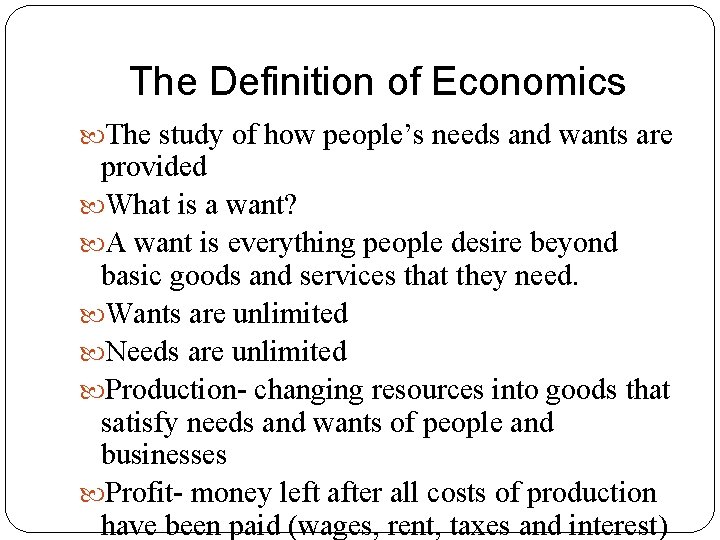
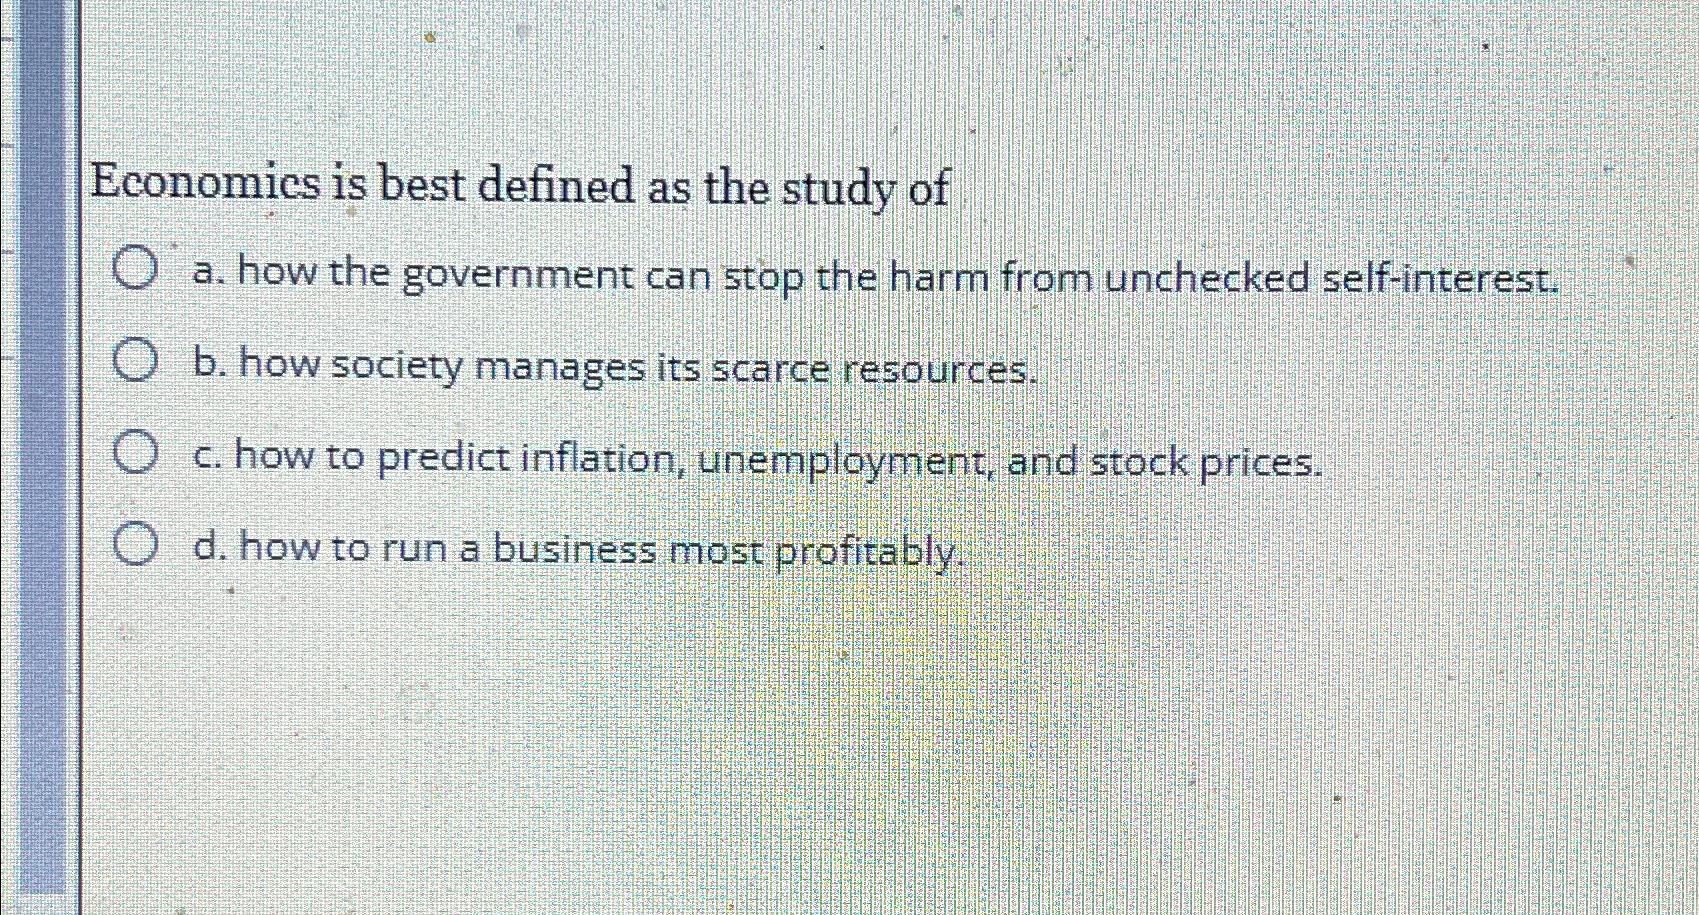
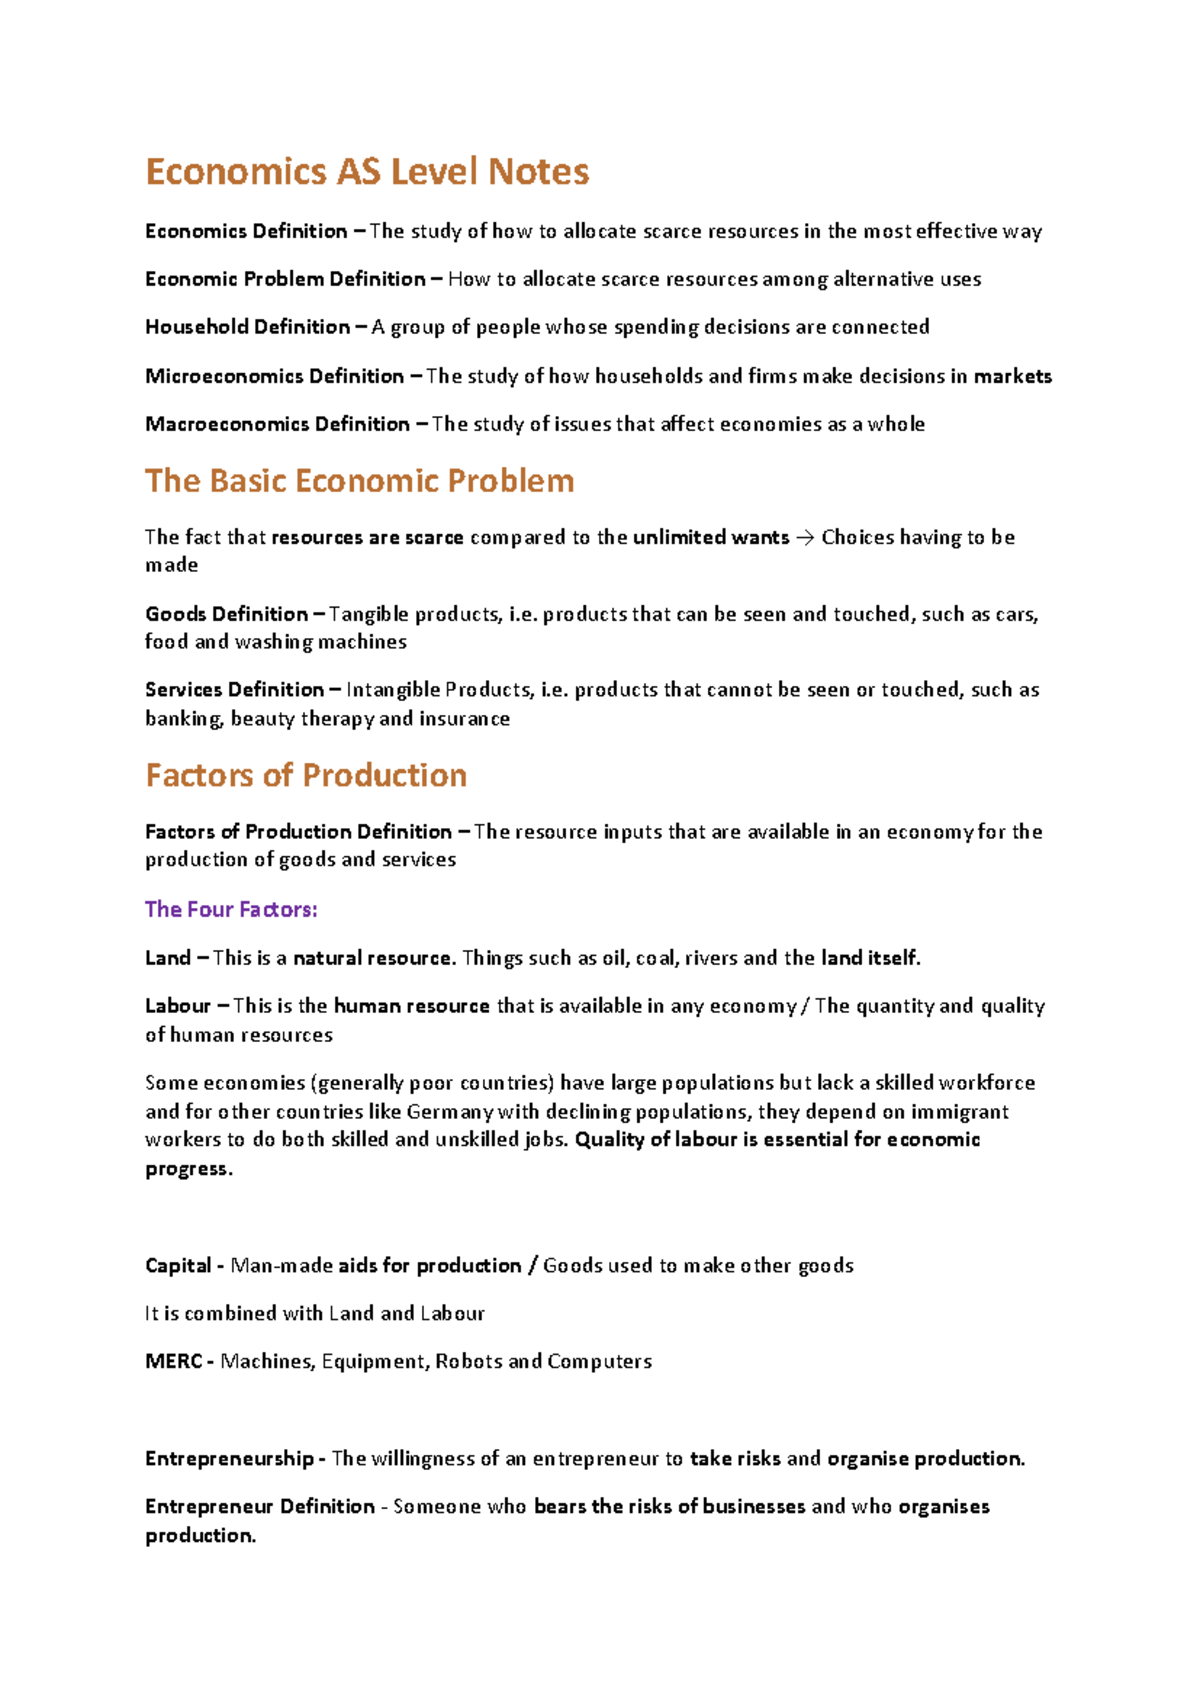
Economics is most commonly introduced as "the study of scarcity and choice," but that framing leaves out half the practical work most economists actually do. If you look at what professional economists spend their time on, the definition that holds up better is that Economics Is Best Defined As The Study Of How People and Institutions Make Decisions Under Constraints. It sounds dry, but it is closer to the daily reality of the field. I used to teach introductory material to undergraduates and watched students bounce between two completely different definitions depending on which textbook their advisor recommended. The scarcity version works fine for a first week of class. The decision-under-constraints version carries further into actual research and policy work. Both are technically correct. One is just more useful once you leave the classroom. The scarcity framing emphasizes that resources are limited and wants are unlimited. That is true, but it stops being helpful the moment you try to model anything real. The constraints framing opens the door to actually specifying what those limits are: budgets, time, information, institutional rules, physical laws. Economics becomes a study of optimization problems rather than a philosophy lecture about desire.
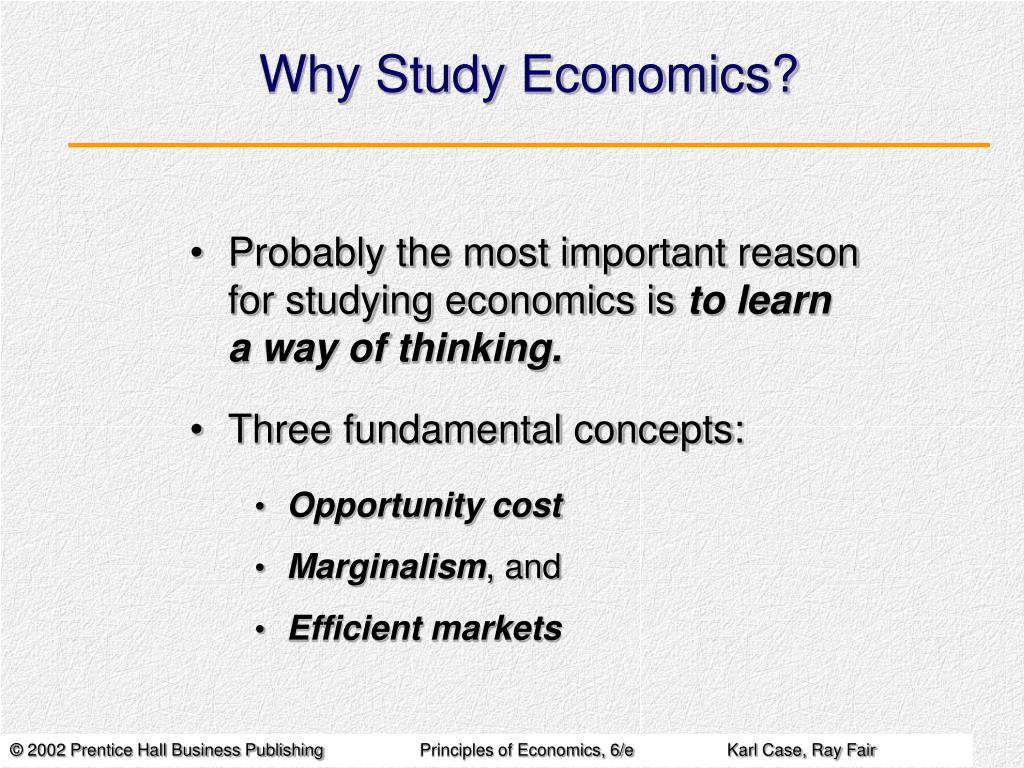
Opportunity cost is the tool that bridges both definitions. It measures what you give up when you pick one option over another. Every economist I know uses it constantly, even when they do not name it explicitly. The reason it matters is that opportunity cost is rarely obvious. It depends on the next best alternative, which changes based on context, timing, and available information.
How the Definition Shows Up in Actual Work
When I ran regression analyses on labor market data for a state policy evaluation a few years back, the textbook definition did not prepare me for the messy boundary between individual choice and structural constraint. A local manufacturing plant had shut down unexpectedly, and unemployment claims spiked in three counties. The naive reading suggested that displaced workers were choosing not to search. The data told a different story. Many had stopped searching because the nearest viable employer was forty miles away, and transit options were nonexistent. The constraint was geography and infrastructure, not motivation. I ended up restructuring the analysis to include commuting time as a hard constraint variable rather than treating labor force participation as purely a preference decision. That shift changed the policy recommendation entirely. Instead of programs targeting job-search motivation, the recommendation became transit subsidies and remote-work incentives. The difference matters when you are asking people to spend taxpayer money.
Get the Full Details
Common Pitfalls Beginners Miss
Beginners tend to treat models as descriptions of reality rather than tools for isolating specific mechanisms. A ceteris paribus assumption means holding everything else constant so you can see one variable's effect. In practice, nothing stays constant. The mistake is forgetting that the model is doing work by simplifying, not by claiming the world is simple. Another frequent error is conflating correlation with causal structure. Two variables moving together does not tell you which one drives the other, or whether a third factor is pulling both. Instrumental variable techniques exist to address this, but they come with their own assumptions about relevance and exclusion restrictions. If those assumptions fail, the estimates are not just slightly off. They are directionally wrong, and the math will not warn you. Marginal thinking is another area where people stumble. The concept itself is straightforward: decisions happen at the margin, not in binary all-or-nothing choices. The mistake is applying marginal analysis to situations where the relevant margin is poorly defined or invisible. Hiring decisions, for example, often involve discrete lumpy choices rather than smooth marginal adjustments. Treating them as continuous can produce misleading predictions.
When the Standard Definition Breaks Down
The constraints-and-decisions framework performs poorly in contexts where preferences are endogenous and shaped by the same institutions being studied. Behavioral economics has documented this extensively. People do not enter a market with stable, pre-existing preferences. Advertising, social norms, and platform design alter what people want in the first place. When preferences shift because of the environment, defining economics purely as decision-making under fixed constraints misses a critical feedback loop. Institutional economics attempts to address this by treating rules and norms as the constraints themselves, but the approach often sacrifices predictive precision for descriptive accuracy. You gain insight into why institutions persist. You lose the ability to forecast short-term behavior reliably. Neither outcome is wrong. They serve different purposes. General equilibrium models represent the most ambitious application of the constraints framework. They attempt to model the entire economy as a system of interdependent markets clearing simultaneously. The mathematics is elegant. The empirical application is extremely limited because the required data and computational assumptions are rarely satisfied in real-world policy scenarios. These models are better understood as conceptual scaffolding than operational tools for most practitioners.
A Practical Workaround for Ambiguous Constraints
When I encountered situations where the binding constraint was unclear, I found it useful to specify multiple competing constraint hypotheses and test which one the data supported rather than assuming the obvious one. In the manufacturing plant closure case, the initial hypothesis was that income constraints were binding. Testing revealed that spatial constraints dominated. The workaround was not clever. It was just refusing to commit to a single constraint specification before the evidence arrived. This approach does not solve every ambiguity. It slows down analysis enough that you notice your own assumptions instead of burying them in the model structure. That delay usually prevents embarrassing policy errors.
Why the Definition Matters More Than It Appears
The definition you adopt shapes which questions you consider legitimate and which you dismiss. If you define economics narrowly as price theory, you overlook behavioral anomalies, institutional arrangements, and power asymmetries that influence outcomes. If you define it too broadly as any study of choice, you risk losing analytical tractability entirely. The constraint-based definition occupies a middle ground that allows formal modeling without pretending the constraints are exogenous or obvious. It also aligns more closely with how economists actually write papers. The abstracts usually state a constrained optimization problem, identify the relevant boundaries, and estimate how changes to those boundaries affect outcomes. That is the definition in practice, even when textbooks lead with scarcity instead.