Working Through Central American Markets: What Nobody Tells You
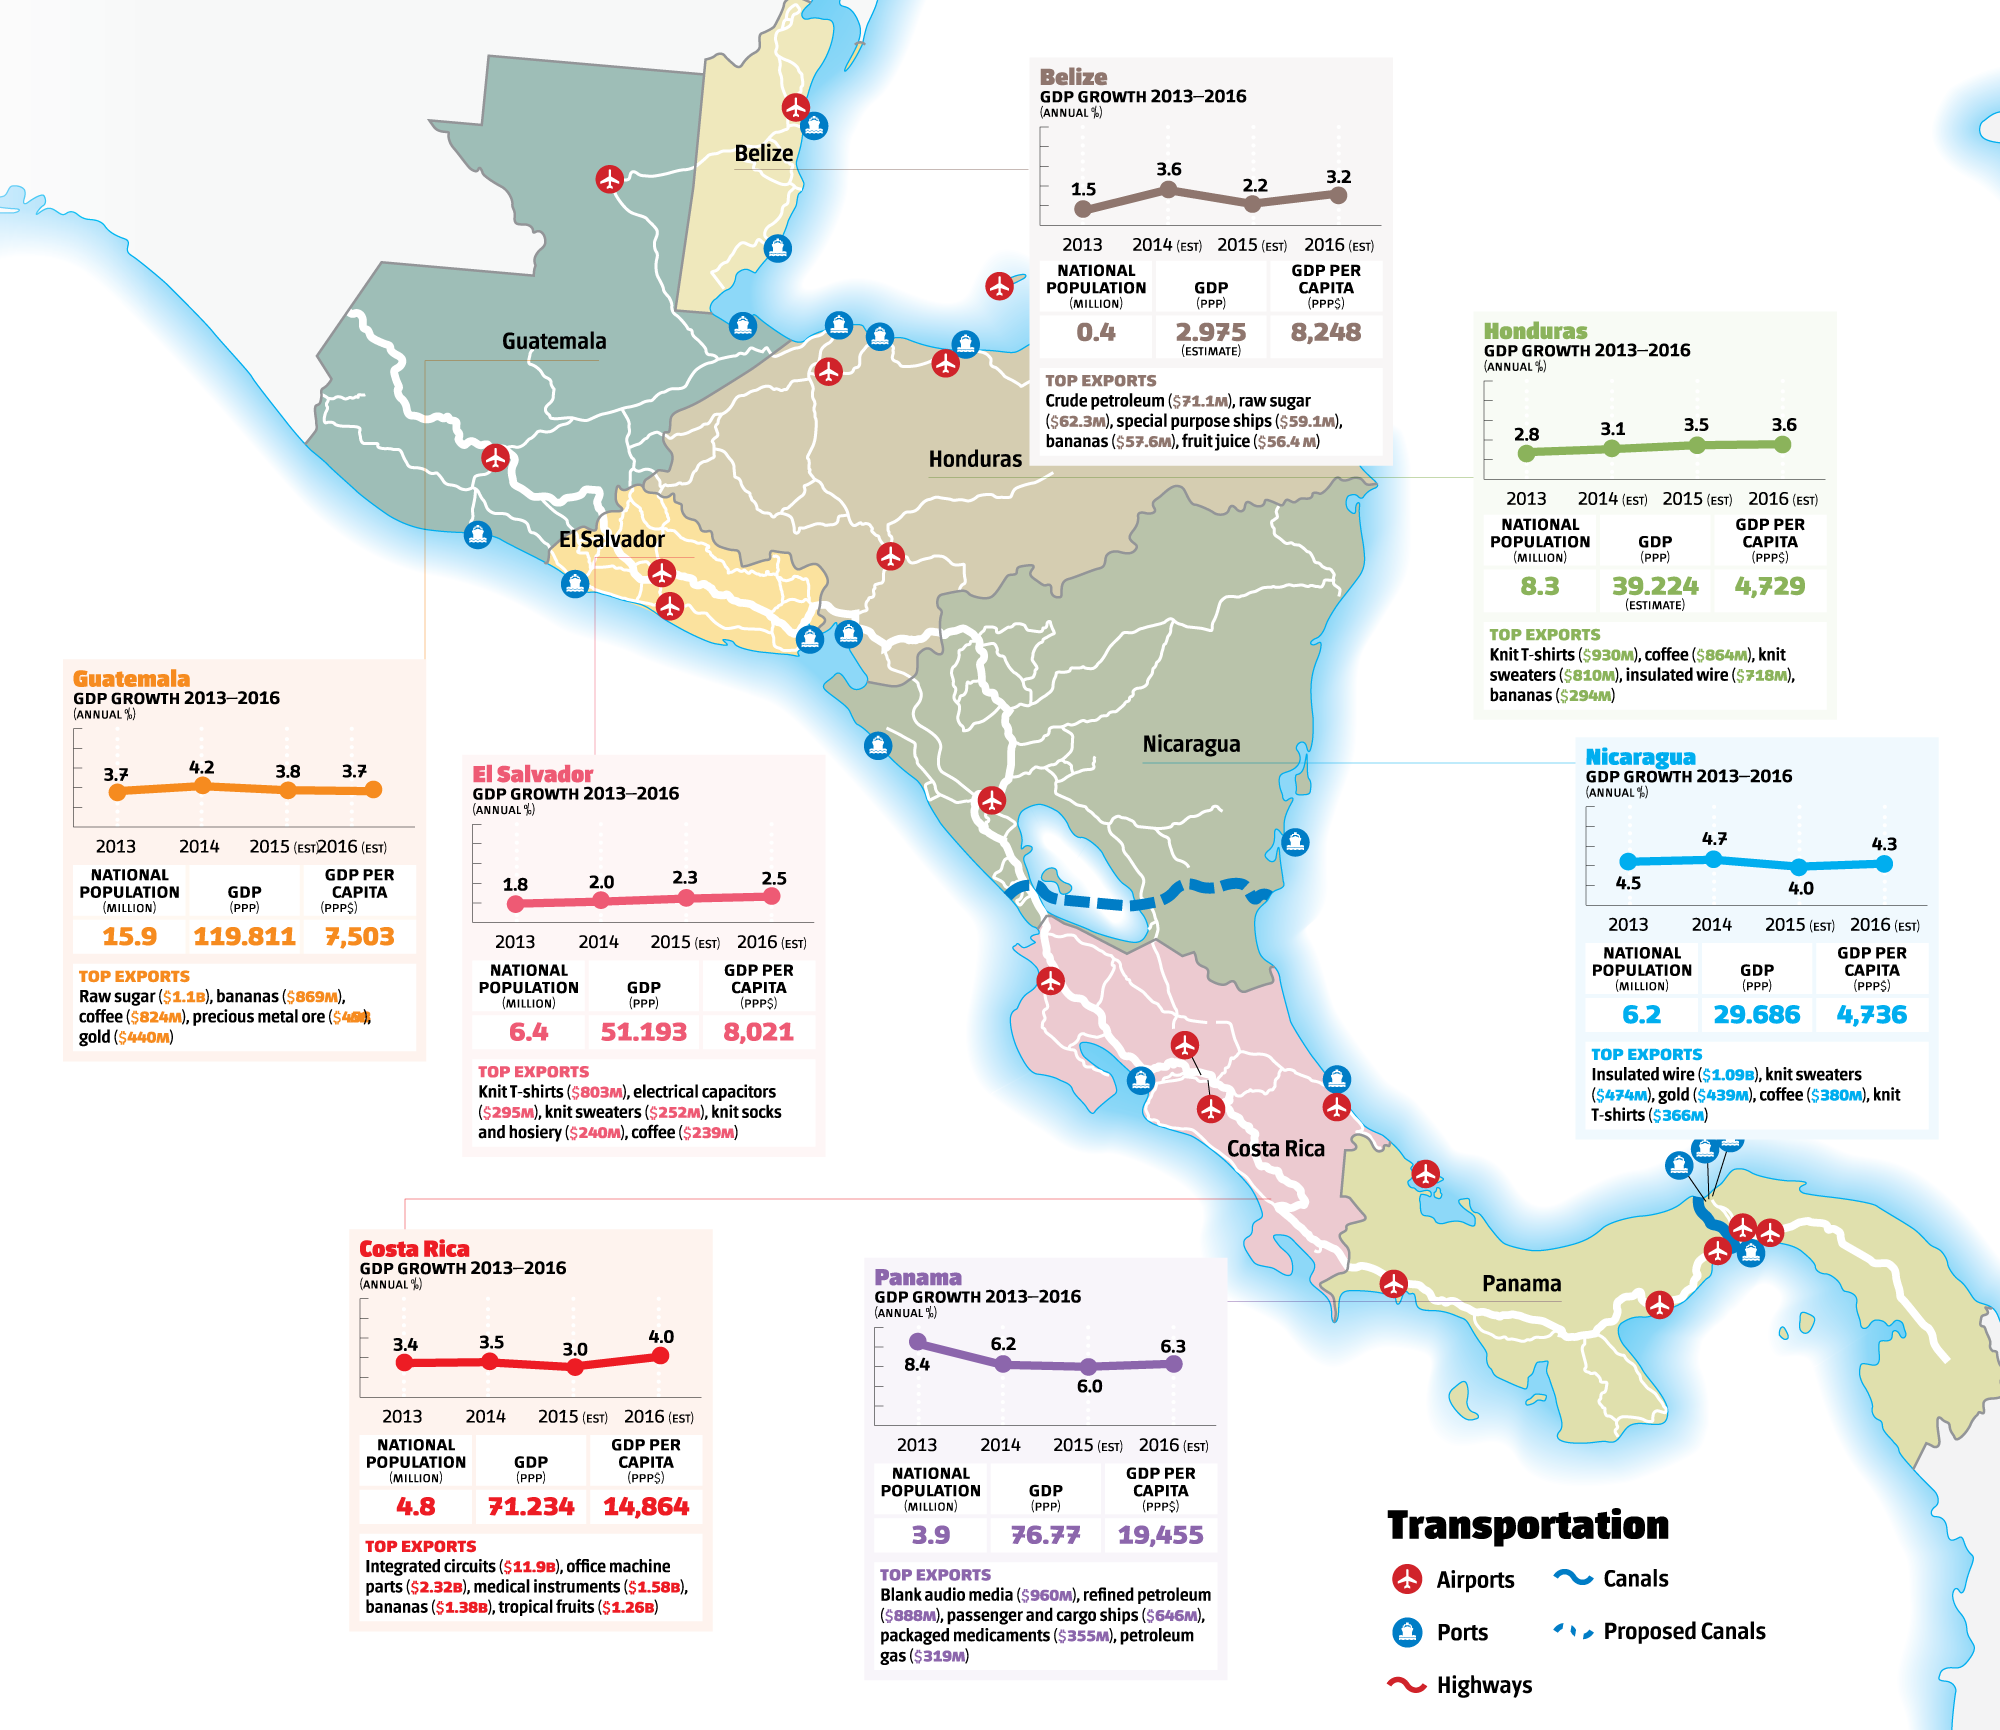
The economics of Central America is a region where the textbook definitions fall apart somewhere around the border controls. I've spent more time than I care to admit tracking how remittances, trade agreements, and currency policy actually move money through this part of the world. The macro numbers are one thing. The micro reality is another. Start with what matters: remittances. They account for roughly 17% of GDP across the region on average, but the distribution is wildly uneven. Guatemala pulls in about $20 billion annually in remittances, while El Salvador's economy is essentially built around them at around $6-7 billion. When you're modeling anything for this region, that inflow is your baseline. Ignore it and your forecasts are wrong before you start. The CAFTA-DR agreement is the trade framework everyone references, but here's what most analyses miss: the actual utilization rate for preferential tariffs is nowhere near 100%. In my experience working with exporters moving goods through the corridor, companies typically claim preferential rates on about 60-70% of eligible shipments. The gap comes from documentation headaches and the fact that rules of origin are genuinely tricky to satisfy when your supply chain crosses multiple Central American countries before reaching a final market.
I once had a client trying to export textile assemblies from Honduras into Costa Rica under CAFTA-DR and hit a wall because the fabric was cut in Mexico and sewn in Honduras. The rule of origin requires the entire production process to qualify, and partial processing doesn't cut it. We ended up restructuring their supply chain entirely — sourcing fabric from a CAFTA-eligible supplier in the Dominican Republic instead. That added maybe 8 cents per unit in cost but saved them the full tariff differential of around 12%. That's the kind of math that matters in this market.
The Dollarization Question
El Salvador adopted the US dollar as legal tender in 2015, replacing the colon. On paper this was supposed to bring stability and lower borrowing costs. The data is mixed. Inflation did converge toward US levels, and credit spreads narrowed initially. But the country gave up monetary policy as a tool, which became a liability when regional shocks hit that didn't match US Federal Reserve priorities. Panama has operated under a similar dollar-based system for decades, and it works reasonably well because Panama's economy is structured differently — more services-oriented, less dependent on commodity cycles. For anyone doing business across the region, the dollarization creates a split reality. Transactions in El Salvador and Panama are priced and settled in USD, but Guatemala, Honduras, Nicaragua, and Costa Rica all maintain their own currencies. Exchange rate risk between the colón, lempira, córdoba, and colon costs businesses more than they usually budget for. I've seen margin models break because someone assumed a stable 2% annual depreciation when the lempira actually moved 15% in a single quarter during a regional liquidity crunch.
Get the Full Details

Trade and Industrial Policy Realities
The maquila sector — essentially assembly and export processing — is a significant employer in Guatemala and Honduras, particularly in textiles and light manufacturing. These zones operate under special customs regimes that defer or eliminate duties on imported inputs. The theory sounds sound. The practice has issues. I've observed that compliance costs for smaller manufacturers trying to access these regimes can be disproportionate. The paperwork alone takes roughly 40-60 hours per shipment cycle for a mid-size operation. That's not trivial overhead. Agriculture remains the backbone for much of the rural economy. Coffee, bananas, sugar, and beef dominate exports from different countries in the region. The problem is concentration. A handful of large producers control the majority of export volumes, which means price signals at the farm level are often disconnected from international commodity prices. Smallholder farmers, who make up the bulk of agricultural producers, typically receive 30-40% of what the export price reflects. This isn't new information, but it matters for any economic model that assumes transparent price transmission.
Infrastructure and Logistics Costs
Trading within Central America is surprisingly expensive given how close the countries are. Moving a container from Guatemala City to San José costs roughly the same as moving it from Los Angeles to Guadalajara, according to World Bank logistics indices. Port congestion, road quality, and border delays compound each other. The Pacific corridor — Guatemala to Honduras to El Salvador to Nicaragua — has seen some improvement with highway upgrades, but the Caribbean corridor through Belize and eastern Honduras remains a bottleneck. If you're planning logistics for this region, budget 2-3 additional days for cross-border transit compared to domestic moves in North America. I learned this the hard way when a shipment sat at the Las Mezquitas border crossing for four days because of a document discrepancy that could have been resolved with a phone call. The broker on the Guatemalan side and the one on the Honduran side weren't communicating. Having both brokers on a group chat cut our average border delay from three days to eight hours on subsequent shipments.
Where the Models Break Down
Standard economic forecasting tools perform poorly in Central America. IMF and World Bank projections routinely miss by 2-4 percentage points on growth forecasts for this region. The main reason is that these models don't capture informal economic activity well, and the informal sector in countries like Nicaragua and Honduras is estimated at 40-50% of GDP. Weather shocks also hit harder and faster than models account for — a single hurricane season can wipe out 3-5% of GDP for the affected countries, and recovery timelines are rarely built into baseline projections. The biggest blind spot I've encountered is the treatment of remittances as exogenous. Most models take remittance flows as given. In practice they're deeply endogenous — they respond to employment conditions in the US, immigration policy shifts, and exchange rate movements simultaneously. When the US labor market tightened in 2022, remittance growth to Central America slowed noticeably, and no major forecast had flagged that connection clearly enough. If you're building economic analyses for this region, the most reliable approach combines formal sector data with remittance flow tracking from the central banks and independent sources like the Inter-American Development Bank's remittance dashboards. Cross-reference those against currency reserves and you'll get a much clearer picture of actual liquidity conditions than GDP figures alone will ever give you.