What Actually Goes Into a Yearly Economics Plan
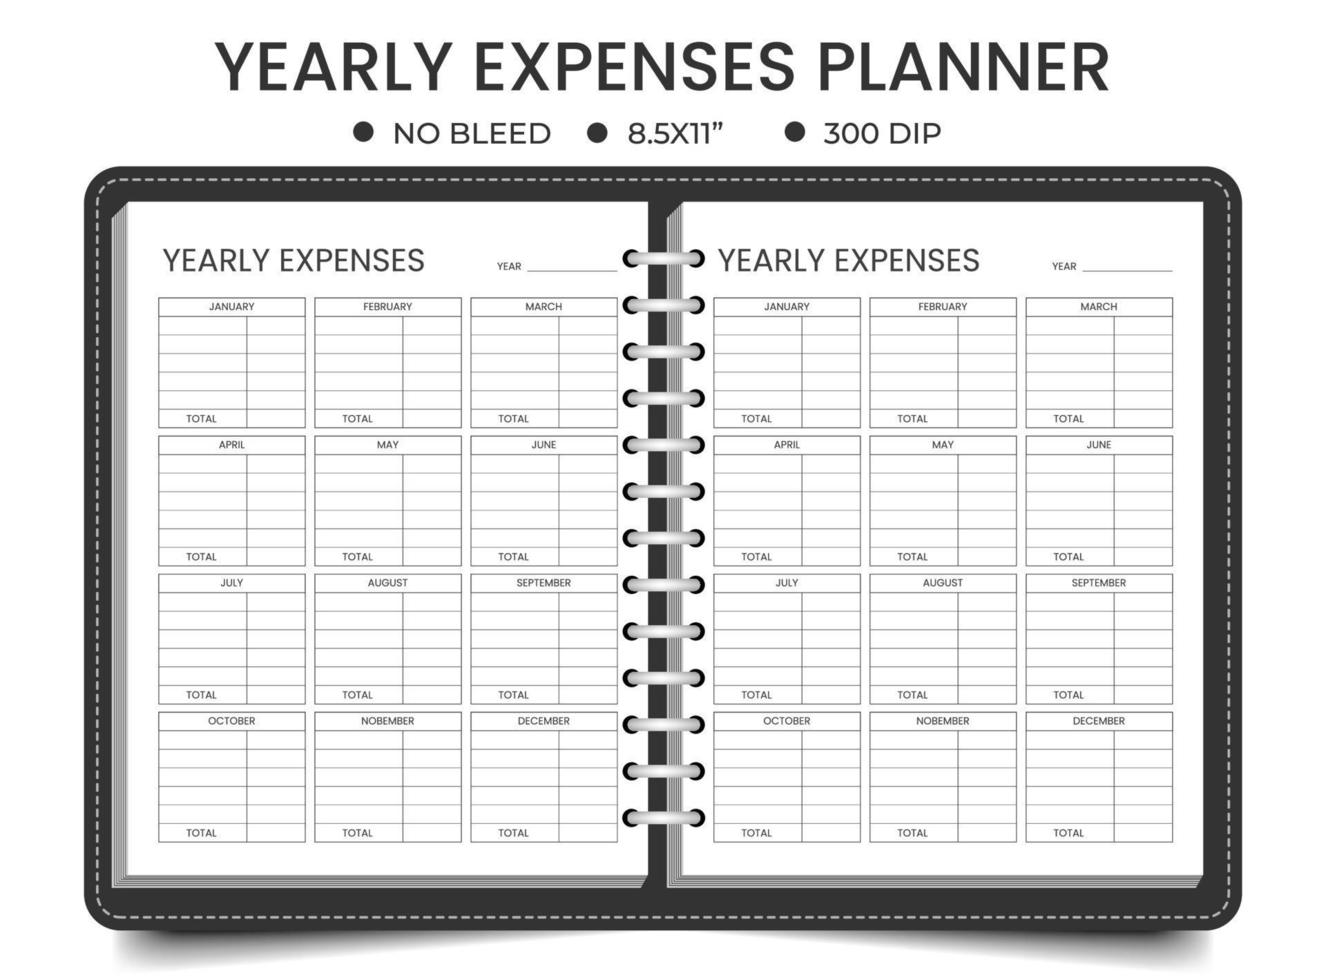
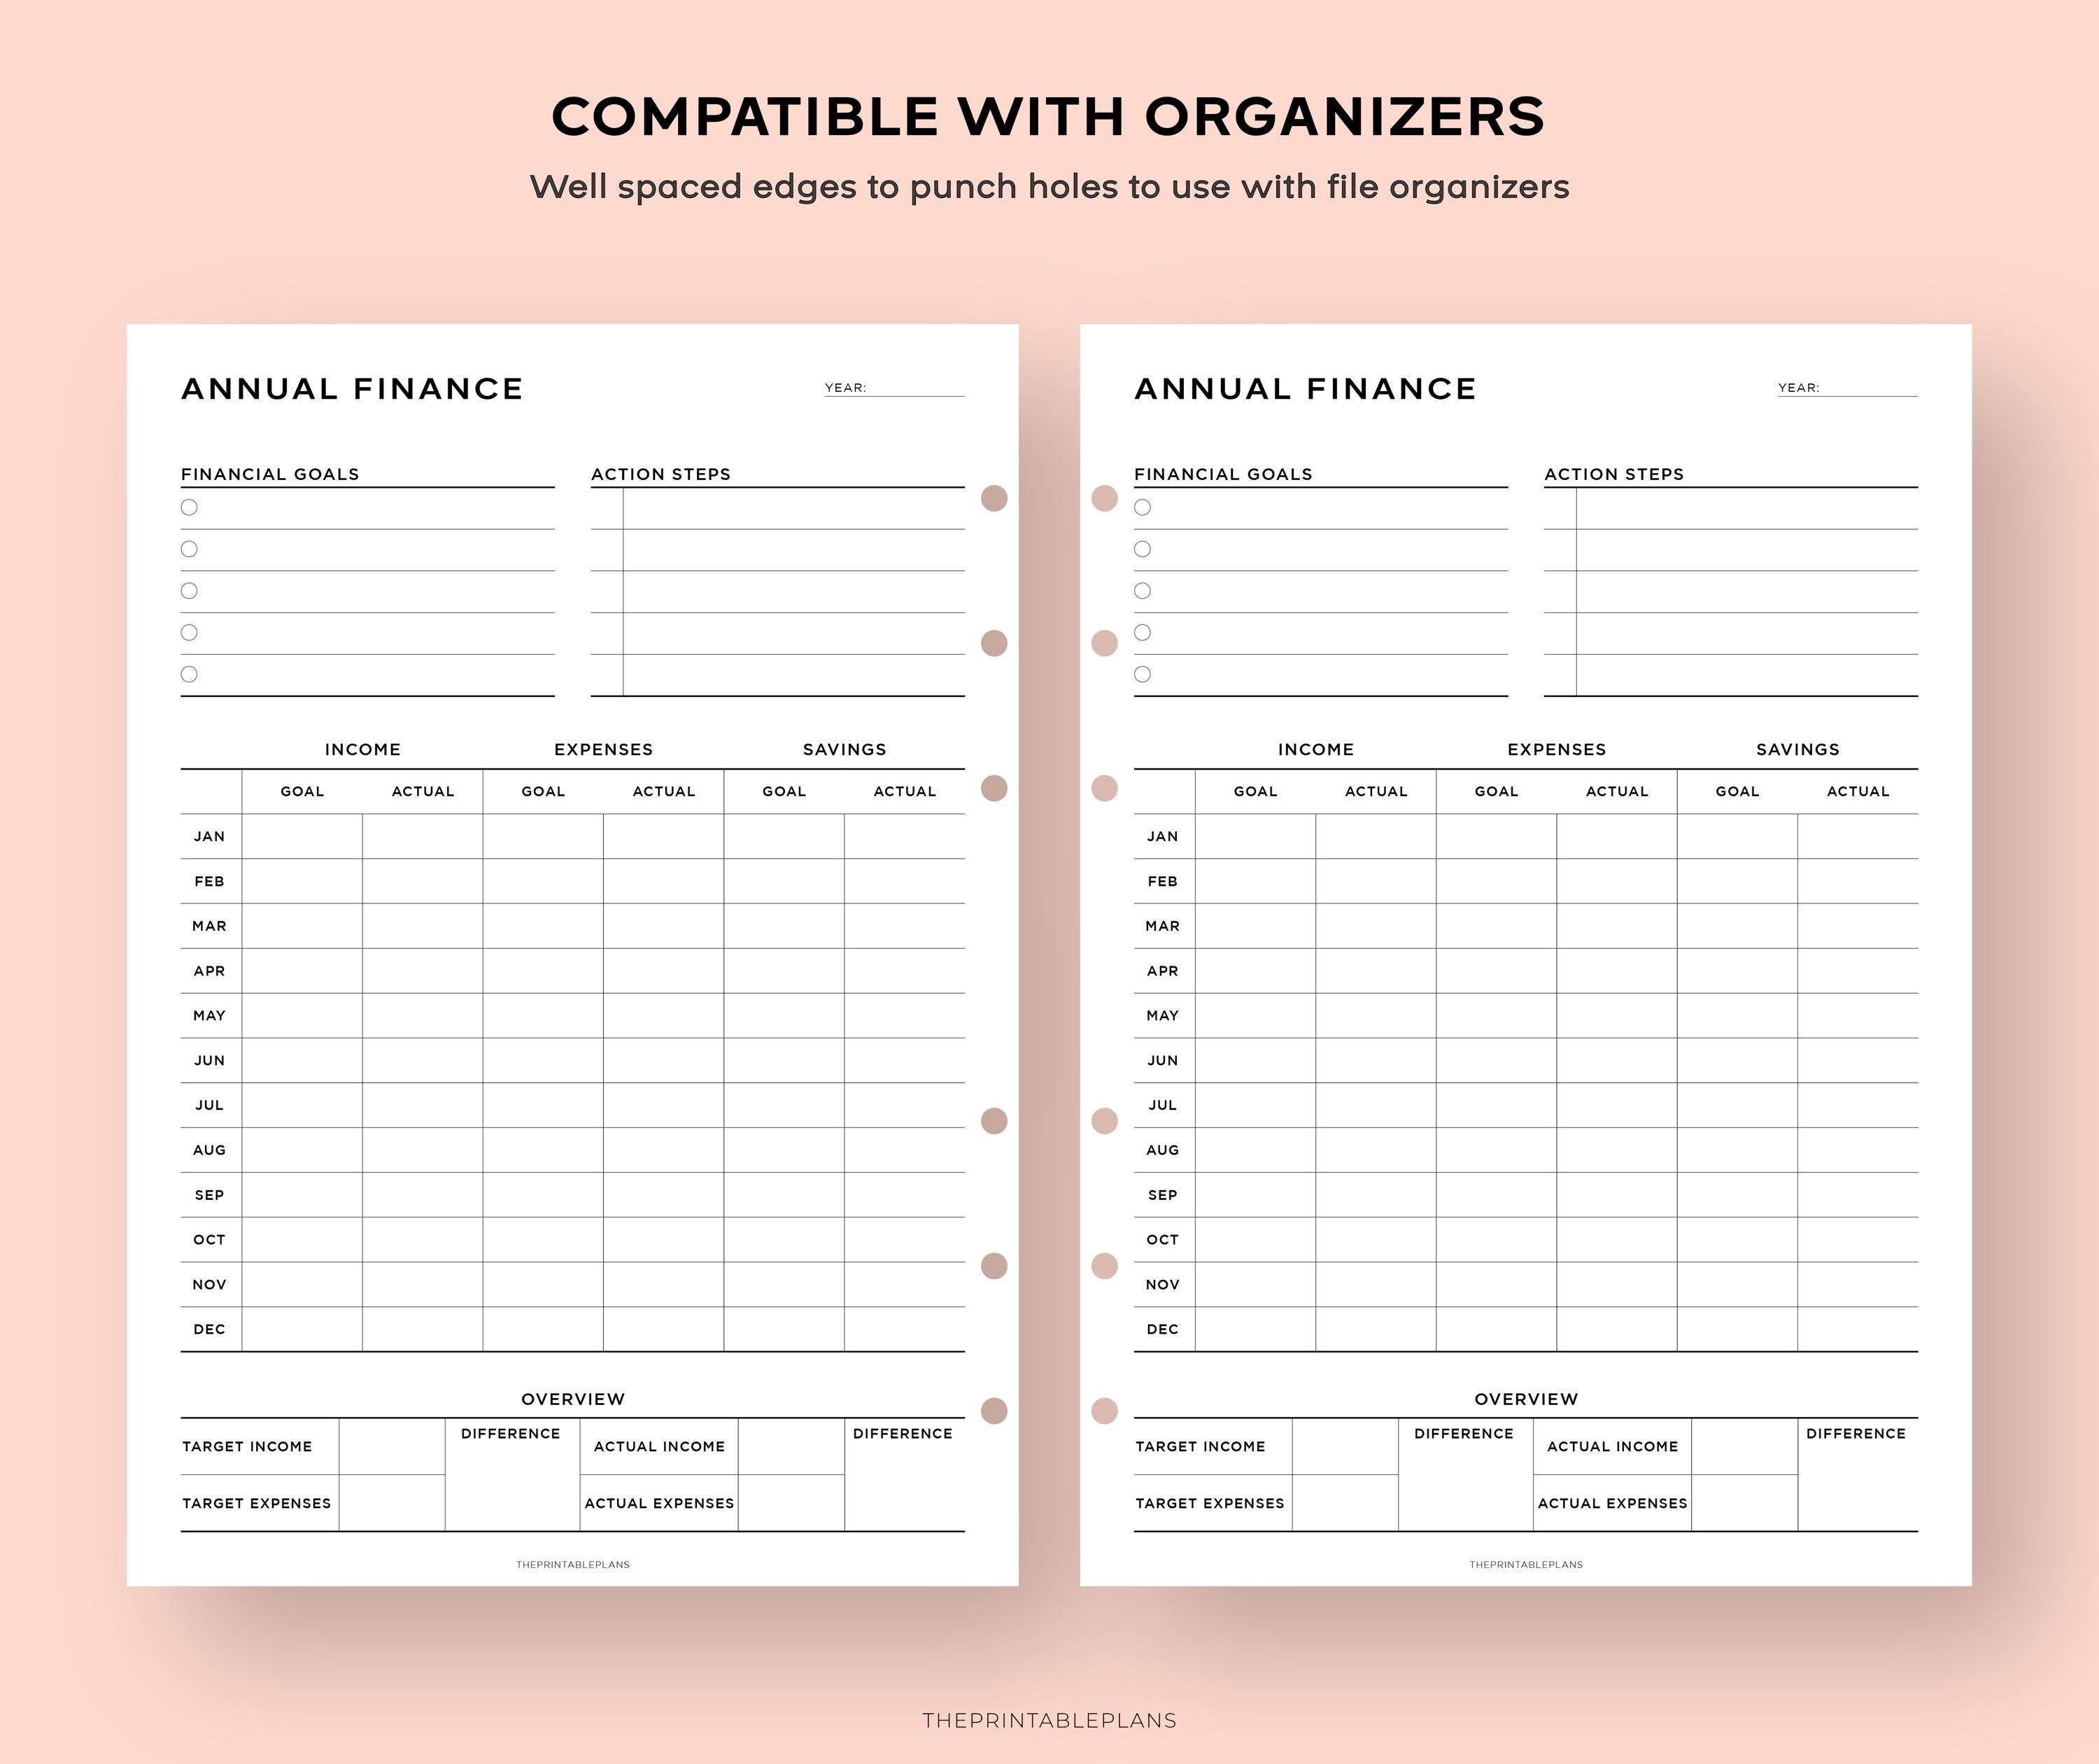
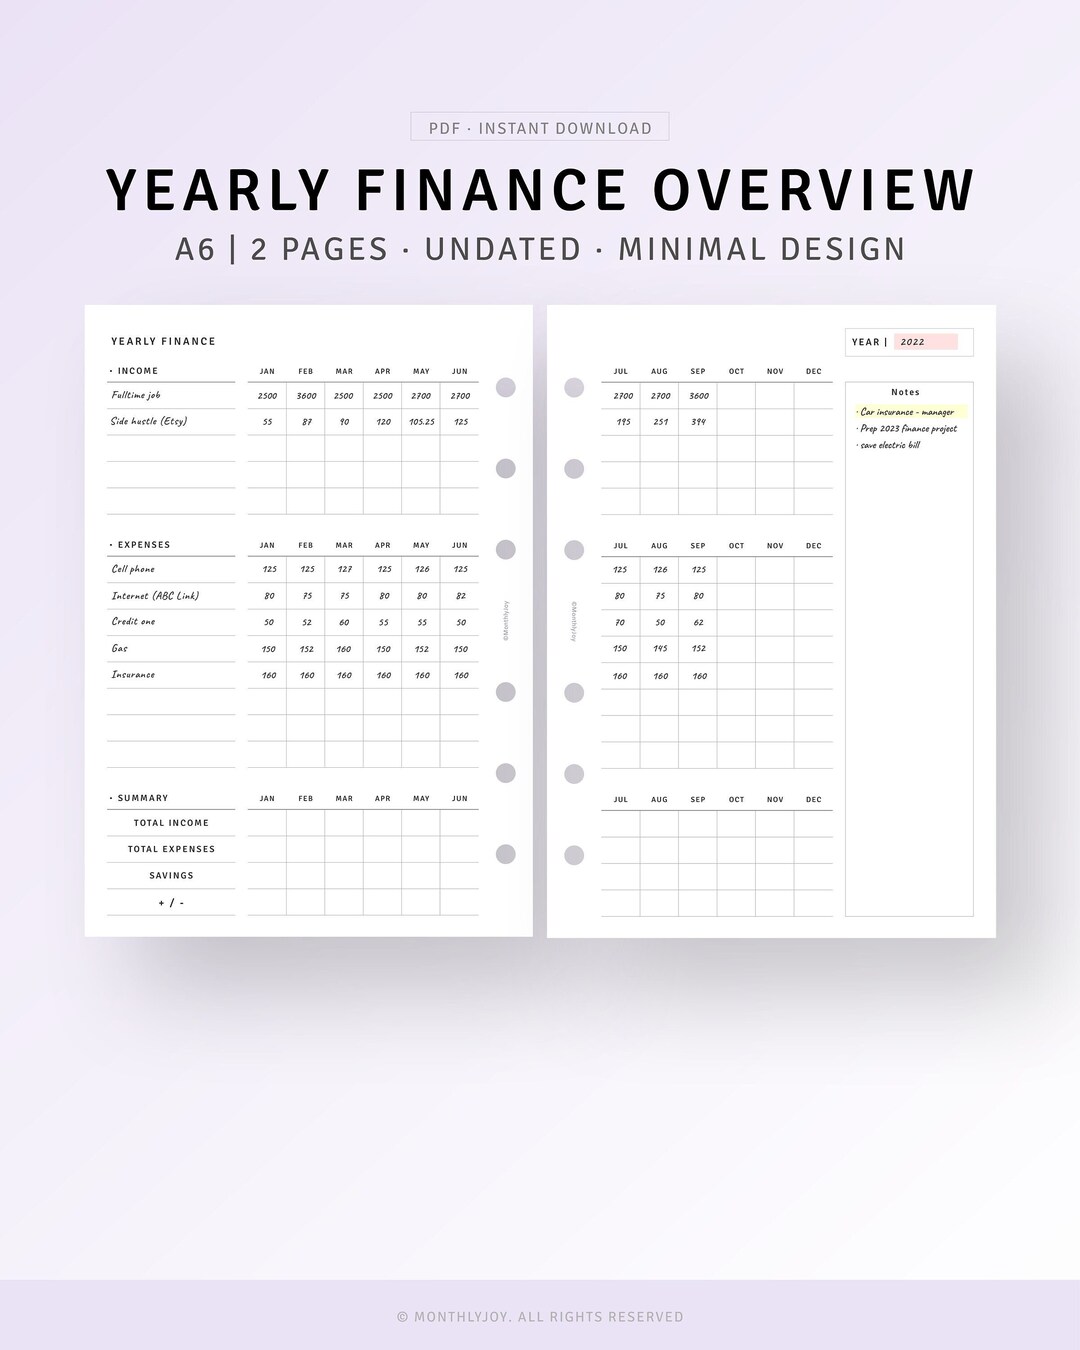
A yearly economics planner is just a structured way to track revenue, expenses, and cash flow across twelve months. Most people overcomplicate it. You need income projections, fixed costs, variable costs, and a buffer. That's it. The tool matters less than the discipline of actually updating it every month. I built my first one back in 2016 using a basic Excel sheet with twelve columns. It took three weeks to set up properly because I kept trying to account for every possible scenario. Now I use a simplified version that takes about two hours to update annually and fifteen minutes per month. The difference is knowing what actually moves the needle versus what's just noise.
Economics Planner Yearly: What You Actually Need
Here's the structure that works without turning into a full-time job: Revenue section. Project monthly income based on last year's actuals, not your hopes. If you made $42,000 in January last year, start there. Adjust for known changes — a raise, a new client, a seasonal dip. Don't guess. Look at the data. Fixed expenses. Rent, insurance, subscriptions, loan payments. Things that don't care how much money you made this month. List them. All of them. I once missed a $180/year software license until the third quarter because I only tracked monthly recurring costs. It cost me a surprise cash crunch in July.
Variable expenses. Inventory, contractor payments, marketing spend, utilities that fluctuate. These are where most plans fall apart because people either ignore them or round them too aggressively. Use actual ranges from the previous year, not single estimates. Cash flow buffer. This is the part nobody includes until they need it. Set aside 10 to 15 percent of projected income for unexpected gaps. I run a 12 percent buffer and it's saved me twice in three years from having to borrow against future revenue.
Get the Full Details
How to Build It Without Losing Your Mind
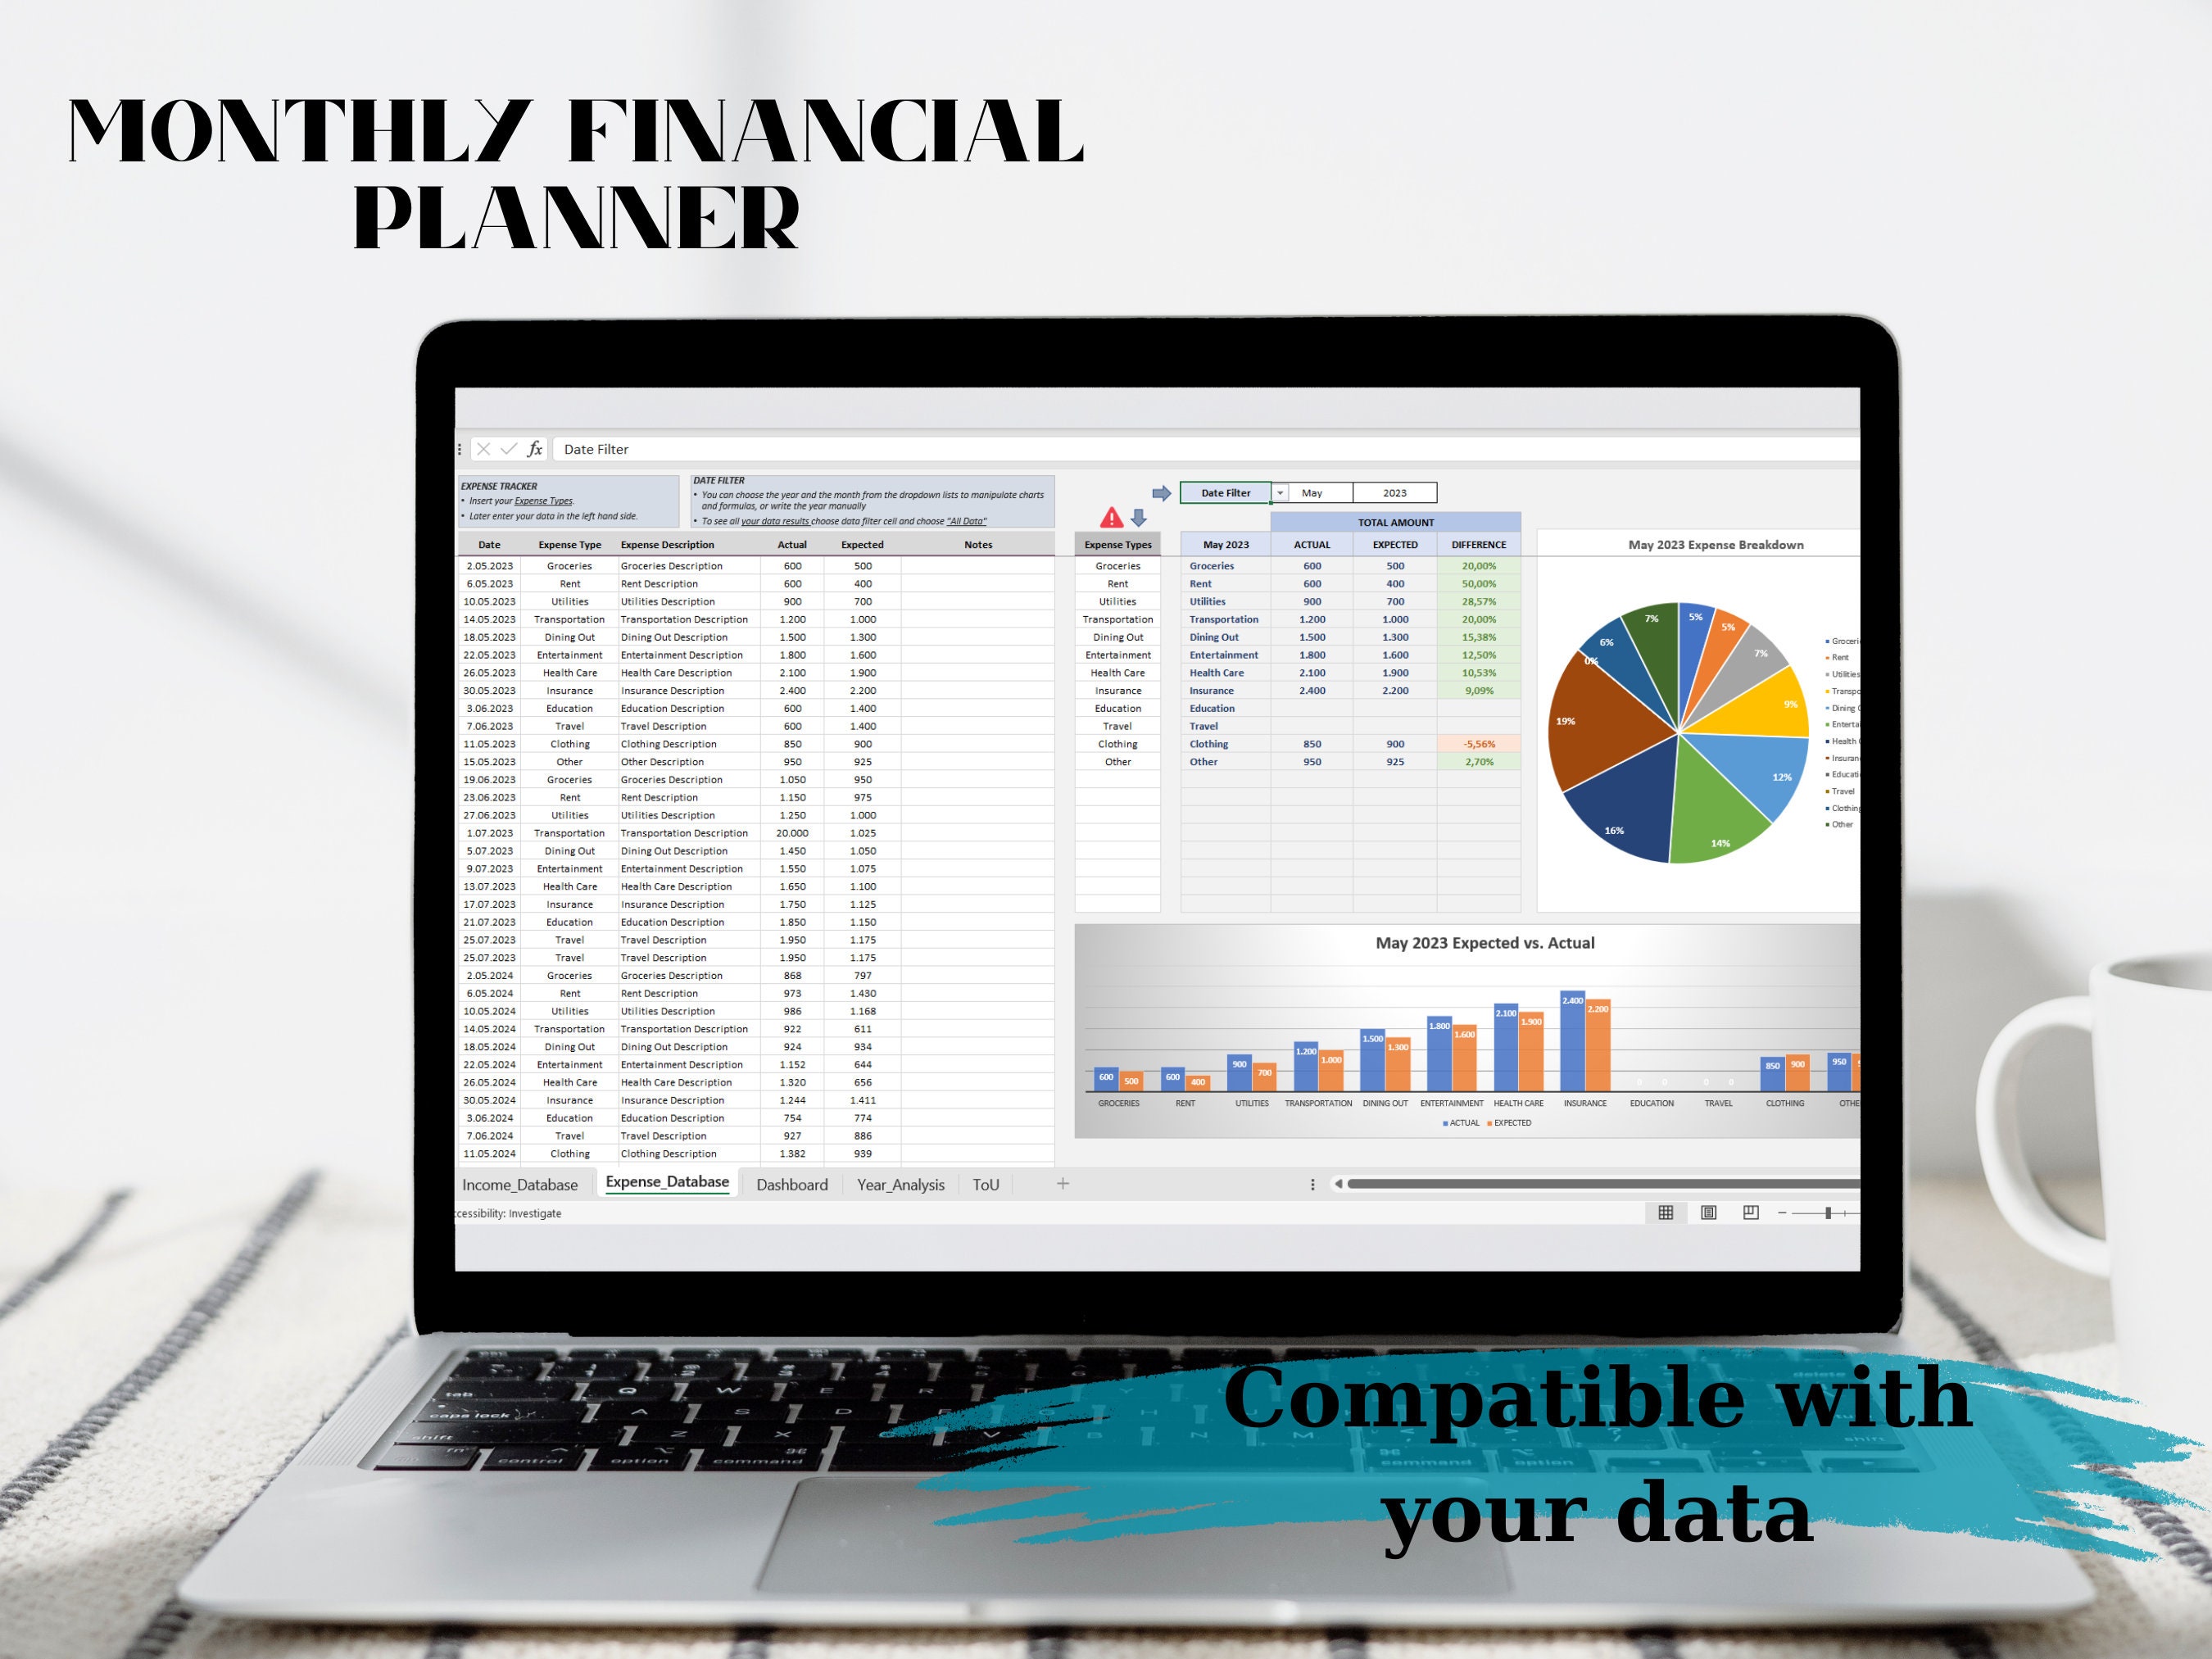
Start with a blank sheet. Google Sheets or Excel both work fine. I prefer Google Sheets because I can access it from my phone when I need to update something quickly. That small convenience actually matters for consistency. Create these rows in this order:
- Month headers (January through December)
- Beginning cash balance
- Projected income by source
- Total income
- Fixed expenses
- Variable expenses
- Total expenses
- Net cash flow
- Ending cash balance
The ending balance of one month becomes the beginning balance of the next. This linkage is what makes the whole thing functional. A lot of people build static monthly sheets that don't connect. That defeats the purpose entirely. I learned this the hard way in 2019. I had twelve separate monthly sheets with no carryover. When June came around and expenses were higher than expected, I had no idea what my actual cash position was because I'd lost track of the running total. Took me four hours to reconstruct everything from bank statements. Never again.
The Counter-Intuitive Part Most People Miss
Updating your planner regularly matters more than building it perfectly. A mediocre planner that you update monthly beats a masterpiece you build once in January and never touch again. I've seen people spend entire weekends designing beautiful color-coded dashboards with conditional formatting and pivot tables. Then they abandon it by February because it became a chore to maintain. Keep it simple. Simple enough that a tired Sunday evening update takes ten minutes. If it takes longer than that, you've added unnecessary complexity. Another thing nobody tells you: your first year's projections will be wrong. Not slightly wrong. Significantly wrong. Even if you're meticulous, something will shift — a client cancels, a supplier raises prices, an expense appears that you didn't know existed. The planner isn't a crystal ball. It's a tracking system. Its real value shows up in months three through six when you can compare actuals against projections and course-correct before small issues become emergencies.
Download and Setup
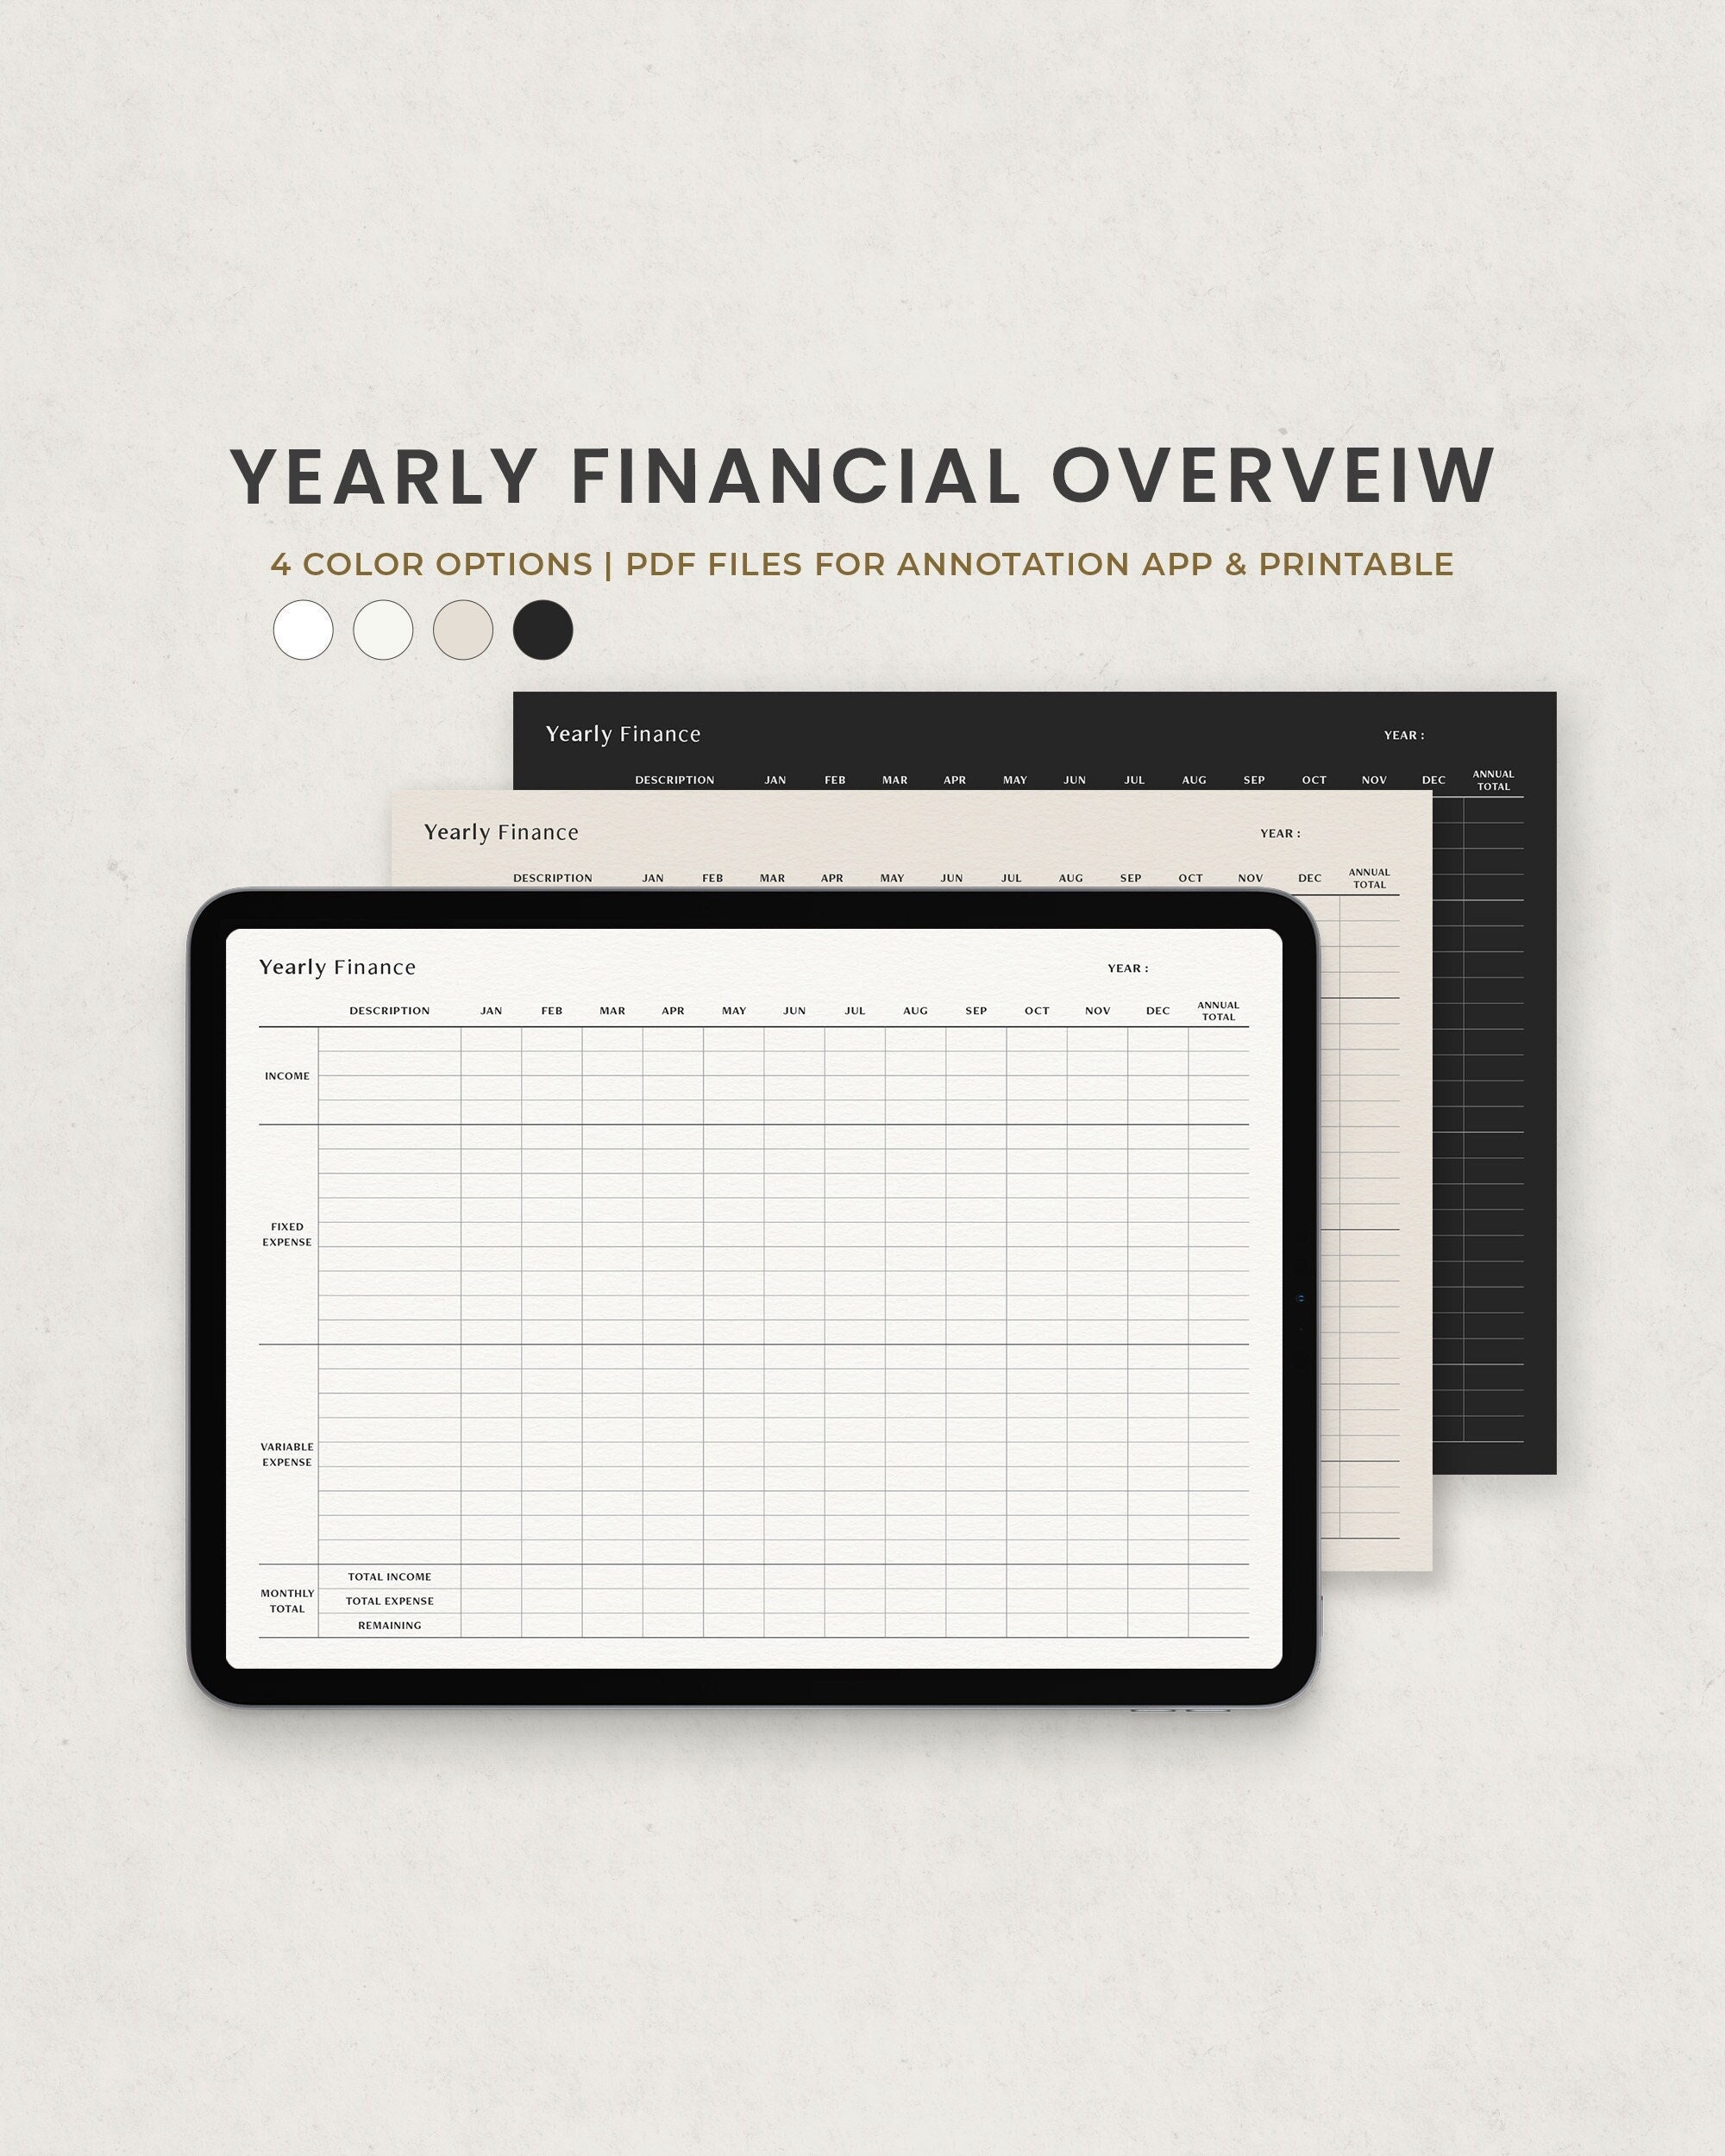
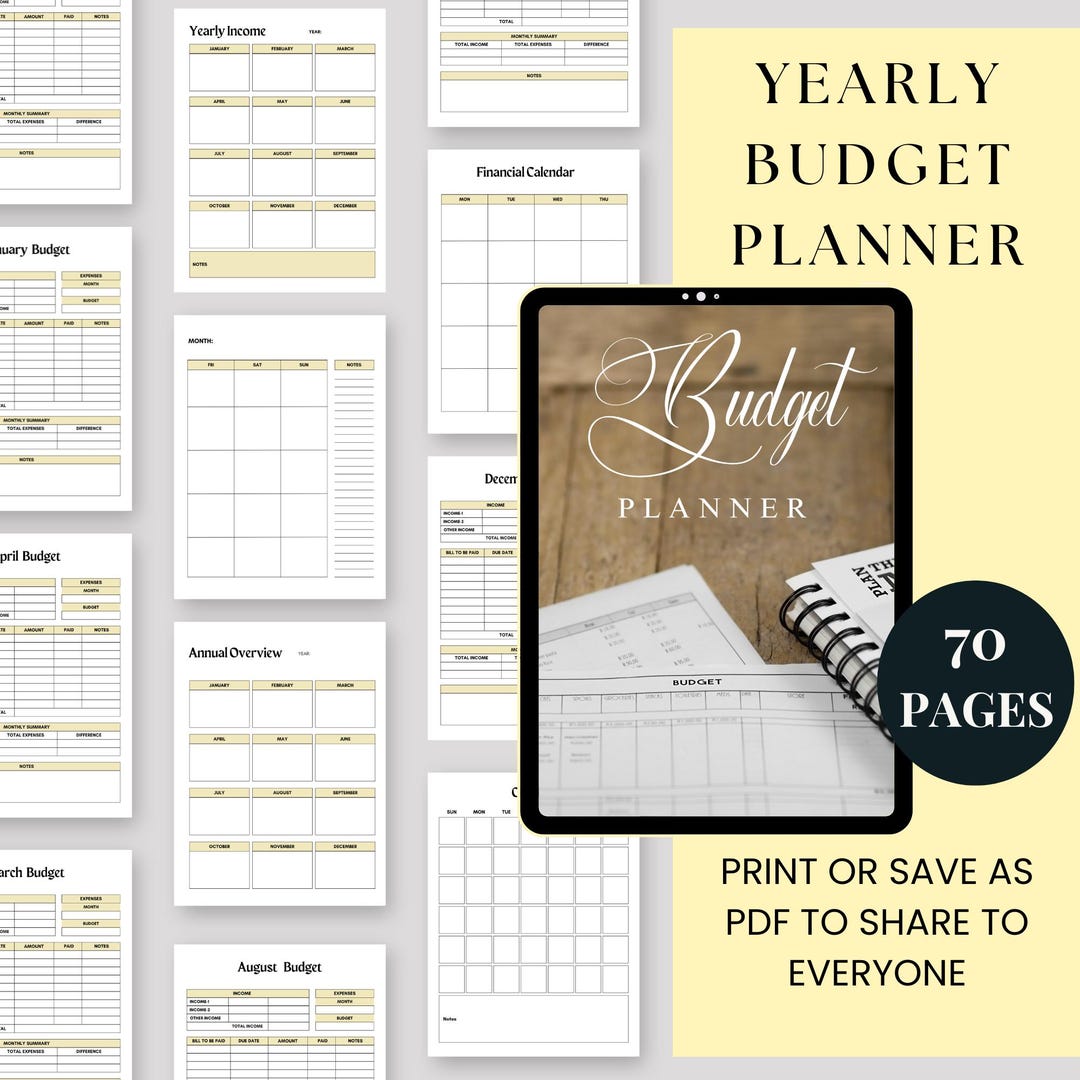
You can build your own from scratch using the structure above, or grab a pre-built template. Here are a couple of reliable options: Google Sheets template: Search "yearly budget planner Google Sheets" in the template gallery. Pick one with twelve month columns and rolling balances. Avoid anything with more than five sheets or fancy macros — you don't need them and they'll break when you share or move files around. Excel version: Microsoft's built-in budget templates under File > New > Budget work fine for this purpose. Download one, strip out the sections you don't use, and rebuild it using the row structure I outlined above. Takes about twenty minutes.
I keep mine in a dedicated folder with the previous year's version archived. Naming convention is simple: Economics Planner 2025, Economics Planner 2024, etc. You'll thank yourself later when you're comparing year-over-year data.
Where This Falls Apart
Yearly economics planners have real limitations. They don't work well for irregular income streams unless you build in weekly or biweekly tracking instead of monthly. Freelancers and commission-based workers often find themselves three months into the year with projections that look nothing like reality because the income pattern is sporadic. They also fail when you have multiple revenue streams with different seasonality. A business that makes money in Q4 but operates year-round needs more granular tracking than a standard twelve-month grid provides. In those cases, quarterly planning with monthly checkpoints works better. And honestly, if you're already using accounting software like QuickBooks or Xero, the manual planner is redundant for basic tracking. The software does the heavy lifting. A separate planner only adds value if you're doing forward-looking projections that your accounting system doesn't handle natively. Otherwise you're maintaining two systems and neither gets proper attention.
The bottom line is this: build something simple, update it monthly, and accept that your projections will drift from reality. The planner's job isn't to predict the future perfectly. It's to make sure you notice when things go off track early enough to do something about it.