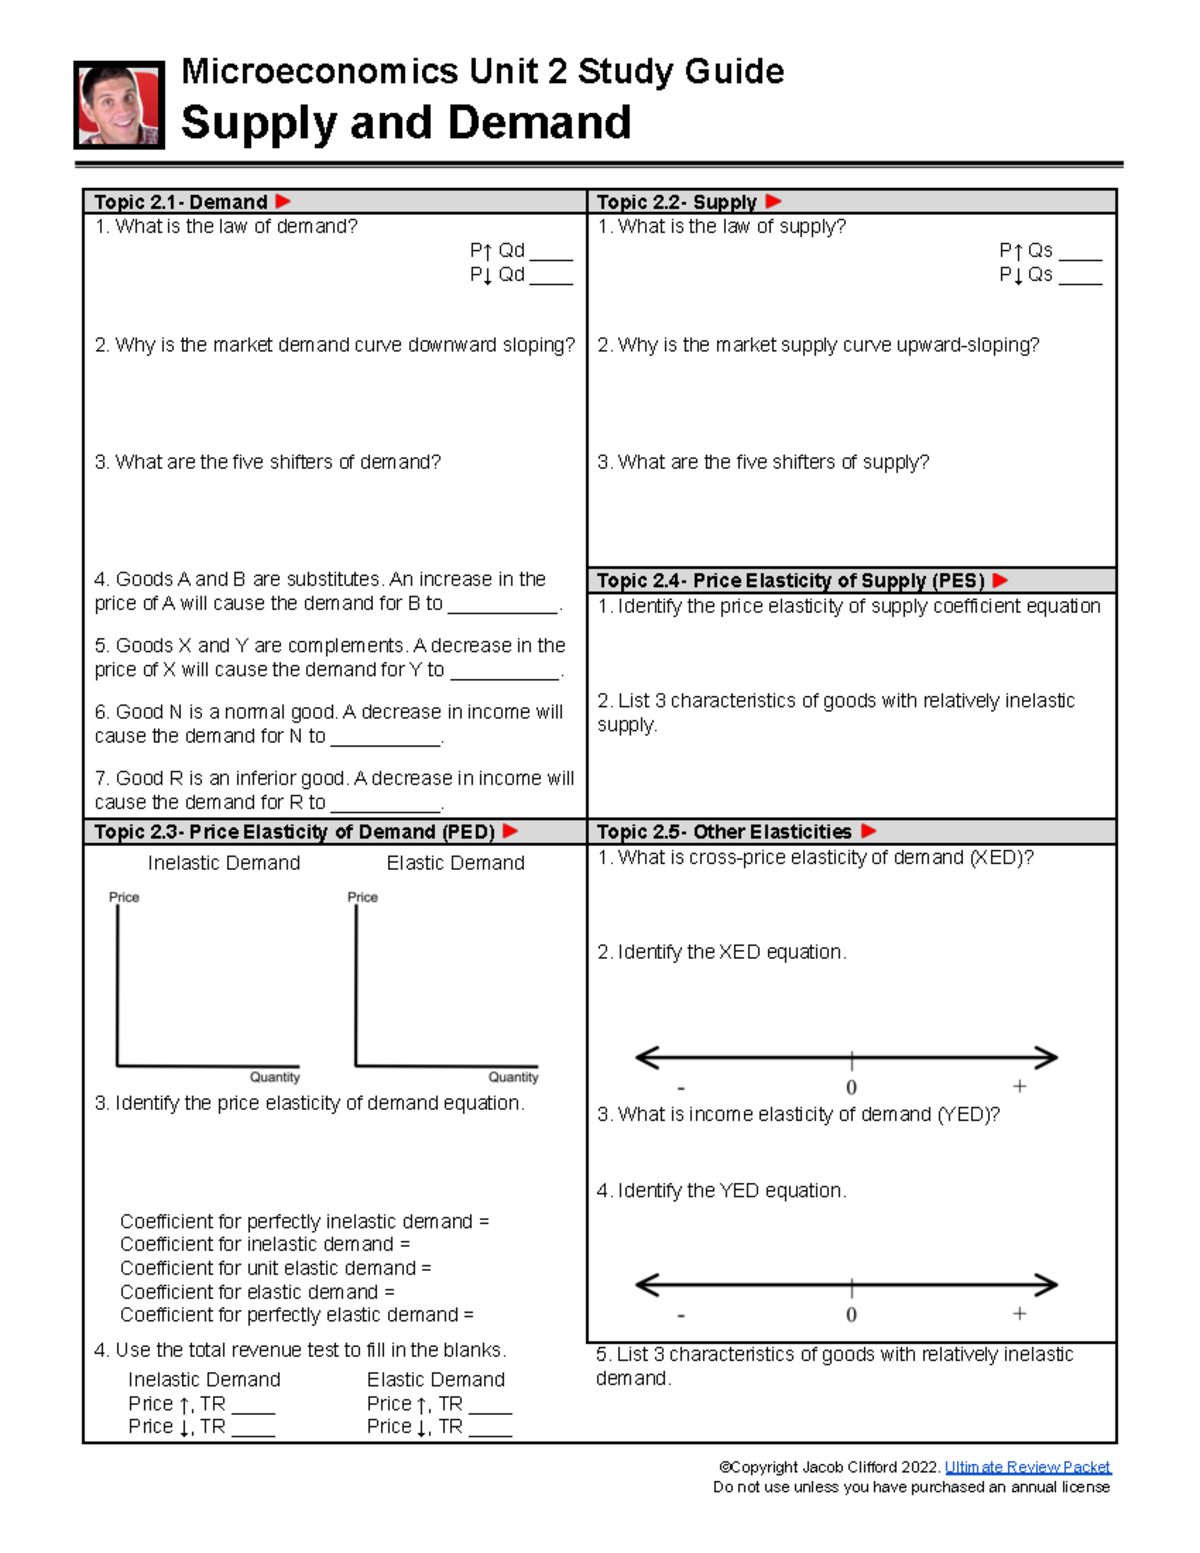
Unit 2 usually covers supply and demand, market equilibrium, and elasticity. It is one of those units where the concepts build on each other, so if you fell behind early, everything after gets harder. I have seen students struggle with this not because the math is hard, but because they do not connect the graphs to the actual behavior.
Working With Economics Unit 2 Study Guide Answers
When you are going through a study guide, the first thing to do is separate the definitions from the application. Most guides will give you terms like normal good, inferior good, price ceiling, and price floor. Those are straightforward. The part that trips people up is applying them to graph questions where multiple shifts happen at once.
I remember working with a student who kept getting demand curve questions wrong because she would shift the curve in the wrong direction when income changed. She thought higher income always meant higher demand, which is only true for normal goods. Once we went through a list of examples and categorized them, she stopped making that mistake. That is the kind of thing that matters more than memorizing definitions.
Let us talk about elasticity. Price elasticity of demand measures how responsive quantity demanded is to a change in price. The formula is percentage change in quantity divided by percentage change in price. If the result is less than one, demand is inelastic. Greater than one means elastic. Equal to one is unit elastic. This sounds simple, but the problem is knowing what affects elasticity in real life.
Things that make demand more elastic include having close substitutes, being a luxury rather than a necessity, and having a longer time period to adjust. Gasoline is a classic example of inelastic demand in the short run. People need to drive to work regardless of the price. Over a longer period, they might move closer to work or buy a more fuel efficient car, which makes demand more elastic over time.
Revenue management is another area where students lose points. When demand is elastic, lowering price increases total revenue. When demand is inelastic, lowering price decreases total revenue. This is because the percentage change in quantity demanded is larger than the percentage change in price when demand is elastic. The math checks out, but it is easy to mix up which way revenue moves.
Market equilibrium happens where supply and demand intersect. A price ceiling set below equilibrium creates a shortage because quantity demanded exceeds quantity supplied. A price floor set above equilibrium creates a surplus. Rent control is a common example of a price ceiling. Minimum wage laws are an example of a price floor. Both have debate around them, but the basic economics is clear.
Government intervention introduces taxes and subsidies. A tax on a good shifts the supply curve to the left, raising the price and lowering the quantity traded. The burden of the tax is shared between buyers and sellers depending on the relative elasticities. The more inelastic side bears more of the tax burden. This is counter-intuitive for some students who think the tax falls entirely on the seller.
Here is a practical edge case I encountered. A student was working on a problem where both supply and demand shifted at the same time. Supply decreased while demand increased. The equilibrium price definitely rose, but the equilibrium quantity could go either way depending on the magnitude of each shift. The study guide answer just stated the new equilibrium without explaining why quantity was indeterminate. I showed him how to draw it out with different magnitudes, and he finally understood why some questions leave quantity ambiguous.
Another area where people struggle is with cross-price elasticity. If two goods are substitutes, the cross-price elasticity is positive. If they are complements, it is negative. The classic example is peanut butter and jelly. If the price of jelly goes up, demand for peanut butter goes down. That negative relationship is what tells you they are complements.
When you are doing practice problems, start with the graph. Draw the initial supply and demand curves. Mark the equilibrium. Then apply the change step by step. If it is a change in consumer income, shift demand. If it is a change in input costs, shift supply. Do not try to do it all in your head. I have found that slowing down and drawing each shift separately cuts errors by about half.
For exam preparation, make sure you can explain the difference between a change in quantity demanded and a change in demand. A movement along the curve is caused by a price change. A shift of the entire curve is caused by something else like income, tastes, or prices of related goods. This distinction comes up constantly.
If you are stuck on a particular concept, try teaching it to someone else. Explaining elasticity to a peer forces you to organize your thoughts and spot gaps in your understanding. It also takes about ten minutes and works better than re-reading the textbook a third time.
Some study guides oversimplify things. They present elasticity as a fixed number when in reality it varies along a linear demand curve. The midpoint method gives you a more accurate measure, but even that is an approximation. Being aware of these limitations helps you answer trick questions that professors like to include.
The most important thing is to practice with graphs. Every concept in this unit can be shown visually. If you can draw the graph and explain what happened, you understand the material. Memorizing formulas without the visual context is a recipe for forgetting everything by test day.
Gallery Economics Unit 2 Study Guide Answers
Micro Unit 2 Study Guide | PDF | Demand | Elasticity (Economics)
Economics Study Guide Unit 2: Market Economies at Work: Supply & Demand ...
Unit 2 Study Guide Answers | PDF
Unit 2- Economics study guide - Busch Economics Kyliegh Rolls Remember ...
Unit 2 Study Guide Blank - Microeconomics Unit 2 Study Guide Supply and ...