How to Actually Build an Editable Bank Statement Template That Doesn't Fall Apart
Most people I see asking about this are trying to fabricate something, and that's not what this is about. What an editable bank statement template actually is in legitimate practice is a structured spreadsheet format you use when you need to reconcile records against what your bank provides, or when you're preparing documentation for a loan application and need to organize raw transaction data before submitting it. Banks don't accept raw spreadsheet dumps—they want their own PDFs. But internal financial tracking is a different thing entirely.
I spent three years doing accounts payable for a mid-size logistics firm, and we used custom bank statement templates weekly to match vendor payments against clearing transactions. The version that finally worked wasn't fancy. It was a Google Sheet with hardcoded columns that mirrored what Chase and Wells Fargo actually sent out. Here's how you build one that won't break on you.
Building Your Editable Bank Statement Template
Start with a blank spreadsheet. Set up these columns at minimum: Date, Transaction Description, Debit Amount, Credit Amount, Running Balance, Reference Number, and Category. Do not merge cells. Do not use color coding for data entry. I learned this the hard way when our accounting software export broke because someone had merged every other cell for "presentation." When the month-end script ran, it skipped half the rows and the balance reconciled to within eight cents of being wrong instead of zero. Took me four hours to find.
The trick nobody tells you about bank statement templates is that banks structure their statements in ways that don't map cleanly to a grid. My main gripe was with the date format. Chase uses MM/DD/YYYY but their CSV exports sometimes return dates as text strings in DD-MMM-YYYY format depending on which menu option you pick to download. If your template doesn't account for that, your date column turns into garbage and every formula downstream breaks. The fix was putting a helper column right next to the date import that runs a TEXT() conversion—=TEXT(A2,"MM/DD/YYYY")—and then referencing that helper column in all your formulas instead of the raw import cell. Took ten seconds to set up and saved me from rewriting the entire sheet every quarter when a bank changed their export format.
For the running balance calculation, don't rely on SUM formulas that reference the whole column. Use =B2+C2-D2 and drag it down only as far as your actual data goes. If you use =SUM() across a 1000-row range and you're only working with 47 transactions, every empty row adds up as zero and your total shows fine, but then someone pastes data below your working range and suddenly your "balance" includes phantom entries. Keep the range tight.
Here's what most beginners miss: credit and debit columns. Some banks report debits as positive numbers and credits as negative, others do the opposite, and a few list everything as positive with a separate "Type" column that says CR or DR. If you're pulling data from multiple banks into one template, normalize it immediately in the first step. I keep a master reference sheet that maps each bank's output format to the standard layout, then use INDEX/MATCH to auto-convert. Takes about two minutes per bank setup and eliminates the most common reconciliation error I see people making.
Practical use cases that actually justify building one:
- Reconciling personal finances where your bank's app doesn't categorize things properly and you need a clean view
- Preparing documentation for a mortgage or small business loan where the underwriter asks for six months of organized statements and your bank's PDF export is messy or missing transaction details
- Cross-referencing multiple accounts (checking, savings, investment) in one place before filing quarterly taxes
- Tracking cash flow for a side business where you don't want to pay for QuickBooks but need something better than a phone banking app
The downloadable template structure is straightforward. You can find ready-made versions on spreadsheet marketplaces, but most of them are overbuilt with conditional formatting and macros that break when you open them in a different program. I keep a bare-bones version on my Google Drive that I share with anyone who asks. It's just the columns I listed, a couple of validation rules to prevent entering text in amount fields, and a data validation dropdown for categories. Nothing fancy.
When I share mine, people always ask about the automated reconciliation feature. I don't build that into my personal template because it creates a false sense of accuracy. What I do instead is a manual match step where I flag cleared transactions with a checkmark column. It takes about twelve minutes for a typical month of personal transactions, versus the twenty minutes I'd spend debugging a semi-auto reconcile that inevitably misses edge cases.
Here's a realistic scenario where the template approach completely fails: if your bank statement contains recurring subscriptions that change amount or date unpredictably, or foreign currency transactions, or wire transfers with reference numbers that don't follow a pattern. In those cases, the spreadsheet model becomes a guessing game. The workaround is to export the raw bank data and use a tool like Plaid's dashboard or even a basic Python script to parse and categorize before importing into your template. For most individuals that's overkill though.
A few things your template should not have:
- Pre-filled transaction data. Start empty every month. Carrying over data creates ghosts where old transactions linger and mess up your count.
- Hardcoded month names or year references in formulas. Use DATE() functions or reference a single input cell for the period you're tracking.
- Complex VLOOKUPs for transaction categorization during data entry. It slows you down and introduces error points. Type the category in, organize later.
- Password protection that locks editing. You'll lose access during an audit or when someone else needs to verify the numbers quickly.
The honest downside is that maintaining a manual template takes consistent effort. If you let it go for three months, catching up feels worse than just accepting the discomfort and doing it. I've seen people abandon templates after one frustrating month and switch back to whatever disorganized system they had before. The ones who keep using it for more than six months usually cite the tax season benefit as the main reason—it cuts statement preparation time from several hours to under forty-five minutes because everything is already categorized and indexed.
Another counter-intuitive thing: you don't need to import the full statement every single time. If you're just tracking a specific period, pulling the last 30 to 90 days is often enough. Full six-month imports create file bloat and slow down the spreadsheet significantly, especially if you start adding charts and summary tables. Keep the working sheet lean and archive older data in a separate file.
If you're building this for business use and your volume is above a certain threshold, the template stops being worth it. At around 200 transactions a month across multiple accounts, you're better off with actual accounting software. The template excels in the low-to-mid volume range where the overhead of setting up a full system isn't justified but spreadsheets alone aren't organized enough.
The bottom line is that an editable bank statement template is a compromise between having nothing structured and spending money on software you'll barely use. It works when you respect its limitations, break when you try to make it do too much, and requires the same disciplined maintenance habit that any financial tracking system does. I've been maintaining the same personal version since 2019 with minor adjustments. It's boring and it works.
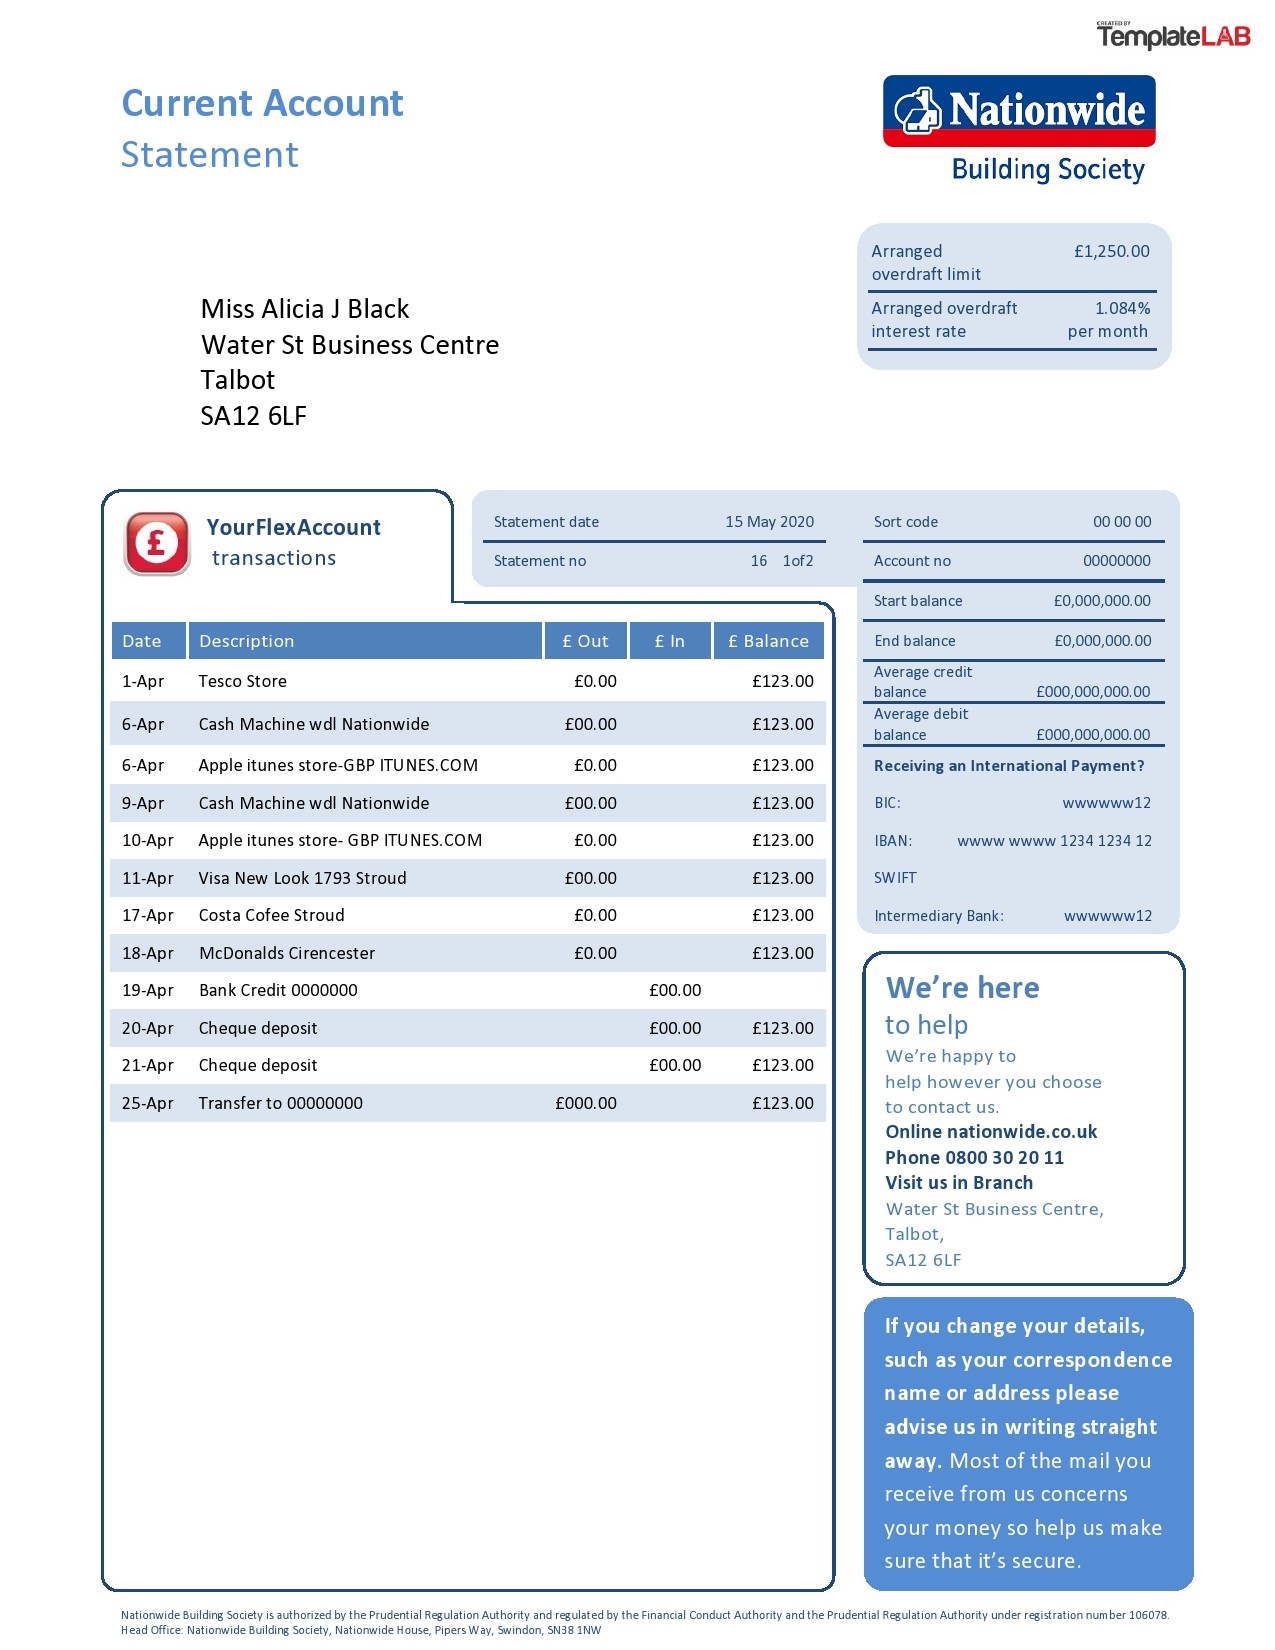
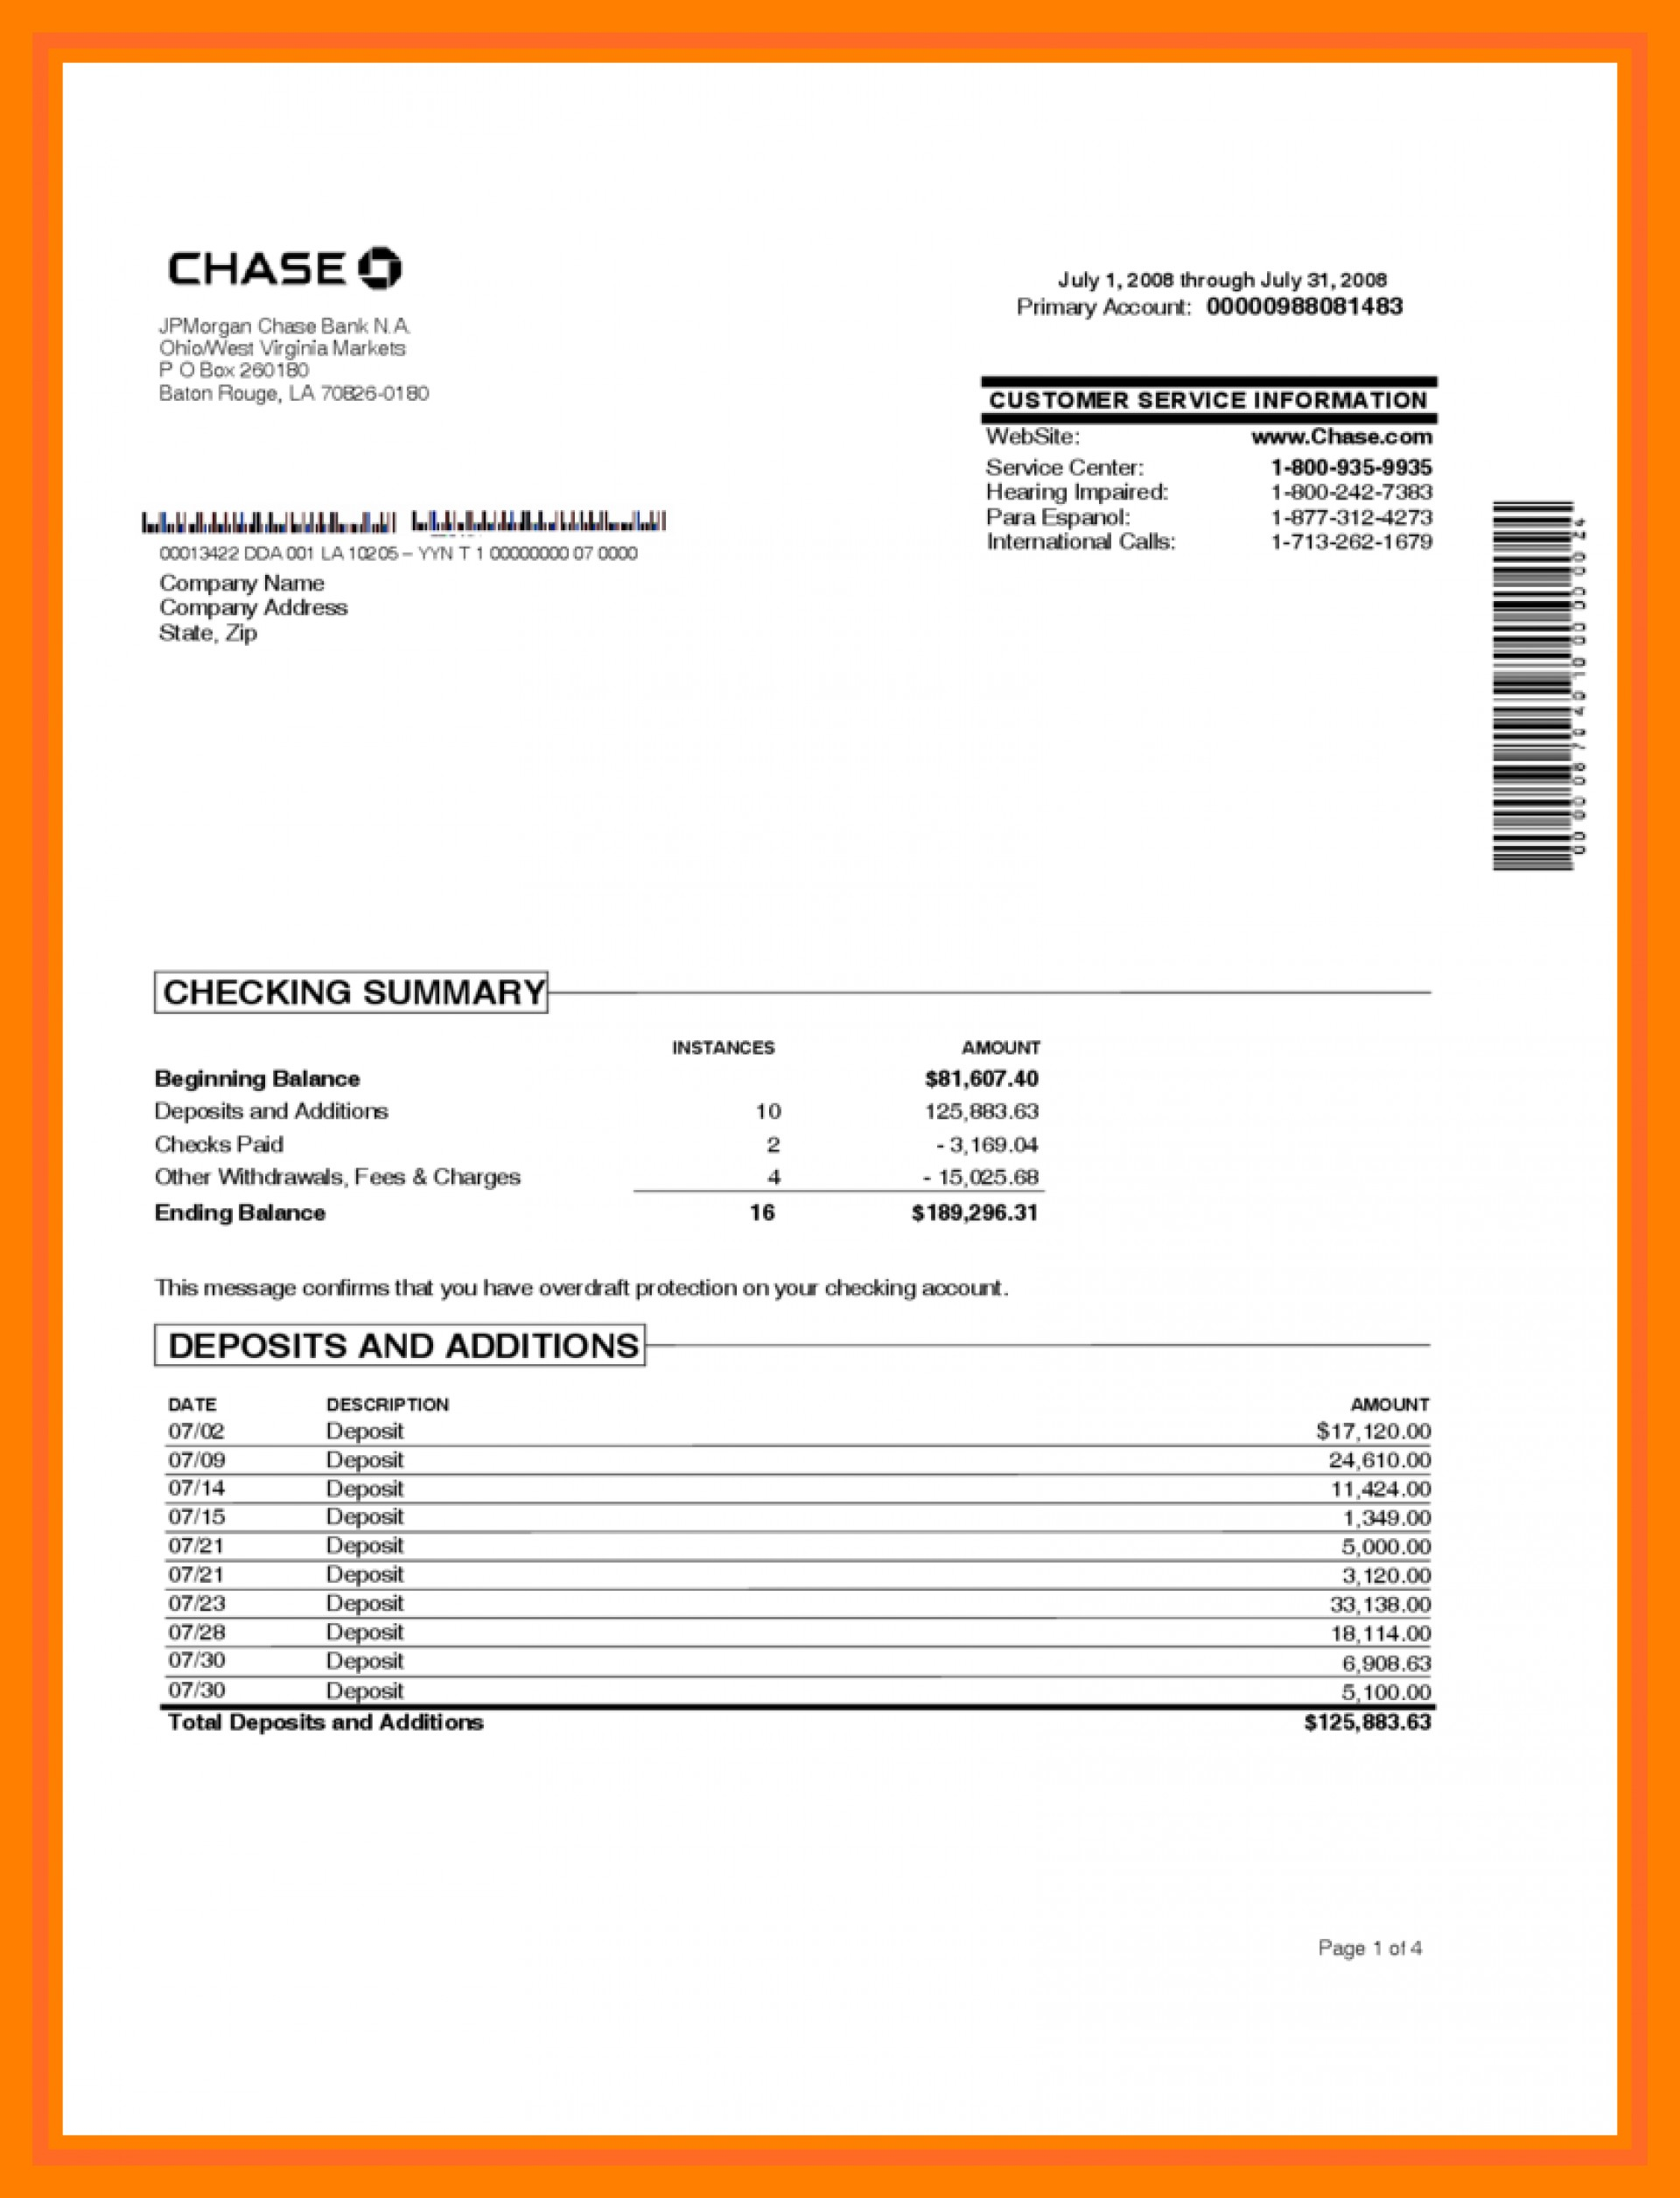
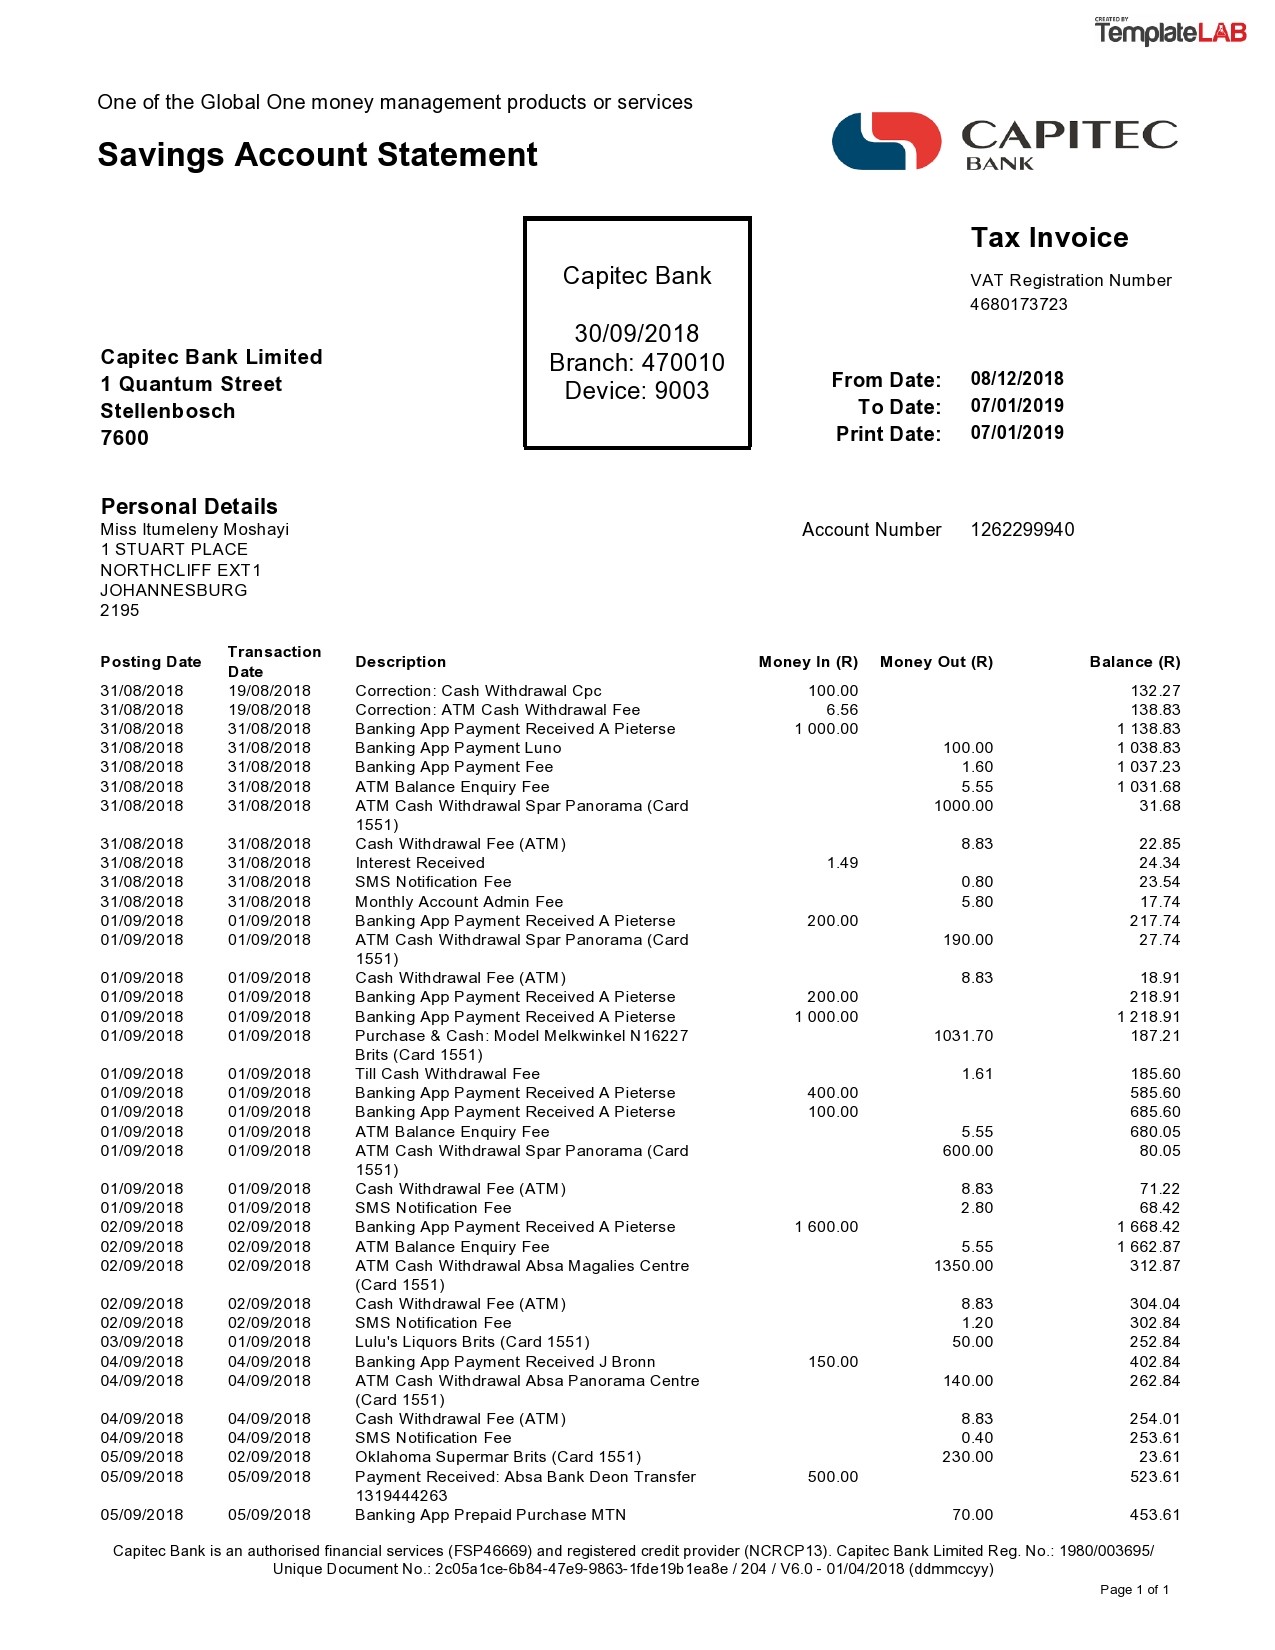
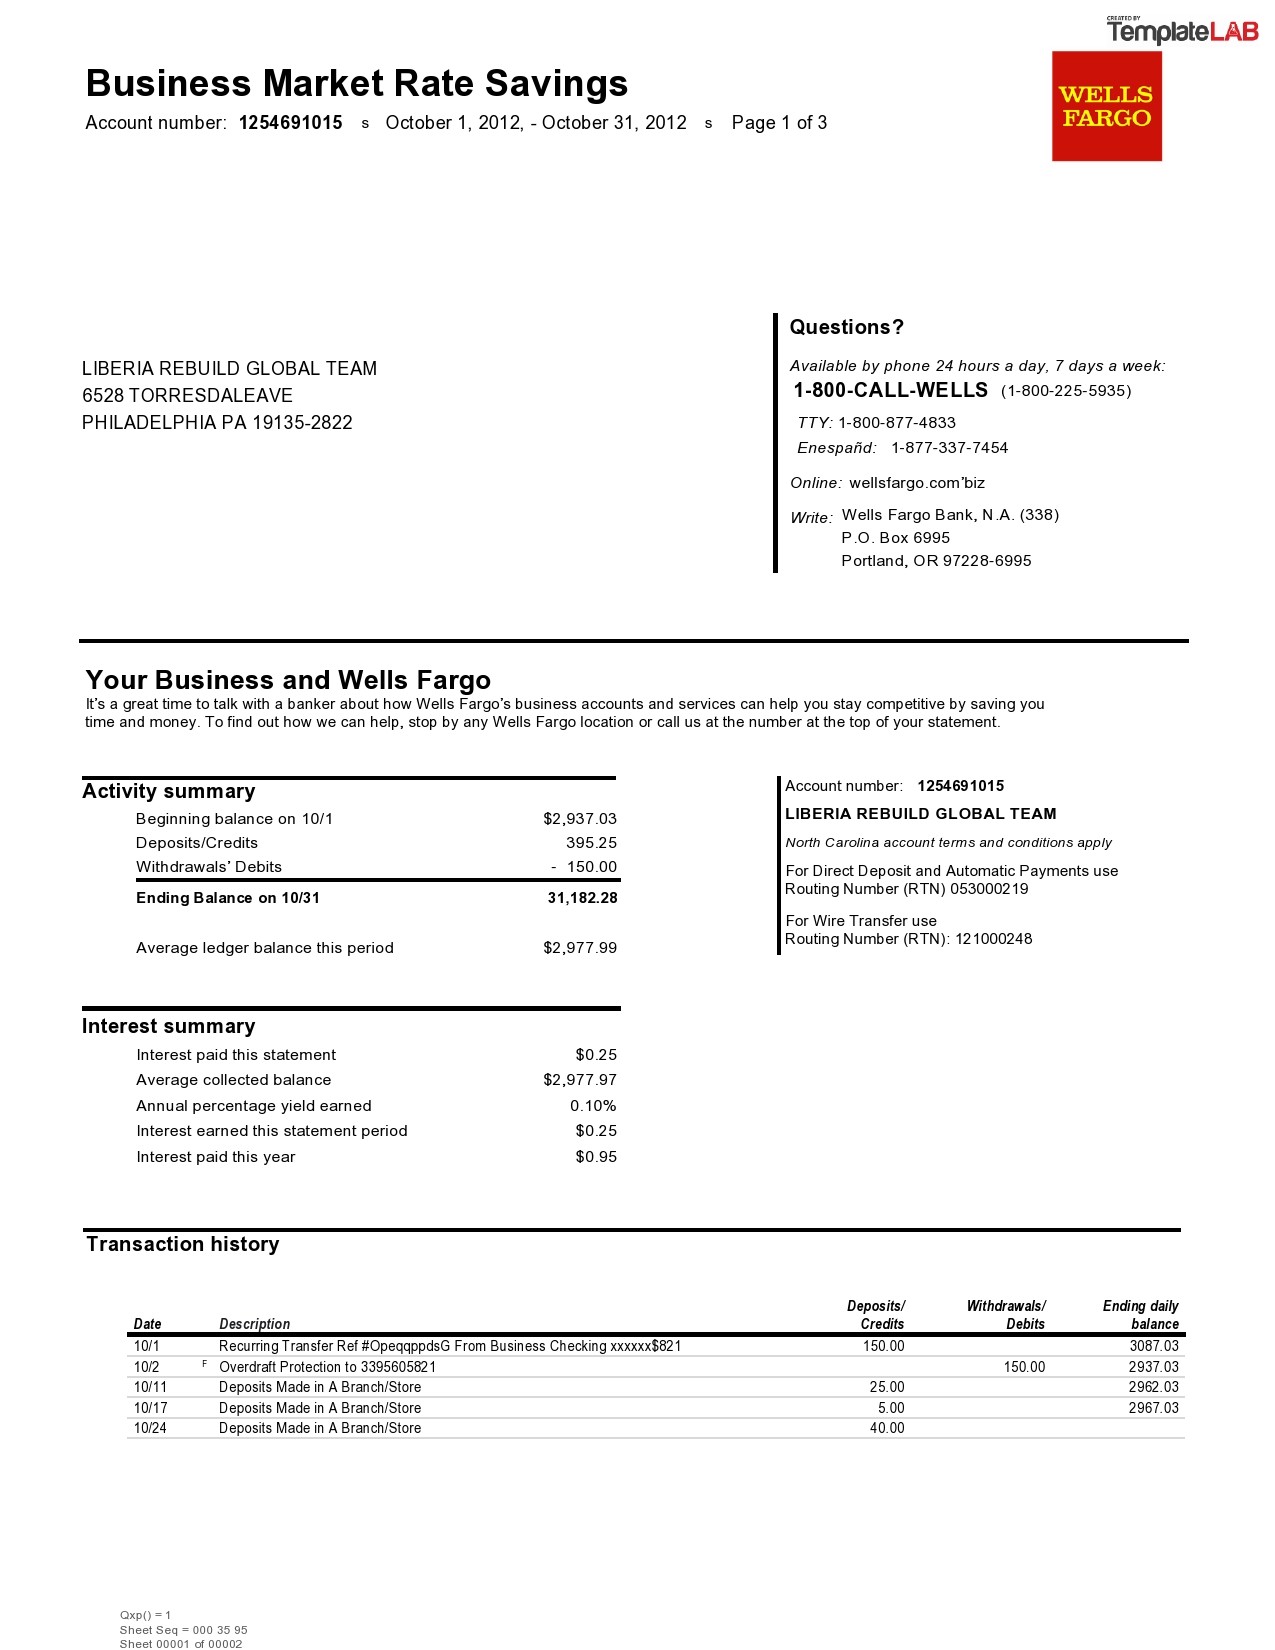
Gallery Editable Bank Statement Template
Editable Bank Statement Template
Editable Bank Statement Template
Editable Bank Statement Template
35 Editable Bank Statement Templates [FREE] ᐅ TemplateLab
35 Editable Bank Statement Templates [FREE] ᐅ TemplateLab