Understanding the EIC Worksheet B Process
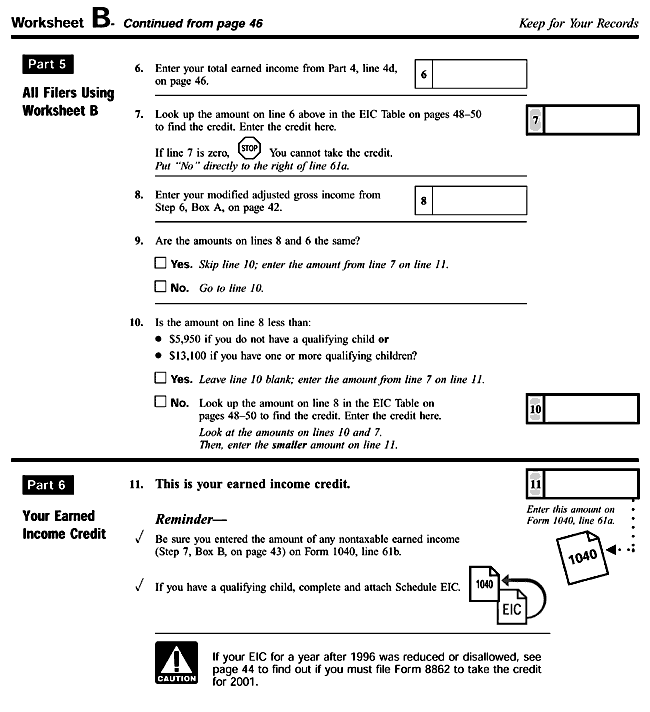
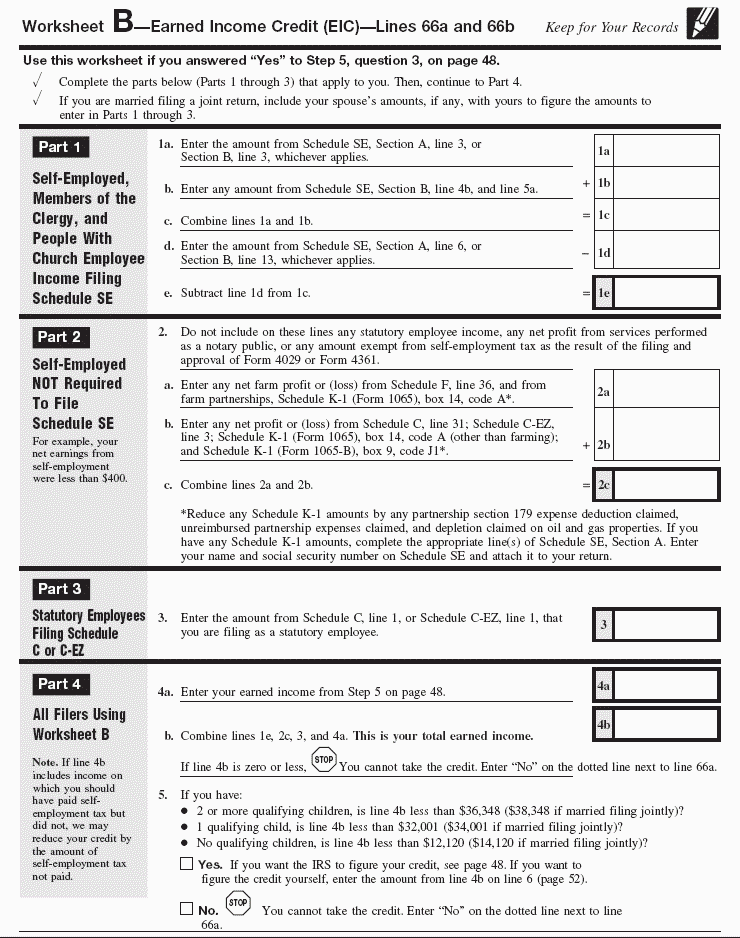
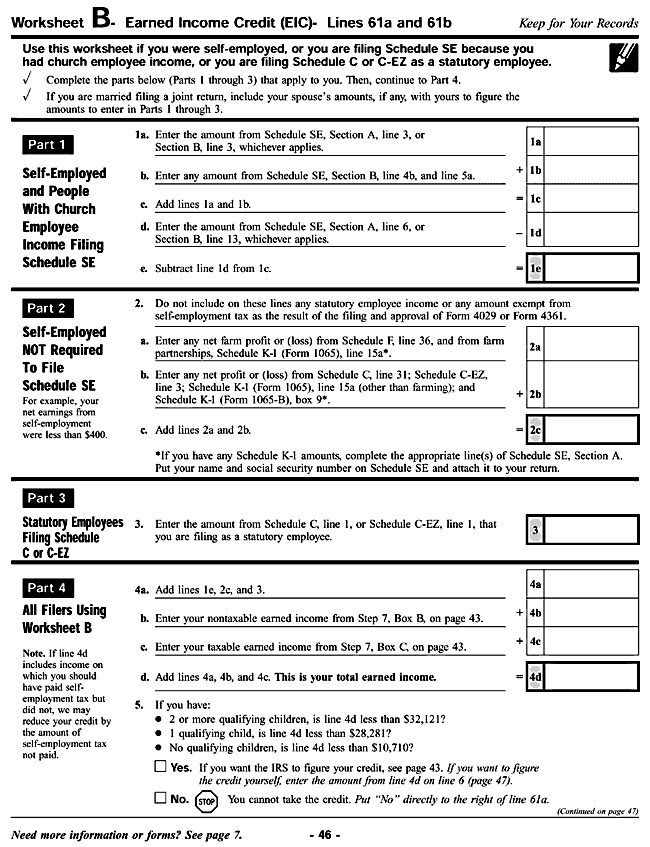
The Earned Income Credit Worksheet B is a supporting document that appears alongside IRS Form 1040 when you're filing taxes and want to claim the EIC. It's not the main form itself. It's a supplemental calculation sheet. For the 2021 tax year, the worksheet became notably more relevant because the American Rescue Plan Act temporarily expanded the credit to include childless workers without dependents, which was a significant departure from how the credit had operated for decades. Worksheet B is used when your filing situation falls outside the simplest scenario. If you're filing single, have no qualifying children, and your income is below a certain threshold, the worksheet guides you through determining whether you qualify and how much credit you're entitled to receive. The IRS published the 2021 version with updated income limits that reflected the temporary expansion. Childless filers could now qualify with earned income between $8,500 and $21,430 (for single filers in 2021), which was completely new territory for a lot of people. Here's how the worksheet actually works in practice. Line 1 asks for your adjusted gross income from line 11 of your Form 1040. Line 2 asks if you're a qualifying child's parent or have a disability. Most childless filers answer no. Lines 3 through 5 walk you through income thresholds based on filing status. If your income is below the stated limit, you move forward. The worksheet then has you reference the EIC Tax Table in the instruction booklet, where you look up your exact credit amount based on AGI and filing status. That lookup step is where most people trip up, and it's worth doing carefully.
When You'd Actually Need It
The worksheet applies when you do not have a qualifying child who lived with you for more than half the year. That's the primary differentiator between Worksheet A and Worksheet B. Worksheet A is the simpler version designed for taxpayers with at least one qualifying child. Worksheet B is for everyone else: childless filers, those whose income falls into a more complex range, or people with certain types of earned income that require additional verification. In 2021, the temporary expansion meant that an estimated 27 million additional workers who previously did not qualify for any EIC benefit suddenly had to fill out Worksheet B. That's a massive population that had no prior experience navigating this part of the tax code. Many of them had never even heard of the EIC before 2021.
The Step-by-Step Walkthrough
Start by locating the 2021 EIC Worksheet B in your Form 1040 instructions package. It should be included at the end of the PDF or on paper if you received a physical copy. Have your completed Form 1040 ready with line 11 filled in, since that feeds directly into line 1 of the worksheet. Answer the question on line 2 honestly. If you do not have a qualifying child living with you and you are not disabled, select no. This is correct for the majority of childless EIC claimants. Moving to line 3, compare your AGI from line 1 against the threshold for your filing status. For single filers in 2021, the threshold was $21,430. If your AGI is below that amount, proceed. If it's above, you do not qualify for the credit and the worksheet stops there. No need to continue. Lines 4 and 5 involve checking your investment income. For 2021, if your investment income exceeded $10,300, you are disqualified entirely from the EIC regardless of your earned income. This is a hard cutoff and it's non-negotiable. If your investment income is below that threshold, you proceed to line 6, where you enter your earned income from line 1 of the worksheet. This is typically your wages, salaries, or self-employment income after adjustments.
Get the Full Details

Once you have your earned income entered, you cross-reference it with the EIC Tax Table found in the instruction booklet. Find the row that matches your income and your filing status, then read across to get your credit amount. Write that number on the designated line of the worksheet. If your income falls between two table entries, use the lower income amount to calculate the credit. The worksheet then asks you to compare your calculated credit against another figure on line 13, which is derived from a separate calculation. Take the smaller of the two amounts and enter it as your final EIC. Transfer that number to line 27b of your Form 1040.
A Real Problem I Ran Into
I once worked with a client who had multiple sources of income in 2021: a W-2 from a part-time job, freelance income reported on a 1099-NEC, and a small amount of interest from a savings account. When she filled out Worksheet B, she initially entered only her W-2 wages as earned income and ignored the self-employment income. The worksheet's line 6 clearly says "earned income," which includes both wages and net earnings from self-employment after Schedule SE, but this detail is easy to miss if you're filling it out for the first time. Her error understated her earned income, which pushed her into a lower bracket in the EIC table and resulted in a smaller credit than she was entitled to. The fix was straightforward once identified. She recalculated her net earnings from self-employment on Schedule SE, added that to her W-2 wages, and re-ran the worksheet. The corrected credit was about $800 higher. It took maybe ten minutes total to identify and correct, but it required actually understanding what "earned income" means in the context of the EIC rather than just assuming it meant salary and wages.
Common Pitfalls to Avoid
One counter-intuitive issue that catches people off guard involves the interaction between the EIC and the additionalChild Tax Credit. If you have qualifying children and you're filling out Worksheet A rather than Worksheet B, you can potentially claim both credits on the same return. But Worksheet B filers do not have qualifying children, so this is purely a consideration for those using Worksheet A. Still, it's worth noting because tax software sometimes conflates the two worksheets in ways that can produce incorrect results. Another frequent problem is the timing of the 2021 tax year itself. The COVID-era EIC expansion was only in effect for the 2021 tax year. If you had filed using 2020 rules and then tried to apply the same logic to 2021, or vice versa, you would get the income thresholds wrong. The 2021 thresholds were distinctly higher than prior years due to the temporary legislative changes. Using outdated tables from a previous year's instructions will give you an incorrect answer every time. A third issue is the investment income ceiling. People often think that interest from a savings account or a certificate of deposit is trivial and won't matter. But the $10,300 threshold for 2021 is total investment income, including taxable and tax-exempt interest, dividends, capital gain distributions, and passive income. If you've been quietly accumulating savings and haven't thought about investment income in years, this line can unexpectedly disqualify you from the credit entirely. I've seen this happen more often than you'd expect.
Where to Get the Actual Form
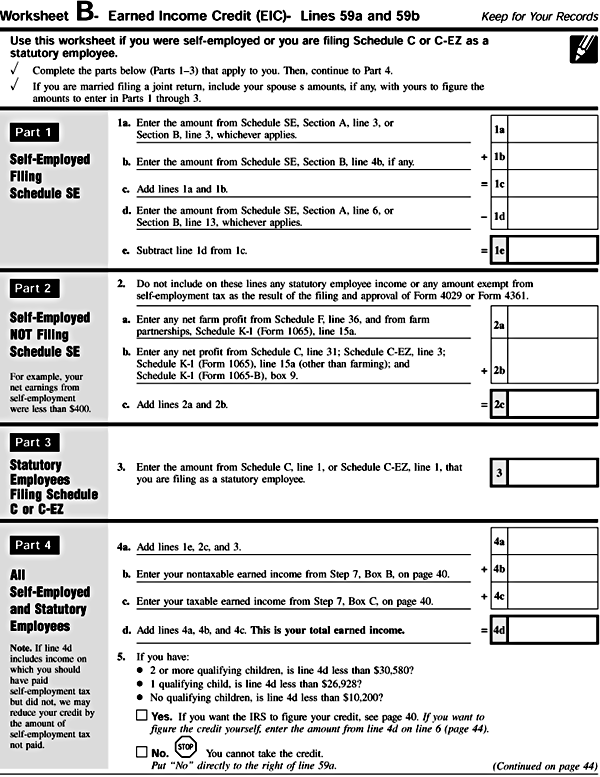
The official 2021 EIC Worksheet B is available directly from the IRS website at irs.gov. Navigate to the forms and instructions section and search for "2021 Form 1040 instructions." The worksheet is included as part of the full instruction package, not as a standalone form. You do not mail Worksheet B separately. You fill it out for your records, transfer the final credit amount to your Form 1040, and keep the worksheet attached to your tax return if you're filing on paper. If you're using tax preparation software, the program should automatically pull the correct 2021 worksheet and guide you through it. This is generally the safer route because the software handles the table lookup internally and flags discrepancies before you submit. The downside is that you lose visibility into exactly how the number was derived, which makes it harder to catch errors if the software makes one. I've seen software errors where the program used the wrong income threshold for a specific filing status. Having the worksheet on hand lets you verify the output manually if you're suspicious.
What the Worksheet Cannot Do for You
Worksheet B does not calculate your total tax liability. It does not determine your refund amount. It does not address state-level Earned Income Credit filings, which vary significantly by jurisdiction. Several states match their EIC to the federal credit, but others have different eligibility criteria and different calculation methods. If you live in a state like California or Minnesota that offers its own version of the credit, you'll need separate forms and calculations beyond what Worksheet B provides. The worksheet also does not resolve disputes. If the IRS sends you a notice questioning your EIC claim, filling out Worksheet B again will not resolve the issue. You would need to respond to the notice directly, possibly with documentation of your earned income and filing status, and potentially request a conference or appeal through the IRS Small BusinessSelfEmployment Ombudsman or the Taxpayer Advocate Service. There are also scenarios where Worksheet B simply does not apply. If you have a qualifying child who lived with you for more than six months, you use Worksheet A. If your income exceeds the phase-out range for your filing status, you do not qualify regardless of which worksheet you start with. If you are married filing separately, you are categorically ineligible for the EIC and the worksheet is irrelevant to your situation.
The 2021 EIC expansion was a meaningful change that helped a lot of low-wage workers who had previously been excluded. But it was temporary, and the rules around it are precise enough that small mistakes can cost you real money. Working through the worksheet methodically, verifying each line against your actual income documents, and keeping a copy for your records are the only reliable ways to make sure you get the credit you're owed.