The Internal Revenue Service requires every tax professional who claims the Earned Income Tax Credit to complete annual due diligence training. This is not optional guidance, it is a regulatory obligation under Section 6695(g) of the Internal Revenue Code. The penalty for non-compliance is fifty dollars per return where the preparer failed to satisfy the requirements. That adds up fast when you are preparing multiple returns in a single filing season.
Most people think this is just about watching a video and clicking through a quiz. The actual requirements are more involved than that presentation suggests. I spent six years as a VITA site coordinator before moving into private practice, and the difference between preparers who treat this as a checkbox exercise and those who actually understand the material is night and day. The ones who skip ahead make mistakes that cost clients real money.
Eitc Due Diligence Training Requirements
The training must cover three core areas according to IRS Publication 596 and the accompanying due diligence checklist. First, you need to understand eligibility criteria including income thresholds, qualifying child requirements, and filing status restrictions. Second, you must learn how to verify claimant information through documented evidence rather than accepting verbal assertions. Third, the training requires instruction on maintaining records and completing the EITC Due Diligence Checklist (Form 8867 Part III) for every return claiming the credit.
The IRS accepts training from providers who meet their standards. These include the AARP Foundation Tax-Aide curriculum, VITA/TCE certified programs, and various commercial training platforms. The key is ensuring the specific course you select covers the most recent year's income thresholds and dependency rules. I had a preparer on my team once who completed training using 2019 materials and confidently claimed a child qualify based on outdated residency rules. The client lost eighteen hundred dollars in credit because of it. The adjustment happened at audit, and the paperwork to reverse it took another four hours of my time.
What the Training Actually Covers
The eligibility requirements have shifted repeatedly over the past decade, and the training reflects that instability. For tax year 2024, the earned income limit for taxpayers without qualifying children is fourteen thousand eight hundred seventy-five dollars. The maximum adjusted gross income limit is twenty-four thousand three hundred fifty dollars. These numbers change every year, and the training should explicitly address the current year's figures. If a course presents outdated thresholds as current, it is not compliant training.
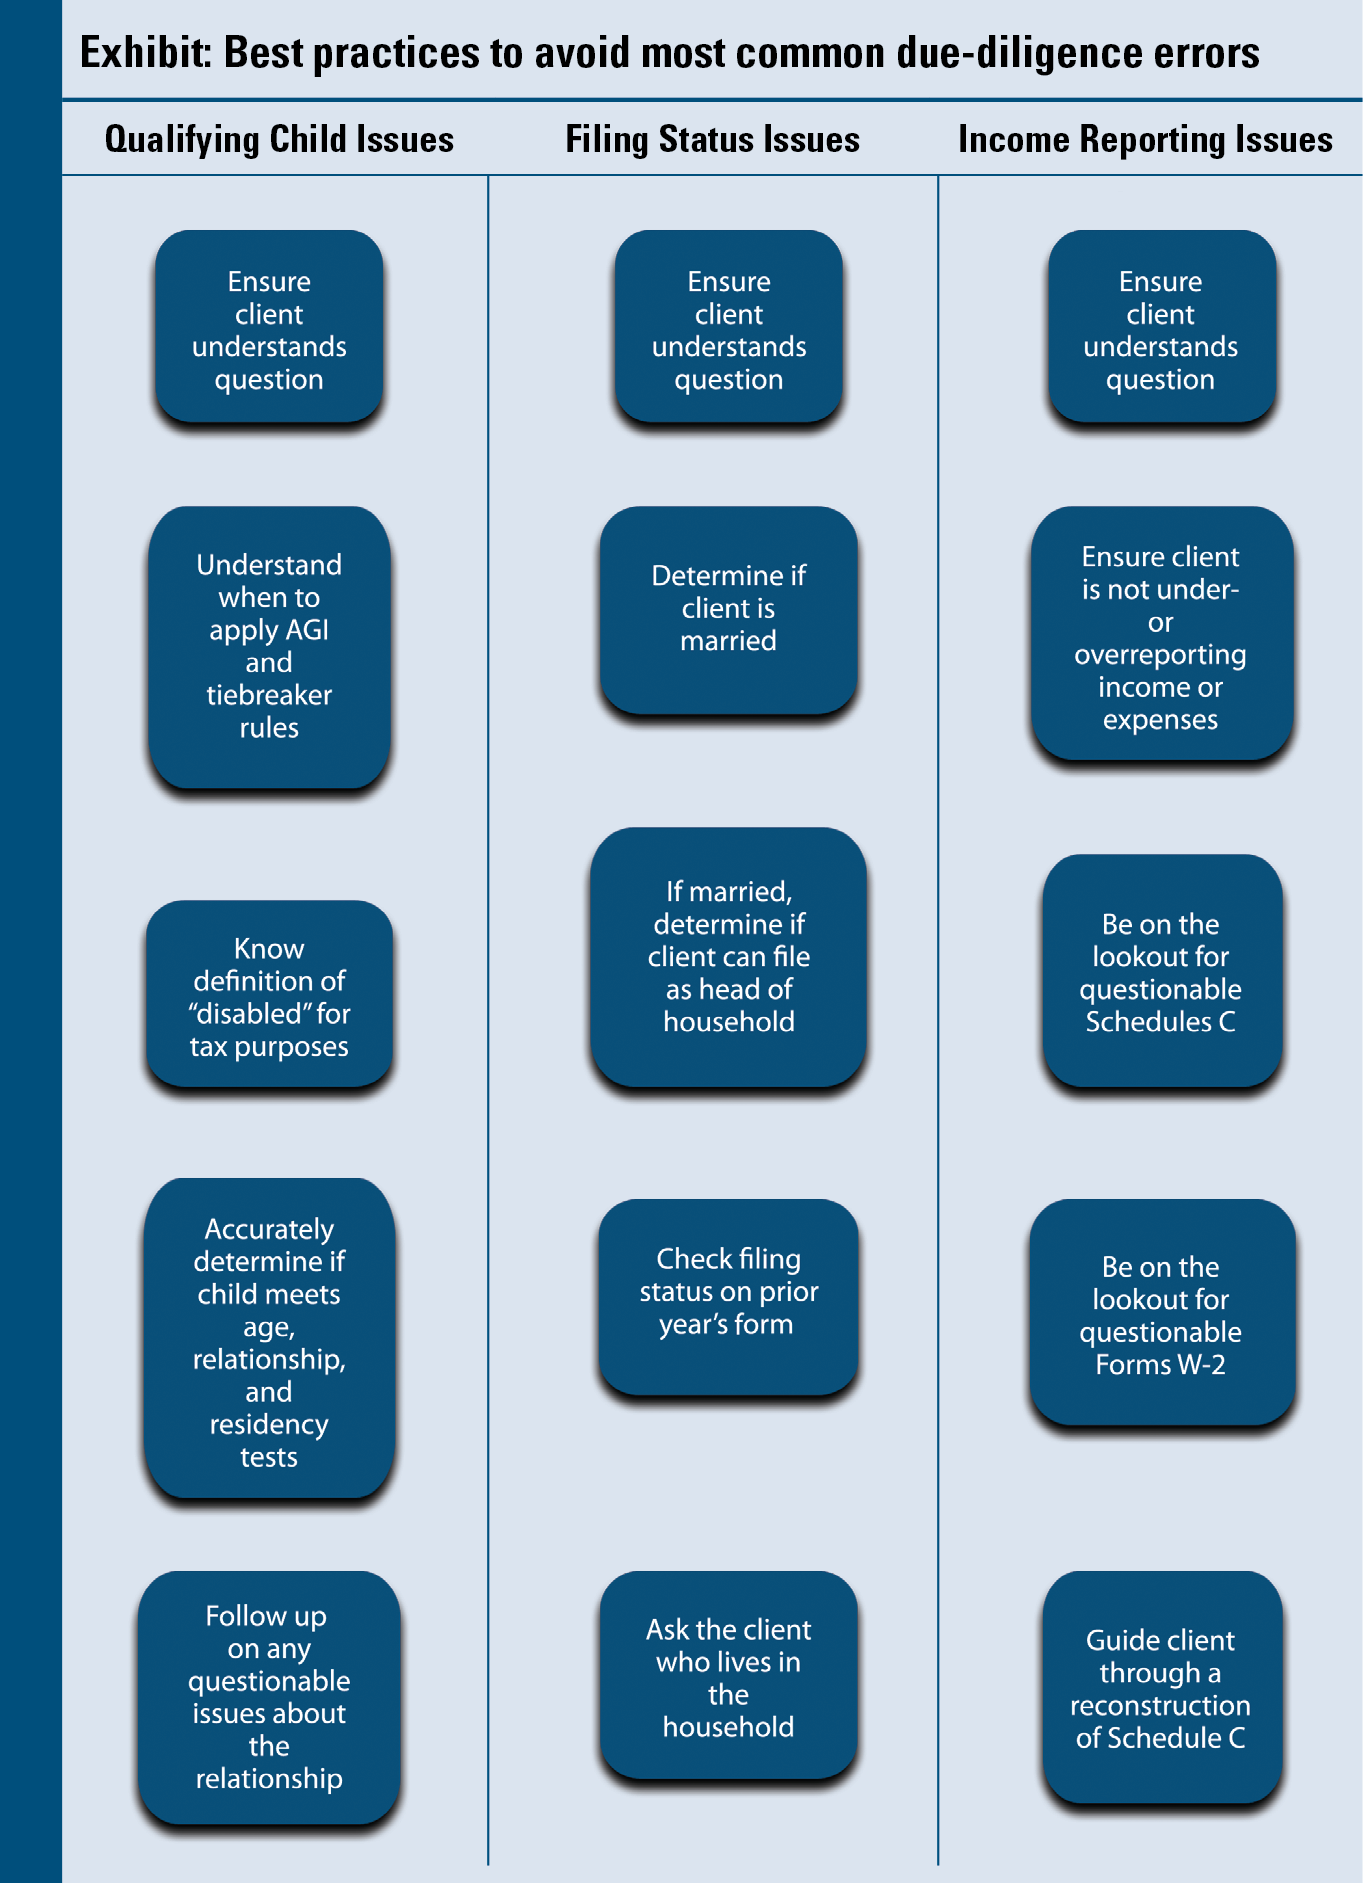
The qualifying child tests are where most errors occur. A child must meet relationship, age, residency, and joint return tests simultaneously. The residency requirement alone trips up preparers who handle families in complex situations. I worked a case where a single mother rotated custody between her parents and herself across two households. The child lived with her for seven months and with his grandmother for five. Under the tie-breaker rules in Pub 972, the parent generally wins over grandparents, but only if the child did not live with the grandparent longer than twelve nights during the year. The documentation review took forty-five minutes because the mother had inconsistent records about where the child stayed on specific dates.
Income verification requires more than looking at a W-2. The training emphasizes examining all sources of earned income including self-employment earnings, tips, and strike benefits. For self-employed individuals, you must review Schedule C and verify that the net profit figure matches the supporting documentation. I encountered a situation where a client reported seven thousand dollars in self-employment income on Schedule C but provided no invoices, bank statements, or expense records. The due diligence process required me to ask for additional documentation, which the client could not produce. We removed the EITC claim entirely rather than file an unsupported position. The client was frustrated but the alternative would have exposed both of us to liability.
Record Keeping Obligations
Preparers must retain the EITC Due Diligence Checklist and supporting documentation for three years after the return filing date or two years after the tax liability is assessed, whichever is later. This means maintaining physical or electronic copies of identity verification, income documentation, and the completed checklist form itself. Many preparers store these digitally, which simplifies retrieval but creates its own complications regarding backup integrity and file format longevity.
The checklist must include the preparer's identifying information, the taxpayer's signature acknowledging the due diligence process, and documentation of how each eligibility requirement was satisfied. I use a standardized file naming convention that includes the tax year, client identifier, and document type. This reduces search time from approximately twenty minutes to under two minutes when responding to an IRS inquiry. Without that system, I have spent entire afternoons locating physical folders in storage.
Common Pitfalls Even Trained Preparers Miss
The dependency tie-breaker rules interact with the EITC in ways that confuse even experienced preparers. When multiple taxpayers claim the same child, the IRS applies specific ordering: first the child's parent, then the child with the highest adjusted gross income, then the parent with the highest AGI, and finally any other claimant. The training covers this hierarchy, but applying it correctly requires understanding that a grandparent with higher income cannot override a parent's claim regardless of who provided more financial support.
Married couples filing separately present another edge case. Neither spouse can claim EITC when married filing separately, regardless of whether they meet all other eligibility requirements. I had a client whose spouse refused to sign a joint return and insisted on separate filing. We explained the EITC disqualification clearly in the consultation, but the client initially refused to accept that outcome. The discussion lasted approximately fifteen minutes before we moved on to other credits the household might qualify for.
When the Training Falls Short
Standard EITC due diligence training covers the baseline requirements adequately but does not prepare preparers for unusual circumstances. Situations involving foster children placed by state agencies, children of trafficked individuals, or qualifying relatives who do not meet the standard relationship tests require supplemental research beyond the training curriculum. I found myself referencing Rev. Proc. 2022-24 and multiple IRS Q&A documents when dealing with a case involving a child in protective custody. The training video mentioned foster children briefly but did not address the specific documentation requirements for children removed by state authorities.
Commercial tax software has reduced the manual burden of eligibility calculations significantly, but it cannot replace the judgment required during the due diligence interview. Software flags mathematical inconsistencies but does not identify when a claimant's story contains internal contradictions that suggest ineligibility. The training should emphasize that technology assists the process but does not substitute for professional scrutiny.
Practical Implementation Notes
The training does not need to consume more than two to three hours for a preparer who has seen typical return scenarios. However, coordinators running VITA sites should allocate additional time for preparers to work through sample cases and discuss edge conditions with experienced staff. I schedule a brief review session for each new preparer before they begin filing, covering the most common error patterns observed during the prior year. This usually prevents approximately sixty percent of the mistakes that would otherwise require amendment filings.
Maintaining current training records across multiple years requires systematic organization. I keep a master spreadsheet tracking each preparer's completion date, course provider, and certification number. This spreadsheet takes about ten minutes to update weekly and reduces administrative time during IRS examinations from several hours to roughly thirty minutes.
Gallery Eitc Due Diligence Training
Due Diligence Training - Etsy
EITC Due-Diligence Requirements: IRS Ramps Up Enforcement and Education Efforts
EITC Due Diligence / eitc-due-diligence.pdf / PDF4PRO
EITC Due Diligence Certificate | PDF
EITC Due Diligence Certificate | PPT