Practical Approaches to Cost Evaluation
Engineering economics is mostly about figuring out whether a project makes financial sense over time. You take a pile of future costs and revenues, bring them all back to today's dollars using an interest rate, and see if the number is positive. If it is, the project usually earns more than your required return. If it is not, you walk away or redesign. Most students get lost in the formulas. The real work is setting up the cash flow correctly. You need to know when money moves, whether it is a cost or a benefit, and what discount rate reflects your actual opportunity cost. Get those three right and the rest is just arithmetic.
I still remember a bridge replacement estimate that looked viable on paper because we used a single 8% discount rate for all cash flows. The problem was the maintenance schedule shifted every five years due to weather delays, and the tax credit came in year three instead of year one. The model said the net present value was solid until we mapped the actual payment dates against the contractor's invoice schedule. The NPV flipped negative after we adjusted for the delayed credits and the compounding effect of higher short-term borrowing costs. The fix was to build a year-by-year cash flow table before running any equivalence calculations, then use a spreadsheet macro to sum the discounted values automatically.
Working Through Engineering Economics Problems With Solutions
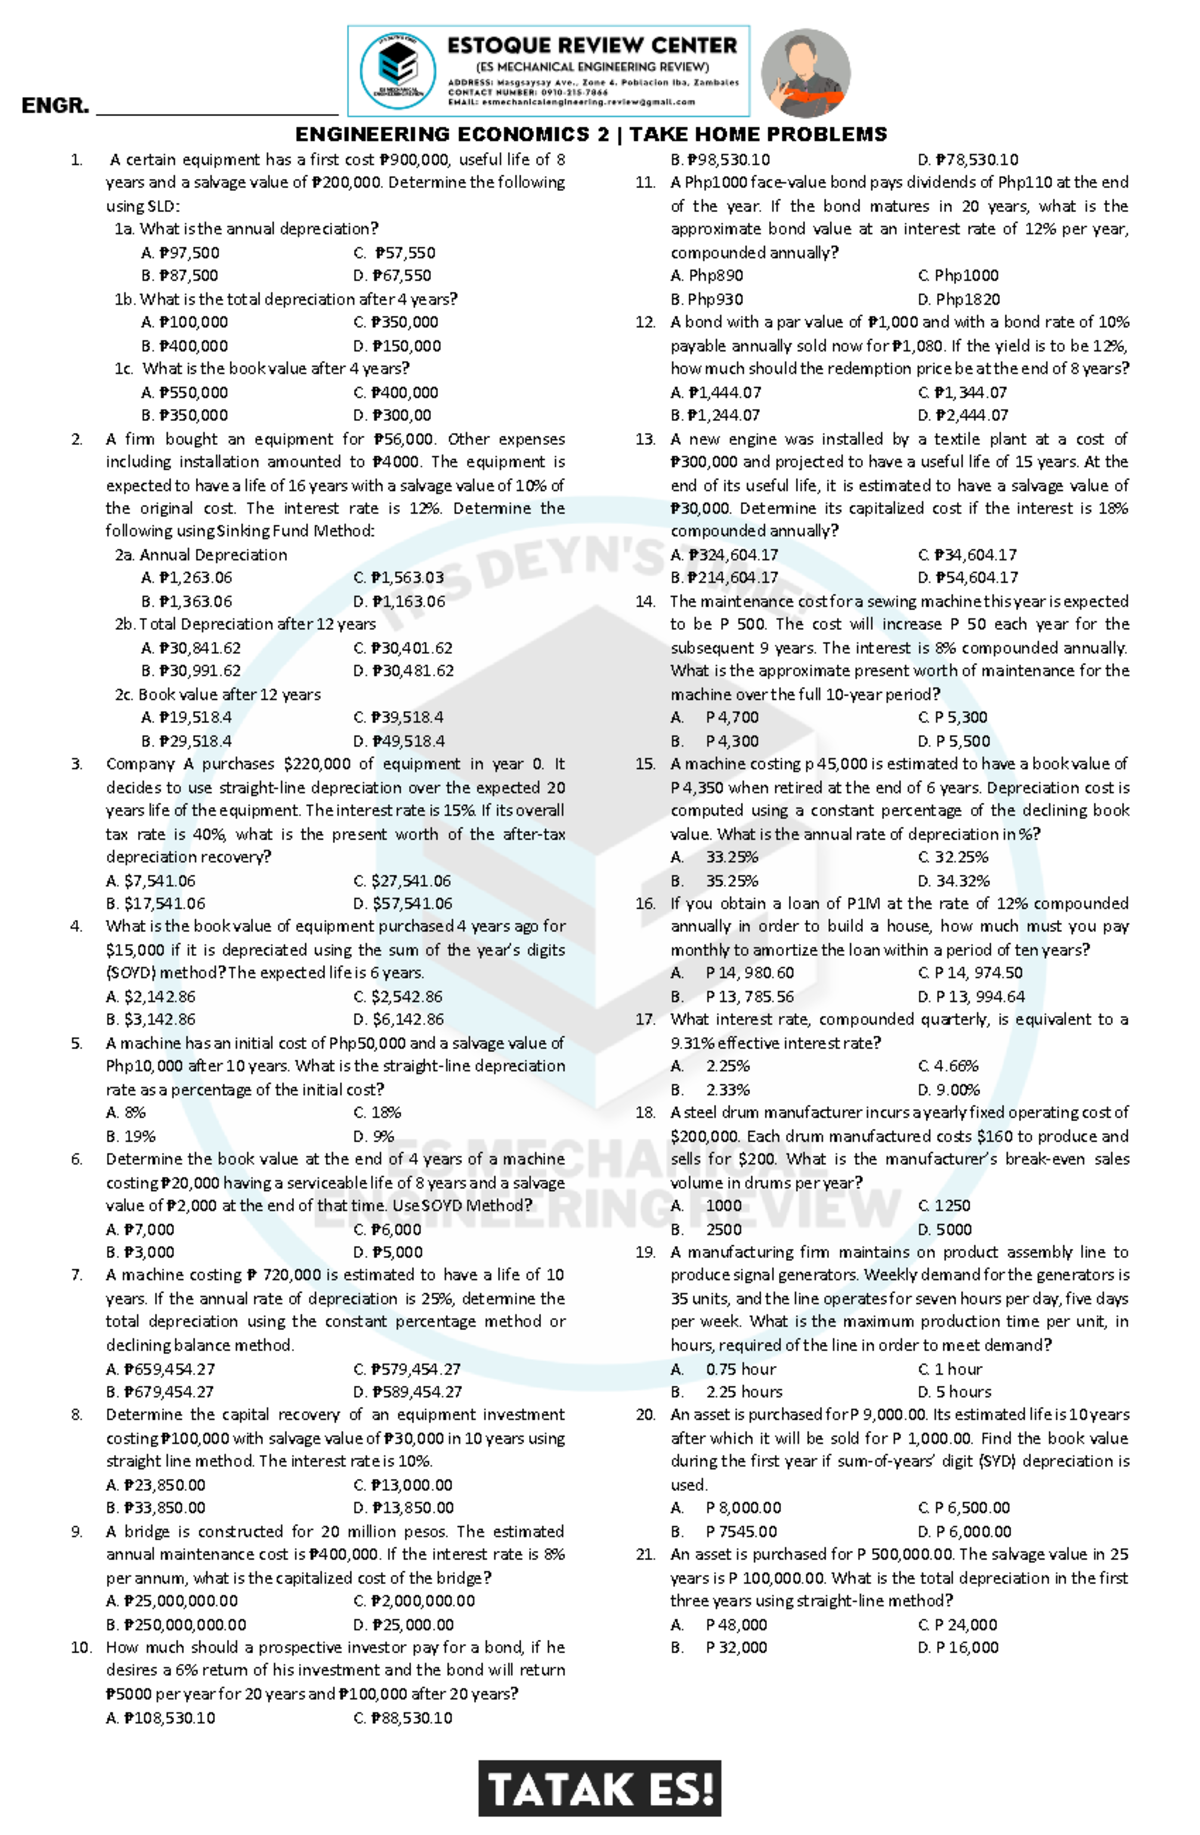
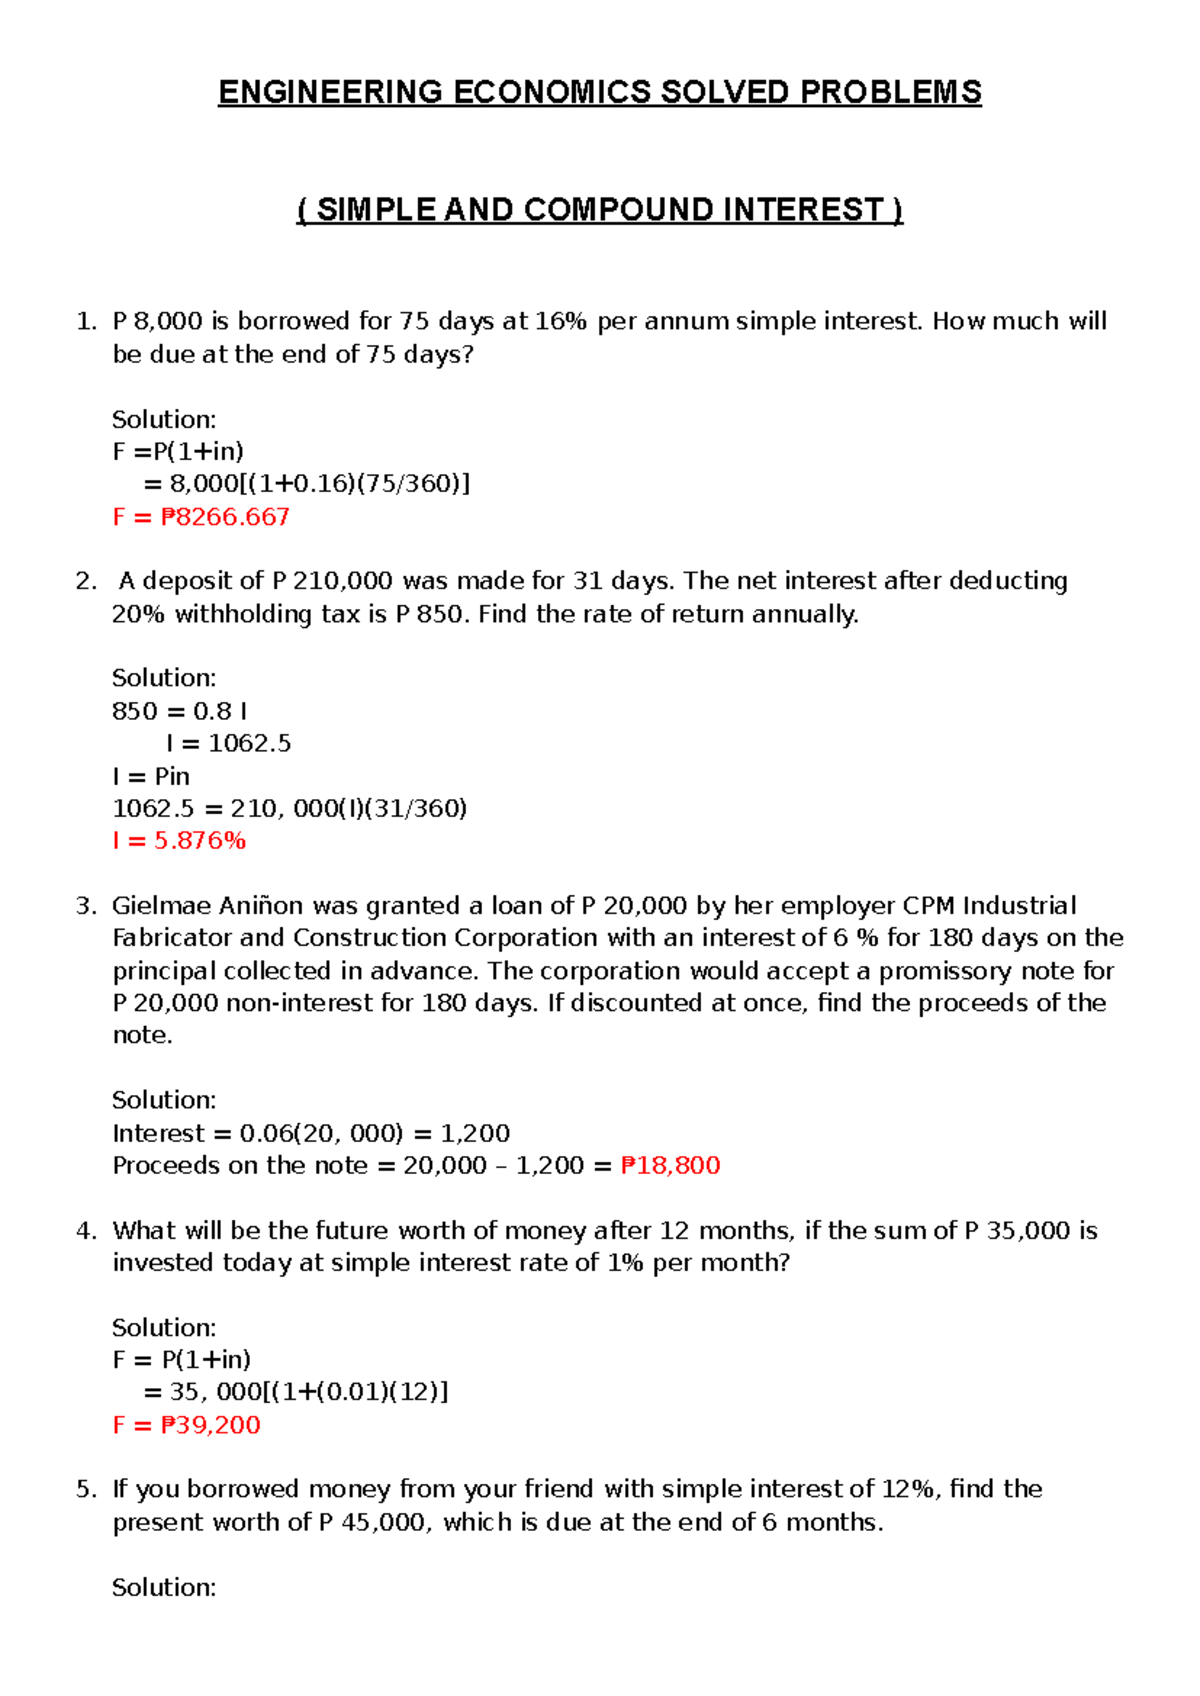
The first step is drawing the timeline. Mark every year or month where a cash flow occurs, label each amount as an inflow or outflow, and note any conditional changes. Once the timeline is clear, you pick the method that matches the decision type. Present worth is the default for comparing alternatives with different lives, as long as you use the least common multiple of their service periods or a study period agreed upon by the stakeholders. Annual worth is useful when the alternatives have indefinite or unequal lives, because it converts everything into an equivalent uniform series. Future worth is rarely the primary tool, but it shows up in retirement or sinking-fund problems where you need the accumulated amount at a specific date. The internal rate of return is often asked for in exams, but it is the trickiest metric to apply correctly. A single conventional cash flow yields one IRR, but a project with alternating sign changes can produce multiple IRRs, none of which map cleanly to your actual hurdle rate. In those cases, you fall back on net present value using your stated minimum attractive rate of return. That rate should come from your firm's weighted average cost of capital or the expected return on a comparable risk investment, not from a textbook default. Using the right MARR can shift a marginal project from acceptable to rejected in a few percentage points. Here is a concrete example. Suppose you are evaluating a solar pump system that costs $12,000 upfront, saves $2,800 per year in electricity, and requires $400 in annual maintenance starting in year two. The system lasts ten years with zero salvage value, and your MARR is 9%. You calculate the present worth by discounting each net cash flow. Years one and ten have a net inflow of $2,400 after maintenance, while years two through nine have a net inflow of $2,400 as well. The annuity factor for nine years at 9% is about 5.995, and the single payment factor for year ten is about 0.422. Multiply and subtract the initial cost, and you get a positive present worth of roughly $2,150. The project meets the MARR and is economically acceptable.
Get the Full Details

Now consider depreciation and taxes, which most beginner problems skip but real projects cannot ignore. If your jurisdiction allows straight-line depreciation over the asset life, you reduce taxable income each year and create a tax shield. That shield increases the effective after-tax cash flow and can turn a marginal project into a clear accept. I once missed that adjustment on a small water treatment upgrade and nearly approved a scope that would have lost money after tax. The workaround was to add a separate column for annual depreciation, compute taxable income as revenue minus operating cost minus depreciation, apply the marginal tax rate, and then add depreciation back since it is a non-cash expense. The after-tax present worth came out about twelve percent higher than the pre-tax estimate, which changed the ranking of competing vendors. Another common trap is comparing projects with different service lives using only present worth without adjusting for repeated cycles. A cheaper machine that fails in five years will look better than a durable machine that lasts twelve years if you do not extend the analysis to a common horizon. Use the annual worth method instead, because it naturally accounts for the equivalent yearly cost across the entire life cycle. You can also use an assumed study period and include a market value at the end of that period, but that introduces estimation error. When the data are uncertain, it is safer to stick with annual worth and clearly document the life assumptions. Sensitivity analysis is where many reports fall apart. You run one base case and call it definitive, then a stakeholder asks for a quick check and you realize the result flips if fuel prices rise by ten percent. Build a simple data table that varies the key inputs: initial cost, annual savings, discount rate, and project life. Even a quick three-value range for each parameter will show you which variable drives the decision. If the present worth stays positive across a reasonable spread, the recommendation is robust. If it hovers near zero, you should either gather better data or propose a phased investment that limits exposure.
The payback period remains popular in quick screening because it answers a straightforward question: when do I get my money back? That is useful for liquidity-constrained firms or high-risk environments where cash flow timing matters more than total return. However, it ignores all cash flows after the cutoff and does not discount them, so it can favor a short-lived project that looks cheap early but generates far less wealth overall. Use payback only as a supplementary check, not as the sole economic criterion. Inflation is another factor that gets glossed over. If your revenue and cost estimates are in nominal terms, you must discount them with a nominal interest rate. If you work in real terms, use the real rate. Mixing the two breaks the equivalence. A practical rule is to decide whether your market research gives you current-dollar forecasts or constant-dollar forecasts, then match the discount rate accordingly. I have seen estimates that used nominal cost growth but discounted at a real rate, which understated the present cost and made an expensive upgrade look attractive. Correcting the mismatch typically shifts the net present value by several percent and can reverse the decision. For projects with high uncertainty, traditional deterministic analysis may give a false sense of precision. Risk-adjusted discount rates can rough in the uncertainty, but they tend to penalize all future cash flows uniformly and may reject projects that have valuable flexibility. Real options analysis treats investment timing, expansion, and abandonment as choices with option-like payoffs. It is more work to set up, but it captures the value of waiting for better information. If your cash flows are highly volatile and you have the data to model scenarios, I recommend a quick Monte Carlo simulation alongside the base-case calculation. Even a hundred iterations in a spreadsheet will show you the distribution of possible outcomes and the probability of a negative net present value.
The bottom line is that engineering economics is not about picking a formula and plugging numbers. It is about modeling the actual cash flows, choosing the right equivalence method for the decision context, and testing how sensitive the result is to your assumptions. The problems you will face on the job are messier than textbook examples, with changing tax rules, staggered cash flows, and incomplete data. The solutions come from careful setup, consistent units, and a willingness to revisit the model when new information arrives. If you want a reliable way to practice, build your own cash flow tables for real equipment purchases in your department, then compare the calculated present worth against the vendor proposals and the actual post-purchase performance. The discrepancy between the model and reality will teach you more than a dozen solved examples. Keep the spreadsheet transparent, document every assumption, and let the numbers guide the recommendation, not the other way around.