
Engineering Economy Exams: What Actually Shows Up and How to Not Waste Three Hours
Engineering economy final exams are brutal because they pile multiple time-value-of-money calculations into one problem and then add tax, depreciation, and inflation on top. I've proctored them, taken them, and watched students fail the same question six years in a row. The most common reason isn't that the math is hard. It's that students don't set up the cash flow diagram before they start crunching numbers. Here's the thing nobody tells you: about 40 percent of the exam is just reading comprehension and cash flow setup. The formulas themselves are standard. What trips people up is converting a word problem into the right series of arrows on a timeline. Once you have that, the rest is plugging into interest factors or spreadsheet functions. Missing the setup step is why people lose points even when they know the formulas. I'm going to walk through the actual structure of these exams, the shortcuts that save time under pressure, and the one edge case that caught me off guard on my own final. This isn't theory. This is what happens when you're sitting there with a 120-minute exam and a problem that mentions MARR, sinking funds, MACRS depreciation, and a salvage value all in the same paragraph.
What the Exam Actually Tests
Most engineering economy finals revolve around six or seven core topics. If you can solve problems in these areas, you're covering roughly 80 to 90 percent of what shows up on the exam. Present and future worth analysis is always there. You'll get a project description with cash inflows and outflows spread across multiple years. You need to determine whether the project meets the minimum attractive rate of return. This means discounting everything back to year zero or compounding everything forward. Both methods give the same answer if you do the math correctly. Pick the one that requires fewer steps for the problem at hand. Annual cash flow equivalence shows up constantly. You might be asked to convert a present worth into an equivalent uniform annual series or vice versa. The A/P and P/A factors appear everywhere. Students sometimes confuse which one to use. Here's a practical way to remember: if you're given a present amount and need the annual equivalent, you use the capital recovery factor, which is the A/P factor. If you're given an annual amount and need the present worth, you use the P/A factor. It sounds obvious until you're racing against the clock and your brain short-circuits.
Depreciation methods, especially MACRS, are another staple. You'll need to calculate the depreciation schedule for an asset and then use it to find the taxable income and tax liability in each year. MACRS uses prescribed percentages based on the asset class and recovery period. The percentages are usually provided in a table during the exam, but you still need to apply them correctly to the depreciable basis, which is typically the initial cost minus any salvage value that's being treated as recovered through depreciation rather than at the end of the project. Tax calculations are where a lot of students lose points. Taxable income equals gross revenue minus operating expenses minus depreciation. Then you multiply by the tax rate to get the tax payment. After-tax cash flow is gross revenue minus operating expenses minus taxes. That's the framework. But then the problem might throw in a gain or loss on the sale of the asset at the end of its life, which creates a tax effect based on the difference between the salvage value and the book value. That extra step catches people who stop after calculating the annual operating taxes. Inflation adjustments come up less frequently but still show up on every exam I've seen. You need to distinguish between then-current dollars and constant dollars. If the cash flows are given in actual dollars and the MARR is a market rate that includes inflation, you use the market MARR directly. If the cash flows are in constant dollars, you need to adjust the MARR to a real rate. The formula is i_real equals 1 plus i_market divided by 1 plus f, minus 1, where f is the inflation rate. Misapplying this formula is a common error.
Get the Full Details
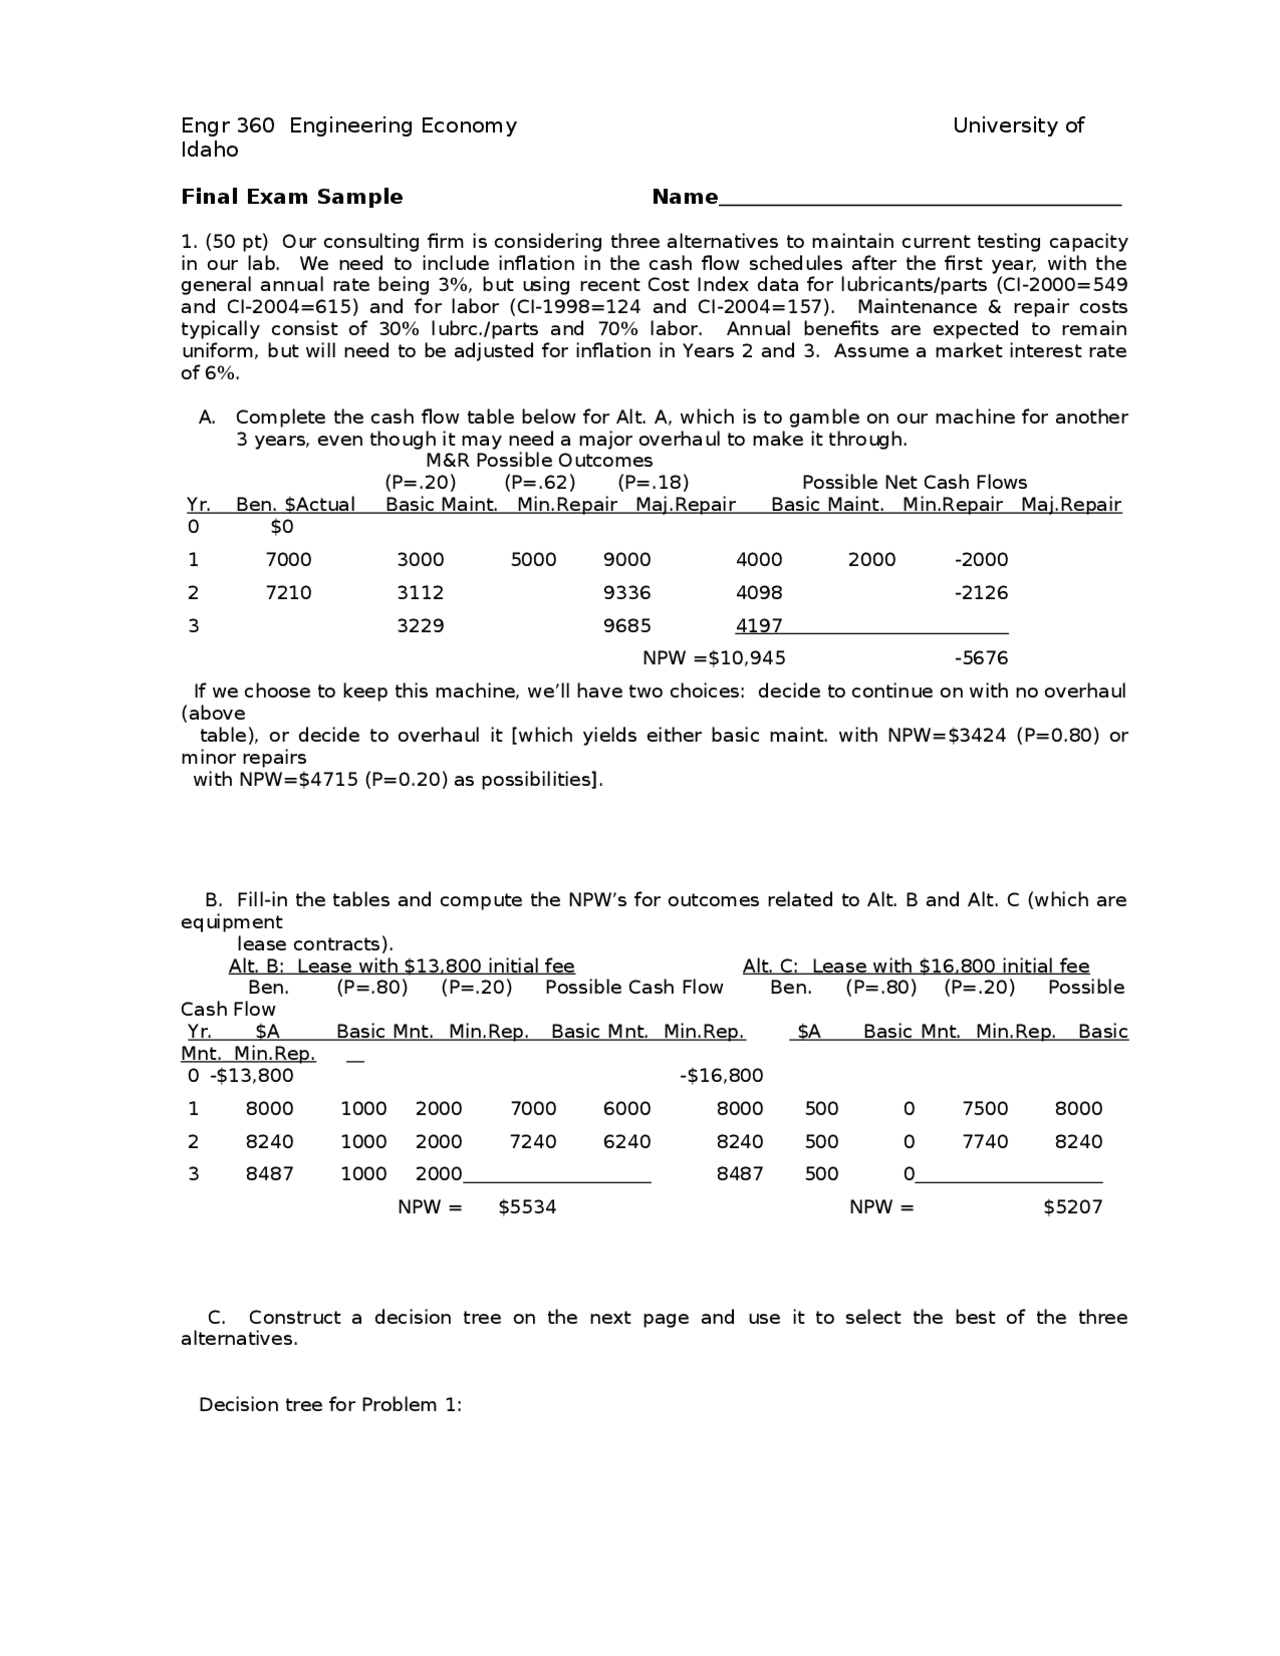
Replacement analysis appears occasionally. You're comparing keeping an existing asset, called the defender, versus replacing it with a new one, called the challenger. The correct approach is to compare the equivalent annual costs of each option over their respective useful lives. A lot of students try to compare total costs over different time horizons, which is wrong. The annual cost method normalizes everything to a per-year basis so the comparison is fair. Sensitivity and risk analysis is sometimes included. You might be asked how the present worth changes when a key variable like revenue or cost changes by plus or minus a certain percentage. This is straightforward once you understand the basic model. You recalculate with the adjusted values and compare the results. The insight here is that sensitivity analysis doesn't require probability distributions. Simple scenario testing is usually enough for an undergraduate exam.
How I Actually Solved the Problem That Cost Me a Letter Grade
During my own final, there was a problem about a machine that cost 85,000 dollars, had a five-year MACRS recovery period, annual operating costs of 12,000 dollars, annual revenue that started at 40,000 dollars and increased by 3,000 dollars each year, a tax rate of 35 percent, and a MARR of 12 percent. The question asked for the after-tax present worth over six years with a estimated salvage value of 15,000 dollars at the end of year six. The twist was that the machine was sold at the end of year six, which was after its MACRS recovery period had ended. I spent twelve minutes on that problem and got it wrong. The issue wasn't the depreciation calculation. I had the MACRS percentages right. The issue was the book value at the time of sale. Since the asset was in the five-year MACRS class and we were selling it at the end of year six, the book value was zero. That meant the entire 15,000 dollar salvage value was a taxable gain. I had forgotten to include the tax on the salvage value in my after-tax cash flow for year six. I only included the 15,000 dollar inflow and ignored the tax liability it created. The tax on the gain was 5,250 dollars. That difference changed the present worth from positive to negative, which flipped my decision on whether to accept the project. The workaround, and the one I use now for every problem like this, is to write down the book value at the time of disposal before I start calculating anything else. Book value equals initial cost minus accumulated depreciation. If the asset has been fully depreciated, the book value is zero and the entire salvage value is taxable. If the asset hasn't been fully depreciated, the book value is positive and the gain or loss is the difference between salvage value and book value. I now do this check as step one for any problem involving asset disposal. It takes ten seconds and prevents the kind of error that cost me points on that exam.
Formulas and Shortcuts That Actually Matter
You don't need to memorize every formula. Most exams provide a formula sheet. What matters is knowing which formula to reach for and how to combine them. The core relationships are the compound interest factors. Here's the practical version you need to know cold. The present worth of a uniform series is P equals A times the P/A factor, which is the interest rate raised to the power of the number of periods, all over the interest rate times one plus the interest rate raised to the power of the number of periods. The future worth of a uniform series is F equals A times the P/A factor times one plus the interest rate raised to the power of the number of periods. The capital recovery factor, which converts present worth to annual worth, is the interest rate times one plus the interest rate raised to the power of the number of periods, all over one minus the interest rate raised to the power of the number of periods. For geometric gradients, where cash flows increase or decrease by a constant percentage each period, the present worth formula is different. If the growth rate g is not equal to the interest rate i, the present worth is A1 times one minus the ratio of one plus g over one plus i raised to the power of n, all over i minus g. If g equals i, the present worth simplifies to A1 times n divided by one plus i. These formulas are easy to mix up. I always derive them from first principles during the exam rather than trying to recall the exact form. It takes a minute longer but it's more reliable.
Excel is allowed on most engineering economy exams, and it changes the game. Instead of looking up factors in tables or computing them by hand, you can use the PV, FV, PMT, NPV, and IRR functions. The PV function calculates present worth given a rate, number of periods, and payment. The NPV function calculates the net present value of a series of cash flows. The IRR function finds the internal rate of return. These functions save time and reduce calculation errors significantly. A problem that would take ten minutes by hand can often be solved in two minutes using Excel, assuming you set up the cash flow series correctly. One important detail about Excel's NPV function: it assumes the first cash flow occurs at the end of period one. If your initial investment occurs at time zero, you need to add it separately outside the NPV function. A lot of students plug all cash flows into NPV including the initial investment, which shifts everything by one period and gives the wrong answer. The correct formula is NPV of the future cash flows plus the initial investment, which is typically a negative number at time zero.
Time Management and Exam Strategy
Engineering economy exams are long problems with many parts. You don't have time to be meticulous about every decimal place. The key is to work in a consistent order and move on when you've gotten reasonable precision. Three significant figures is usually sufficient for the final answer. Carrying more digits through intermediate steps is smart, but reporting twelve decimal places doesn't help you and wastes time. I recommend starting with the problems you find easiest. Most exams have a mix of straightforward present worth calculations and more complex after-tax replacement analyses. The straightforward problems might be worth 10 to 20 points each and should take five to eight minutes. The complex problems might be worth 25 to 40 points and could take 15 to 25 minutes. If you dive into the hardest problem first, you risk running out of time on the easier ones that you could have solved quickly. Drawing the cash flow diagram is not optional. It takes two or three minutes and it prevents mistakes that cost five or ten points. Draw the timeline, mark each cash flow with its amount and direction, and label the interest rate and period. Once the diagram is clear, the rest of the problem usually resolves itself. I've seen students stare at a word problem for eight minutes without drawing anything, then realize halfway through that they'd misread the timing of a cash flow. That diagram would have prevented the entire headache.
If you get stuck on a multi-part problem, write down the formula you would use and label what each variable represents. Some professors give partial credit for correct setup even if the final calculation is wrong. A blank answer always gets zero. A correct setup with a arithmetic error might get you half the points. In an exam where you're competing for a B versus a C, those partial credits matter.
When Standard Methods Break Down
Engineering economy methods work well for most textbook problems, but they have real limitations that exams sometimes test indirectly. One major limitation is the assumption of a constant interest rate. Real projects often face changing rates, especially over long time horizons. If the problem gives you a single MARR, you use it. But if you're doing a sensitivity analysis where the interest rate varies, you need to be aware that the standard formulas assume a constant rate throughout the analysis period. There's no simple extension for a varying rate. You'd need to discount each cash flow individually at the rate applicable to that period. Another limitation is the treatment of risk. Traditional engineering economy uses expected values and deterministic analysis. It doesn't really handle uncertainty in a rigorous way. Some exams ask you to do a simple sensitivity analysis by changing one variable at a time. That's fine for an undergraduate level, but it's worth knowing that this approach doesn't capture the full risk picture. Monte Carlo simulation would be more realistic, but it's almost never expected on a standard engineering economy final. If a professor wants you to go beyond basic sensitivity analysis, they'll usually provide the tools or specify the method. The assumption that cash flows occur at discrete intervals, usually at the end of each year, is another simplification. In practice, cash flows can be continuous or irregular. For exam purposes, you stick to the discrete model. But if you encounter a problem where cash flows are described as continuous, you might need to use continuous compounding formulas instead. The present worth factor for continuous compounding is e to the power of negative i times n, where e is the base of the natural logarithm, i is the interest rate, and n is the number of periods. This is rare but it shows up occasionally and students who don't know it are lost.
Perhaps the most important limitation is that engineering economy analysis is only as good as the input data. If the revenue estimates, cost estimates, or salvage values are wildly inaccurate, the optimal decision from the analysis could be completely wrong. This isn't a flaw in the method. It's a reminder that the output is garbage if the input is garbage. Some professors test this understanding by giving you problems where the numerical result is close to zero, meaning small errors in the inputs could flip the decision. In those cases, the sensitivity analysis is the real point of the problem, not the final present worth number.
What I Wish I Knew Before Taking the Exam
If I could go back, I would have spent more time practicing after-tax cash flow problems. They show up on every exam and they combine multiple concepts in a way that's easy to mess up. The sequence is always the same: calculate depreciation, find taxable income, calculate taxes, find after-tax cash flow, then do the time-value analysis. If you skip a step or do them in the wrong order, everything downstream is wrong. Practicing this sequence repeatedly until it becomes automatic is the single most effective study strategy I can recommend. I also wish I had practiced reading problems more carefully. Engineering economy word problems pack a lot of information into dense paragraphs. Mentions of tax rate, MARR, recovery period, salvage value, operating cost escalation, and revenue growth can all appear in the first two sentences. Missing one of these details changes the entire solution. I've developed a habit of underlining or circling every numerical value and parameter as I read the problem. It adds maybe thirty seconds to the reading time but it prevents misreading errors that cost significant points. Finally, I wish I had understood that the exam is testing your ability to make engineering decisions, not your ability to compute numbers. The numerical answer is important, but the reasoning behind it is what separates a good answer from a great one. If you can clearly state your assumptions, show your setup, and interpret the result in the context of the problem, you're demonstrating the kind of thinking that the course is designed to teach. The formula is just a tool. The decision is what matters.
Good luck. The exam is long but manageable if you stay organized and keep your cash flow diagrams clean.

