
How to Actually Use Enrolled Agent Practice Exam Materials
You don't need another motivational post about passing the EA exam. You need to know how to study without wasting three months on practice questions that don't reflect what shows up on the real test. Here's the straightforward version of how I used these materials, what worked, what didn't, and where people consistently lose points. The IRS administers the Enrolled Agent exam through Prometric, and it's split into three parts: Individual Taxation, Business Taxation, and Representation, Practices, and Procedures. The study guides from Veda, Gleim, and other providers are fine for learning the material, but they're not the same as taking timed practice questions that match the actual exam's difficulty curve. That's where a proper Enrolled Agent Practice Exam comes in. I went through three different commercial question banks before the real thing. The cheapest one was garbage. The expensive one was close but had weird formatting quirks. The one that actually prepared me was the official practice exam from the IRS-aligned providers — the ones that mirror the Prometric interface and time limits. Don't skip this step. I saw people walk into the exam center thinking they were ready after grinding through flashcards and textbook summaries. They weren't.
The Actual Process I Used
Here's exactly how I structured my study around practice exams instead of just reading: first, I took an untimed diagnostic using the full range of questions across all three parts. This took me about 45 minutes per part, roughly 2 hours total. I got maybe 62 percent overall. Not great, but it told me which sections were actually weak versus just unfamiliar. The key insight most people miss is that Part 3 (Representation, Practices, and Procedures) has a completely different mental framework from Parts 1 and 2. It's not about calculating tax liability. It's about knowing the rules of engagement with the IRS — ethics, authority of representatives, collection procedures, penalties. I spent maybe 20 percent of my time on Part 3 initially because I assumed it would be easier. That was a mistake. The scoring weight is equal across all three parts, and Part 3 is where most people underperform because they treat it like a memorization test instead of a procedural reasoning test. After the diagnostic, I started doing timed practice sets of 50 questions per session. Real exam conditions. No notes, no calculator app, just the on-screen calculator Prometric provides. I aimed for 75 percent or above on each set before moving to the next topic cluster. If I scored below 70, I'd go back to the specific section and re-read just that material, then retake a fresh set.
A Specific Problem I Ran Into
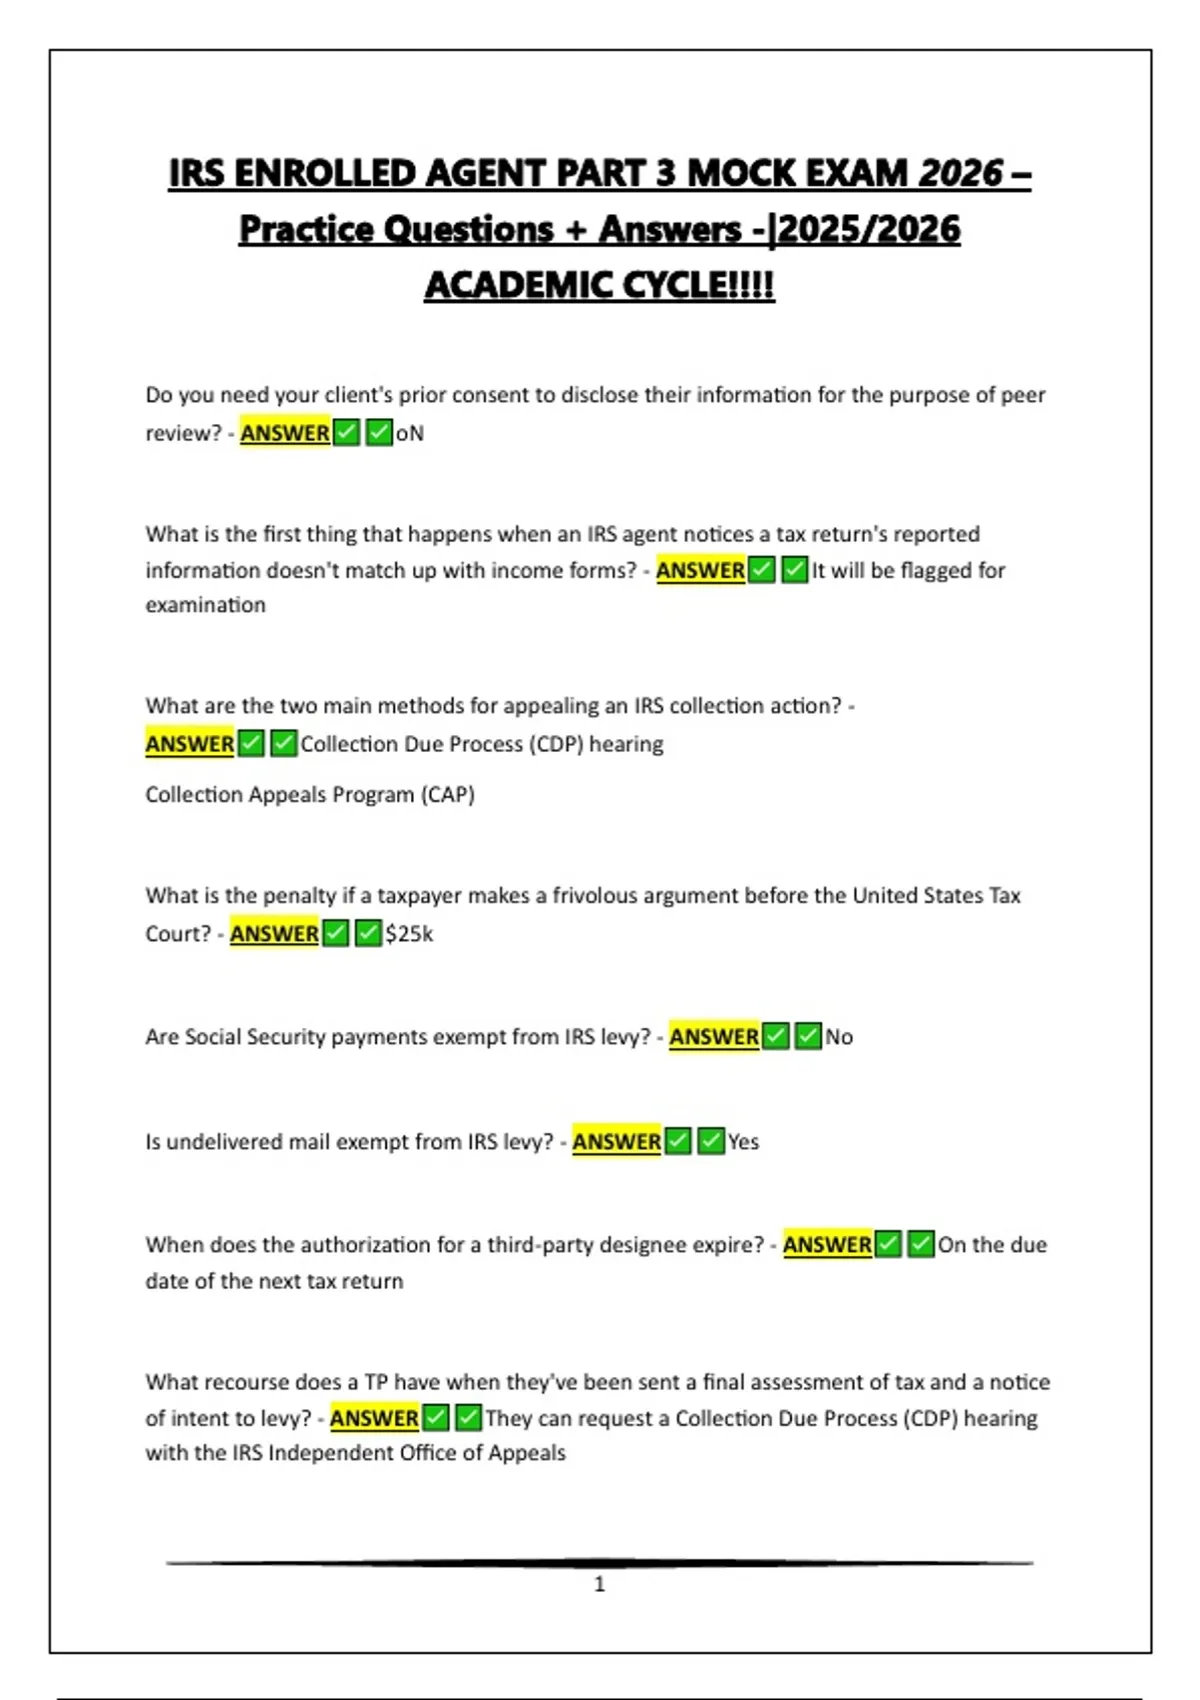
During my second week of practice, I kept missing questions about the difference between a power of attorney (Form 2848) and a tax information authorization (Form 8283). On paper, the definitions seemed clear enough. But in the practice exam questions, the scenarios were deliberately ambiguous — like "a client wants their preparer to discuss an audit with the IRS" versus "a client wants their preparer to represent them at an appeals conference." The correct answer changed based on whether it was a discussion or formal representation, and whether the preparer already had prior involvement with the return. I wasted two days going back and forth until I found a table that clearly mapped out every scenario. I printed it, taped it to my wall, and stopped second-guessing myself on those questions. The exam doesn't test whether you know the form numbers. It tests whether you can distinguish between the scope of authority each form grants in practice.
Get the Full Details
What Most Study Guides Get Wrong
The biggest issue with many review courses is that they over-index on Part 1 (Individual Taxation) because it's the longest section and has the most calculable problems. Parts 2 and 3 get shortchanged. But when you look at the actual exam distribution, Part 2 (Business Taxations) has questions on S corporations, partnerships, and C corporations that are just as weighty as any individual tax question. And Part 3's procedural questions are trickier than they appear because the IRS changes its practices and published guidance regularly. I noticed this clearly in my practice scores. My Part 1 scores plateaued around 78 percent no matter how many questions I did. But my Part 2 and Part 3 scores jumped significantly once I started focusing on IRS Publications — specifically Publication 1 (Your Rights as a Taxpayer), Publication 556 (Examination of Returns), and Publication 947 (Practice Before the IRS). These are dry reads, but they're essentially the source material for a lot of Part 3 questions. Study guides summarize them; the exam draws directly from them.
The Practical Workaround for Time Pressure
The real exam gives you about 2 hours per part with roughly 100 questions. That's roughly 72 seconds per question. Most people don't practice under this constraint, so they learn content but can't execute it fast enough on test day. I built a simple timing drill: I set a timer for 70 seconds per question on my phone and forced myself to move on the second it went off, even if I hadn't selected an answer yet. This felt brutal at first, but it trained me to make quick decisions and flag questions for review rather than stewing on one problem for three minutes. This usually cuts your effective study time down from maybe 80 hours to about 40 to 50 hours if you focus on practice exams from day one instead of reading textbooks cover to cover. The trade-off is that you need to identify your weak areas quickly and stop studying things you already know cold.
Finding Reliable Practice Questions
When I say Enrolled Agent Practice Exam, I don't mean random quizlet sets or free PDFs you download from obscure forums. Those have errors, outdated information, or questions written by people who don't actually know tax law. The ones worth using are from established providers like Veda, Gleim, Keokeen, or the IRS's own annual mock exam if they offer one. Some of these are free. The paid ones are usually $50 to $150 and often include performance analytics that show exactly which topics you're missing. The analytics feature alone is worth the price. It tells you whether you're consistently wrong on capital gain calculations, S corp distributions, or penalty calculations. Instead of guessing what to study next, you just open the report and attack the weakest area. That's how I turned my Part 2 score from 61 percent to 84 percent in about 10 days of targeted practice.

Where This Approach Breaks Down
Practice exams alone won't prepare you if you have zero foundational knowledge. If you've never taken a tax course and open a practice question about like-kind exchanges under Section 1031, you won't learn anything by guessing and checking the answer. You need at least a basic grasp of the concepts before the practice questions become useful. I'd recommend going through a single review course (Gleim or Veda, either one) to get the framework, then switching entirely to practice mode for the last two to three weeks before the exam. Also, the exam occasionally pulls questions from tax law changes that haven't been widely covered in older study materials. The Tax Cuts and Jobs Act provisions, for example, are fully tested now, and some newer updates on like-kind exchange rules or qualified business income deductions may not appear in materials published before 2024. Always check the publication date of your question bank and supplement with the current year's IRS guidance if the material feels stale. I passed on my first attempt after about seven weeks of part-time study — roughly 15 to 20 hours per week. The biggest factor wasn't reading more. It was doing enough practice questions under realistic conditions to build speed and pattern recognition. That's what most people underestimate when they start preparing.


