Working Through the Enron Case Study
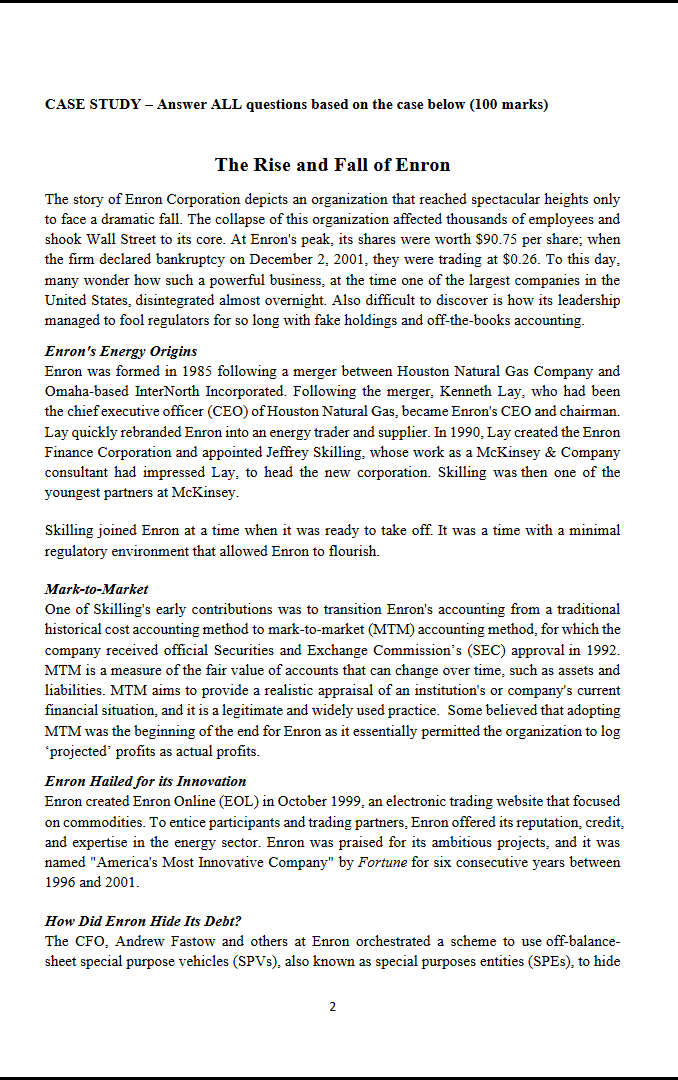
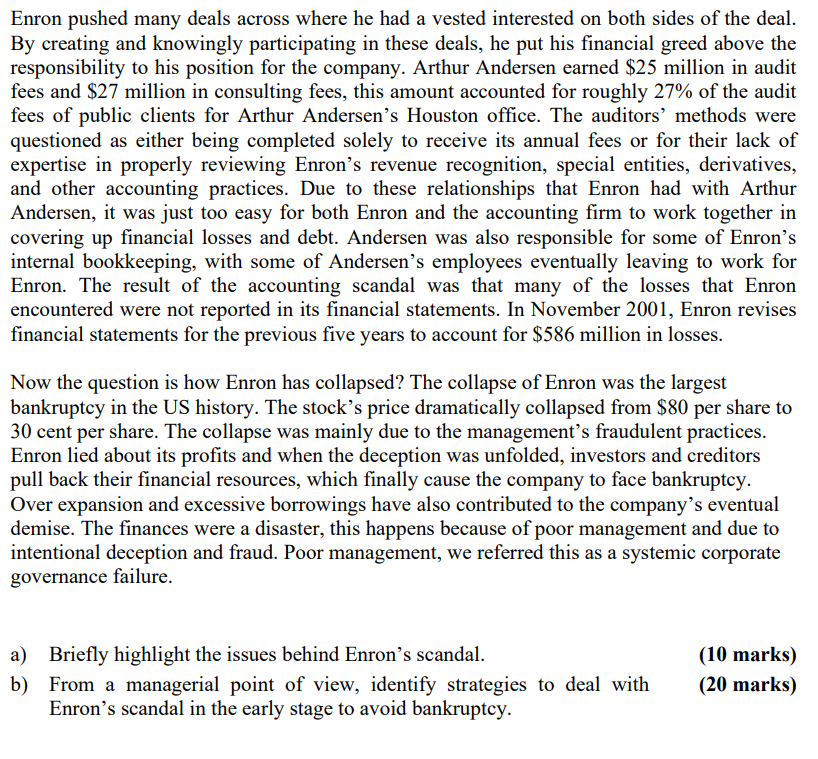
I ran into a problem with Enron Case Study Questions And Answers about three years ago when a student sent me their draft before an exam. The paper was technically correct on every factual point — dates, names, financial figures — but it completely missed the real mechanism that made the collapse possible. They had treated Enron as a story about greedy executives rather than a story about how financial engineering can be used to systematically hide leverage. That distinction matters when you're actually trying to understand what happened, not just memorize a timeline. The most frequently asked question is straightforward: What caused Enron's bankruptcy in 2001? The short answer is that Enron used special purpose entities, commonly called SPEs, to move debt off its balance sheet. This wasn't minor accounting — it was a structured program that involved thousands of these entities. The company reported strong profits to investors while the actual debt burden grew invisible. When the SEC started asking questions and analysts began connecting the dots, the stock price collapsed from around ninety dollars per share to under a dollar within months. Another common question asks about the role of Arthur Andersen. Andersen was Enron's auditor and, critically, its consultant. The firm earned roughly twenty-five million dollars annually from Enron for auditing services and another fifty million or so from consulting work. That conflict of interest meant Andersen had a financial incentive not to dig too hard into Enron's more aggressive accounting treatments. When the scandal broke, Andersen destroyed documents related to Enron. That destroyed the firm itself. It went from being one of the Big Five accounting firms to essentially non-existent in a matter of months.
Questions about what went wrong with corporate governance come up constantly. The board of directors approved Enron's use of SPEs, which is unusual. Most boards don't explicitly greenlight the mechanisms that will later be used to defraud shareholders. Jeff Skilling, who became CEO in 2001, had convinced the board to adopt mark-to-market accounting for Enron's energy trading division. Under that system, Enron could book estimated future profits from long-term contracts immediately. The problem was that those estimates were almost entirely self-generated. There was no independent market pricing for many of these complex energy derivatives. You'll also see questions asking whether Enron's executives broke the law or simply exploited loopholes. The evidence shows they did both. Kenneth Lay, Andrew Fastow, and others were convicted of fraud and conspiracy. Fastow, who set up the SPEs, pleared guilty and cooperated with prosecutors. The line between aggressive accounting and illegal fraud wasn't clear to many people inside Enron at the time, which is part of why the case remains so useful for teaching. Students often ask what lessons this case teaches. The most important one is that financial statements are not neutral documents. They are arguments made by management, and auditors are supposed to check the evidence. When the auditor is also a consultant earning millions from the same client, the check becomes theoretical at best. This is exactly why the Sarbanes-Oxley Act was passed in 2002. It created the PCAOB, mandated auditor independence rules, and required CEOs and CFOs to personally certify financial reports.
A second lesson is harder to absorb but worth taking seriously. Competence without integrity is more dangerous than incompetence. The people at Enron were extraordinarily smart. They understood derivatives, tax law, and regulatory gaps. That intelligence made the fraud far more effective than something a less skilled group could have pulled off. Intelligence without ethical constraints is a force multiplier for harm.
Get the Full Details

Practical Notes from Using These Materials
When I review student work on this topic, the most common mistake is treating the case as a moral fable instead of a structural analysis. Yes, people were greedy. Yes, some lied. But the case is really about institutional failure — how boards, auditors, regulators, and rating agencies all failed to catch what was happening because the incentives were misaligned and the complexity was deliberately designed to resist scrutiny. I had a student once who spent twenty pages describing the personalities involved and only two paragraphs on the actual accounting mechanics. That approach gets a mediocre grade because the professor wants to see that you understand how Enron concealed approximately eighteen billion dollars in debt through its SPE structure. The company created over a thousand special purpose entities. Fastow personally managed many of them while simultaneously serving as Enron's CFO. He earned hundreds of millions from the Cheetah and Raptors entities alone. Another issue I see frequently is confusion about mark-to-market accounting itself. The technique isn't inherently fraudulent. Natural gas pipelines and power plants use similar valuation methods, and those are legitimate. Enron applied the method to long-term contracts with no liquid secondary market, using their own internal models to estimate future cash flows. That's where it crossed from aggressive accounting into deception. The distinction matters because your professor will notice if you conflate the two.
If you're working through this case study on your own, I'd recommend starting with the SEC's administrative proceedings against Lay and Skilling. Those documents are available publicly and they lay out the specific factual findings in more detail than most textbook summaries. The Enron whistleblower, Sherron Watkins, also wrote a detailed memo to Lay in August 2001 warning about the accounting problems. Reading that primary source gives you a much clearer picture than any secondary summary ever will. One thing most study guides don't emphasize enough: the role of Wall Street. Investment banks like Citigroup, Goldman Sachs, and JPMorgan Chase facilitated Enron's structure. They earned substantial fees and, in several cases, knowingly participated in transactions that helped Enron hide debt. Some analysts at these banks continued to rate Enron stock as a buy even as the red flags mounted. That conflict between investment banking relationships and equity research is another reason Sarbanes-Oxley eventually addressed the separation of those functions. The case also illuminates how employee retirement savings were destroyed. Enron workers were encouraged to load their 401(k) plans with Enron stock, and the company's stock-based compensation meant executives were effectively betting everything on the share price. When it collapsed, thousands of people lost their jobs and their retirement savings simultaneously. That's not an abstract accounting story. It's the human consequence of the structural failures described above.
When you're preparing your answers, focus on the sequence of events and the causal chain. Enron's stock rose because of aggressive accounting that inflated reported earnings. The inflated earnings attracted more investors, which pushed the price higher, which justified more aggressive accounting because the stock could be used as currency for acquisitions. It was a feedback loop that only broke when the stock stopped rising. Understanding that dynamic is more valuable than memorizing individual facts about any single year or transaction. The Enron case remains relevant because similar patterns keep appearing. Wirecard in Germany, Theranos in the US, Luckin Coffee in China — each has its own details, but the structural weaknesses are recognizably the same. Weak board oversight, conflicted auditors, opaque financial structures, and a culture where dissent was punished. Studying Enron carefully gives you a template for spotting those patterns elsewhere. If you want a solid starting point for Enron Case Study Questions And Answers, the Harvard Business School published a well-regarded case on Enron that includes both the primary documents and teaching notes. It's widely used in graduate business programs and you'll find it referenced in most course syllabi. Pair that with the House Energy and Commerce Committee's post-collapse report, and you'll have more material than any exam or paper will reasonably require.