What Actually Gets Asked in These Interviews
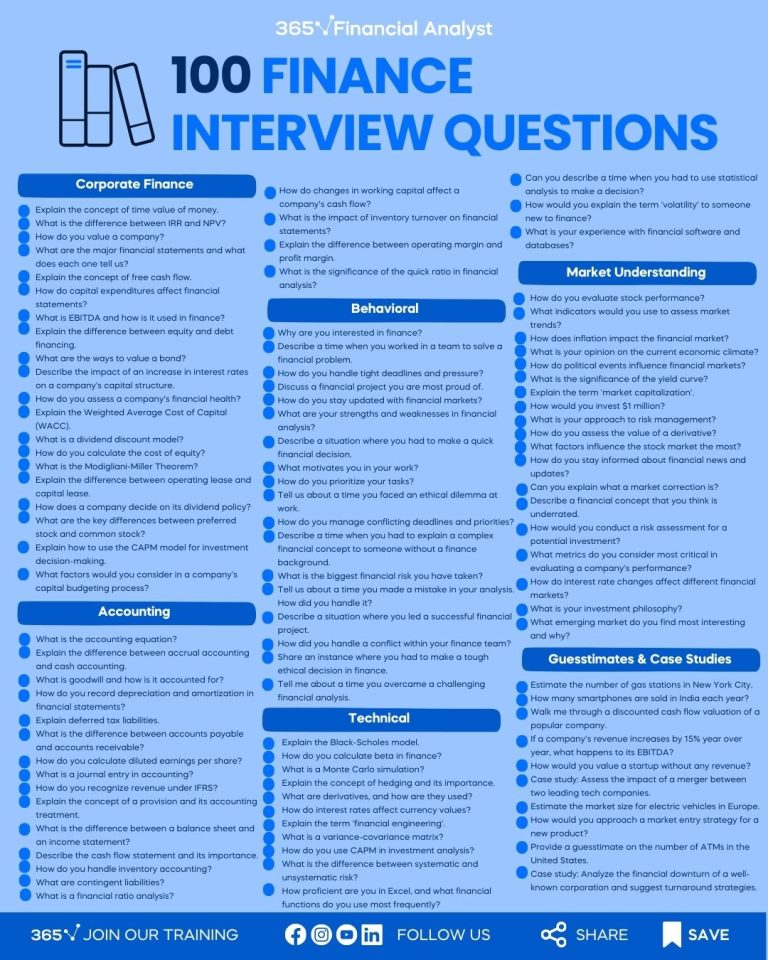
I've been through enough of these to know the pattern, and honestly most entry level financial analyst interview questions and answers boil down to the same handful of topics. You're going to get technical questions about accounting, Excel, and modeling, then some behavioral stuff, and occasionally a curveball that they don't really care about the answer to as much as they care about how you think under pressure. Here's the thing nobody tells you before walking into one of these. The technical questions are never actually testing whether you've memorized the right answer. They're testing whether you can work through an unfamiliar problem without freezing up. I remember sitting across from a hiring manager who asked me to walk through how I'd value a company with no earnings history. The "correct" answer for someone just out of school would be something about revenue multiples or DCF assumptions, but the company I was interviewing with was a pre-revenue biotech firm. I ended up telling him straight that I'd start by understanding their pipeline milestones and then work backward from comparable acquisition multiples in the sector. He nodded and moved on. What he was really checking was whether I'd try to BS my way through a formula that doesn't apply, which is exactly what half the candidates do. The most common technical questions you'll face fall into a few buckets. Accounting basics, Excel skills, financial modeling fundamentals, and valuation concepts. Let's go through them.
Walk me through the three financial statements and how they connect. This comes up in almost every interview. You need to know that net income from the income statement flows into retained earnings on the balance sheet and also starts the cash flow statement under operating activities. Changes in the balance sheet accounts then feed into the cash flow statement as well. The three statements tie together when net income plus depreciation and amortization, minus changes in working capital, minus capital expenditures, plus or minus financing activities equals the change in cash on the balance sheet. That's the basic loop. Most people fumble here because they memorize a textbook definition instead of actually tracing the flow. If you can draw it on a whiteboard or napkin without hesitating, you're in good shape. What's the difference between NPV and IRR? Net present value gives you an absolute dollar amount representing the value created by a project after accounting for the time value of money. Internal rate of return is the discount rate that makes the NPV equal zero. They usually point in the same direction, but not always. When you're comparing mutually exclusive projects with different scales or timing of cash flows, NPV is the more reliable metric. I've seen candidates confidently say IRR is better because it's a percentage and easier to compare, which is wrong in about half the real world scenarios they'd actually encounter. Know when each one breaks down, not just what it is. How would you build a three-statement model from scratch? This is the question that separates people who've actually done modeling from people who've watched a YouTube tutorial. Start with the income statement because it drives most of the other line items. Project revenue based on your assumptions, build out COGS and operating expenses as percentages or fixed amounts depending on what makes sense, get to net income, then carry that forward to the balance sheet through retained earnings. Build the balance sheet from the bottom up, working through PPE with depreciation schedules, working capital accounts with their turnover ratios, debt with its interest and repayment schedule. The cash flow statement is where everything reconciles, and that's also where most models break. If your balance sheet doesn't balance after you link everything, the cash and debt plug is your signal that something is misconnected. I spent two weeks once fixing a model a candidate had submitted as a take-home exercise. The revenue numbers were right, the net income was right, but they hadn't linked depreciation to the accumulated depreciation line on the balance sheet, so the whole thing drifted apart. Point is, the connections matter more than any single formula.
Excel questions will come up, probably on a live screen. They might ask you to clean a messy dataset, build a pivot table, or write a formula on the spot. VLOOKUP and XLOOKUP are table stakes. INDEX MATCH is still useful to know because some companies haven't upgraded their Excel versions. SUMIFS, COUNTIFS, and basic data validation matter more than people realize. The candidates who get tripped up are the ones who try to do everything with manual lookups instead of building a clean structure with helper columns. If they give you a raw sales dataset and ask you to find total revenue by product category in under five minutes, they're watching how you approach the problem, not just whether you get the right number. Open a fresh sheet, label your inputs, use structured references if you can, and show your work. Speed comes from clean setup, not from frantic typing. Then there are the valuation questions. What's the difference between equity value and enterprise value? Equity value is the market cap plus minority interest and preferred stock. Enterprise value is equity value plus total debt minus cash and cash equivalents. Enterprise value represents the actual cost to acquire the entire business, while equity value is just what shares cost. This matters because valuation multiples like EV/EBITDA and EV/Revenue use enterprise value, not equity value. Mixing those up in an interview is an easy way to look like you've never done a real valuation. When would you use DCF versus comparable company analysis? DCF is best when you have a company with stable, predictable cash flows and you can reasonably forecast them for five to ten years. Comparable company analysis works better when you're valuing a company in a mature industry with lots of public peers, or when the target company doesn't have positive free cash flow yet. The problem with DCF is that small changes in your discount rate or terminal value assumption can swing the valuation by twenty to thirty percent. I learned this the hard way during an internship when my model valued a mid-cap industrials company at $42 per share using a 9.5 percent WACC and terminal growth of 2.5 percent. When I bumped the WACC to 10.5 percent, the price dropped to $34. That's a nine dollar difference from a single percentage point change, and a hiring manager who asks you follow-up questions about sensitivity is testing whether you understand that limitation rather than treating your model output as gospel.
Get the Full Details

Now let's talk about the questions that catch people off guard. Tell me about a time you made a mistake in a financial model. This is behavioral framing but it's also a technical screening disguised as soft skills. Pick an actual mistake you made, not a humblebrag about working too hard. I once built a depreciation schedule that assumed straight-line over ten years for a fleet of delivery vehicles when the company actually usedMACRS accelerated depreciation. My expense numbers were close enough that no one caught it in a quick review, but the tax shield timing was wrong and it threw off the cash flow projection by about eight percent over the model's life. The fix was to pull the actual depreciation schedules from the prior year tax return and rebuild the PPE rollforward. What the interviewer wants to hear is that you caught it, you fixed it, and you put a process in place to prevent it from happening again. Maybe you started running a sensitivity check on key assumptions or creating a model audit trail. Something concrete. How do you stay current on financial markets and economic trends? This isn't fluff. They genuinely want to know whether you read anything outside of class. Mentioning the Wall Street Journal, Financial Times, or even a solid podcast like Odd Lots or Money Stuff shows you have baseline awareness. If you follow a specific sector or have a thesis about something, mention that too. I've seen candidates blank on this and then ramble about nothing specific, which is worse than just saying you read the financial sections of a mainstream paper every morning. There are some counter-intuitive things about these interviews that aren't obvious until you sit on the other side. One is that being too polished can hurt you. Candidates who recite textbook answers verbatim often score lower than the ones who think out loud and correct themselves mid-sentence. The second is that questions about LBOs and leveraged buyouts sometimes come up for entry level roles at private equity adjacent shops, even though you won't be building LBO models for years. They're testing whether you've done any self-directed learning beyond your curriculum. You don't need to be an expert, but knowing the basic mechanics of how leverage amplifies returns and what driving a transaction looks like will set you apart from people who only know DCF and comparables.
The other thing people miss is that case studies or take-home exercises are often more important than the live interview. A forty-five minute technical screen might feel decisive, but the take-home model they send you a week before often carries equal or more weight in the final decision. I've hired analysts where the person who bombed the live interview had the cleanest, most logical take-home model by a wide margin. Structure your take-home work with clear input sections, labeled assumptions, and a summary sheet that pulls the key outputs together. Put a one-page memo at the front explaining your methodology and any limitations. That memo alone will put you ahead of most other candidates. One more practical note about the Excel portion. Some companies will give you a broken spreadsheet and ask you to fix it. Others will have you build from a blank file. In both cases, formatting doesn't matter nearly as much as logic. Blue numbers for hardcodes, black for formulas, clear labels, no merged cells. Merged cells destroy pivot tables and break macros, and it's embarrassing when a candidate does that in an interview setting. Also, avoid nesting five levels of IF statements when a SUMIFS or XLOOKUP would do it in one line. Clean formulas read like prose. Messy ones look like you're trying to prove something. If you're preparing for these interviews, start with the basics until they're automatic. Three statement connections, NPV versus IRR, EV versus equity value, basic valuation methods, and Excel fluency. Then move to applications. Build a simple DCF model for a company you know. Recreate a three-statement model from a public 10-K. Time yourself on Excel exercises. The gap between candidates who pass and candidates who don't isn't usually intelligence. It's whether they've actually touched a financial model before walking into the room.