Getting Your Product Across Borders Without Losing Your Mind
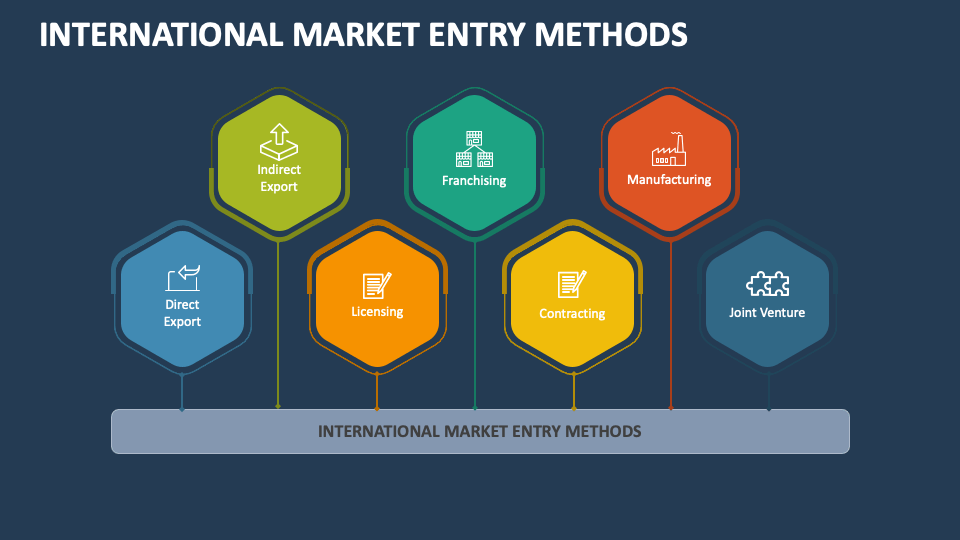
The first time I tried to figure out entry strategies for international markets, I assumed picking the right model was the hard part. It isn't. The hard part is realizing three months into execution that your entire assumption about the target market was built on a government whitepaper that was two years outdated and written by a consultant who'd never left the capital. I learned this the dumb way with a consumer electronics client entering Vietnam. We went full direct subsidiary, set up operations in Ho Chi Minh City, hired locally, and spent about fourteen months before figuring out that the real gatekeepers weren't regulatory — they were distribution networks controlled by three family-owned conglomerates who'd rather sell a competing product than risk their relationship with the Chinese manufacturers already supplying them. That's the thing nobody tells you about market entry: the textbook framework is only useful once you stop treating it as a decision tree and start treating it as a set of levers you can adjust based on what you're actually willing to lose. The five main models — exporting, licensing, joint ventures, franchising, and wholly-owned subsidiaries — exist in every intro course, but the real question is which combination of factors actually forces your hand.
Entry Strategies For International Markets: What Actually Moves the Needle
Here's what my team and I see over and over. Companies pick their entry mode based on product characteristics. Heavy, complex hardware leans toward direct sales or joint ventures. Software leans toward licensing or digital distribution. This logic is roughly correct but dramatically incomplete. The second variable that actually determines everything is how much institutional trust exists in the target market. If you're entering Germany, Japan, or Canada from another developed economy, the friction is low. You can go direct and move fast. If you're entering Vietnam, Nigeria, or Peru, the trust gap means you will spend three to five times longer on setup than the spreadsheets predict, and your entry mode needs to account for that from day one. I've seen companies run financial models that factor in shipping costs, tariffs, and local staffing but completely omit the cost of relationship-building. In markets where guanxi in China or compadrazgo networks in Latin America matter, skipping the joint venture or local partnership angle isn't conservative — it's reckless. Not because the model is morally superior, but because the timeline extensions will sink you regardless of which structure you picked on paper. There's also a common misconception that licensing is the low-risk option. It's low capital risk. It's not low strategic risk. When I worked on a software localization play for the Middle East, we licensed to a regional distributor who then created a forked version of our product, registered it under their own trademark in three Gulf markets, and started selling it to our prospective enterprise clients. We had contractual recourse on paper. In practice, enforcing it through local courts cost more than the revenue at stake and took eighteen months. Licensing works when the licensee has strong brand incentives to protect your IP. It doesn't work when they see your product as a commodity to be replicated. The difference usually comes down to whether you're the market leader or a challenger in that geography.
Another thing that trips people up is the sequencing assumption. The textbook approach says start with exporting, then graduate to licensing, then joint ventures, then subsidiaries. In reality, many companies skip straight to subsidiaries because they have the capital and the confidence, then regret it when they don't have the local intelligence to back it up. I once consulted for a Finnish industrial equipment manufacturer that opened a branch office in Saudi Arabia within six months of deciding to enter the region. They had the license, the bank account, the lease. They didn't have a single meaningful relationship with a procurement decision-maker. Revenue in year one was approximately zero. By year three, after pivoting to a joint venture with a properly vetted local partner who had existing tenders in the pipeline, they hit about 4.2 million euros in annual revenue. The product didn't change. The market didn't change. Only the entry structure changed. Franchising sits in an odd middle ground that's often overlooked. It works exceptionally well for service businesses with standardized operations — food, hospitality, education, fitness. It's nearly impossible for product businesses unless the product itself is highly adaptable to local tastes, which brings me to a point that matters more than most people realize: the adaptation question. You need to answer it before you pick your entry mode, not after. Some products require zero adaptation. Think industrial components or B2B software with universal workflows. Others require localization at the legal, cultural, and technical levels simultaneously. A payment processing platform entering India needs to integrate with UPI, comply with RBI regulations, support local language interfaces, and navigate state-level banking rules. That's not a licensing scenario. That's a locally embedded operation scenario, and the entry strategy should reflect that complexity from the start rather than pretending it'll sort itself out once you're there. Let me be blunt about where these strategies fail. Joint ventures carry the highest hidden tax in my experience. Not financial — operational. Decision-making slows to a crawl because every choice requires alignment between parties with different incentives, different risk tolerances, and often different concepts of what "done" means. I've watched JVs where a simple pricing adjustment took four months because the local partner's management structure required sign-offs from three layers of ownership before anything moved. If you go the JV route, build in escalation mechanisms and clear governance documents from the beginning. Don't assume good intentions will override structural friction.
Get the Full Details

Wholly-owned subsidiaries fail when the market is small enough that the fixed costs of independence eat your margins before you reach scale. There's a threshold — usually around 50 to 100 million in addressable market size — below which going full subsidiary is mathematically irrational unless you're playing a long game measured in seven to ten years, not three to five. Most companies misjudge this because they conflate market potential with market accessibility. Just because a country has 200 million people doesn't mean 200 million people are your customers. It usually means fifty thousand are, and those fifty thousand might be reachable through a distributor who already owns the relationship. Exporting through agents or distributors is the easiest mode to start with and the hardest to scale through. You'll hit a ceiling where your growth depends entirely on someone else's priorities, and by the time you realize that, you've spent years building a channel you don't control. The workaround I've used successfully is to structure distributor agreements with territorial exclusivity thresholds tied to performance milestones. If they hit the numbers, they keep exclusivity. If they don't, you reserve the right to open parallel channels or take direct sales in underserved regions. It's not elegant. It creates tension. But it prevents the common trap of handing a distributor an entire country and waiting three years to discover they've been nurturing the market at the pace comfortable for their existing portfolio, not ambitious enough for yours. There's also the regulatory layer that kills deals before they start. Export controls, sanctions screening, data localization requirements, local content rules. These aren't optional checkboxes. I had a client who was clear to launch in Brazil until the CNPJ registration process revealed that their corporate structure triggered a mandatory local board requirement under CVM rules. They'd already signed leases and hired staff in São Paulo. Fixing the structure retroactively added nine weeks and a legal bill that exceeded their first quarter's projected revenue. Always run the compliance pass before the commercial pass. Not after.
The counter-intuitive insight that saves the most money is this: your entry strategy should be designed to be changed. Not revised. Changed. The markets you're entering will reveal information that no amount of desk research can surface, and the model you commit to on paper will look different once you're operating in the weeds. Build optionality into your initial approach. Use shorter initial contracts. Negotiate termination clauses that aren't punitive. Keep enough capital reserved that you can pivot from licensing to direct within six months if the data demands it. The companies that get squeezed are the ones that committed fully to a path that turned out to be wrong.