epsilon and delta limits
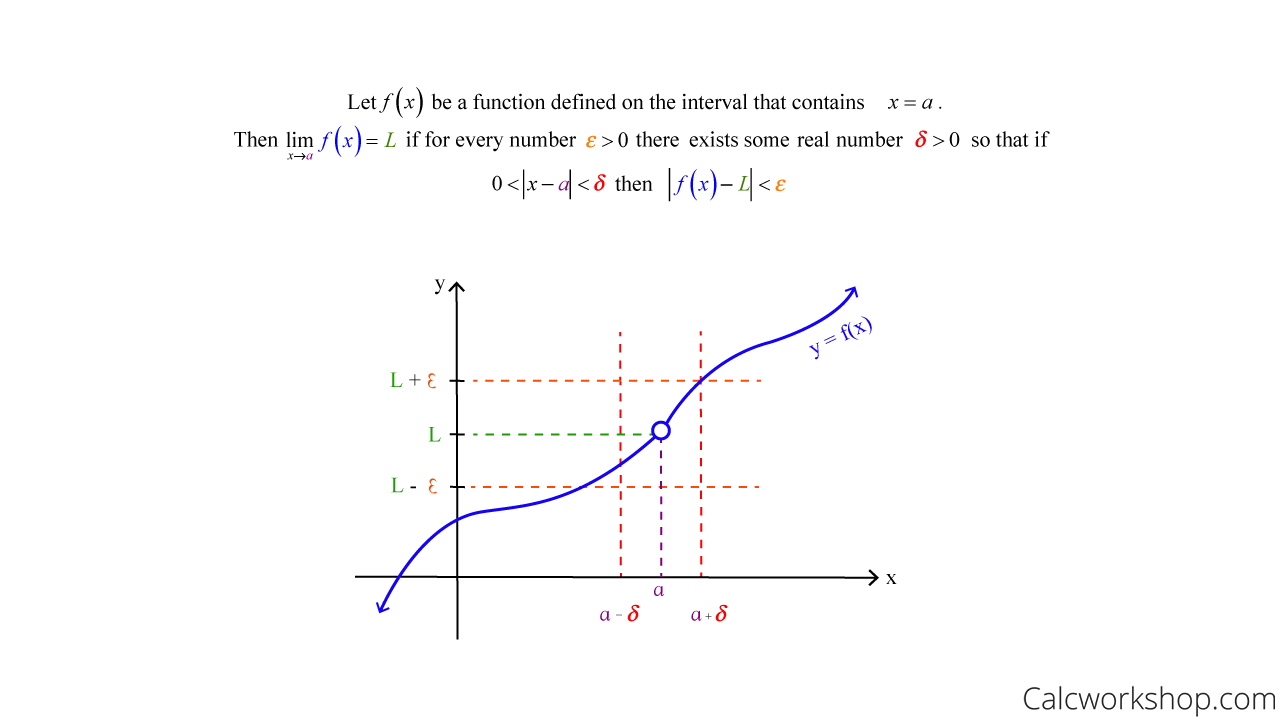
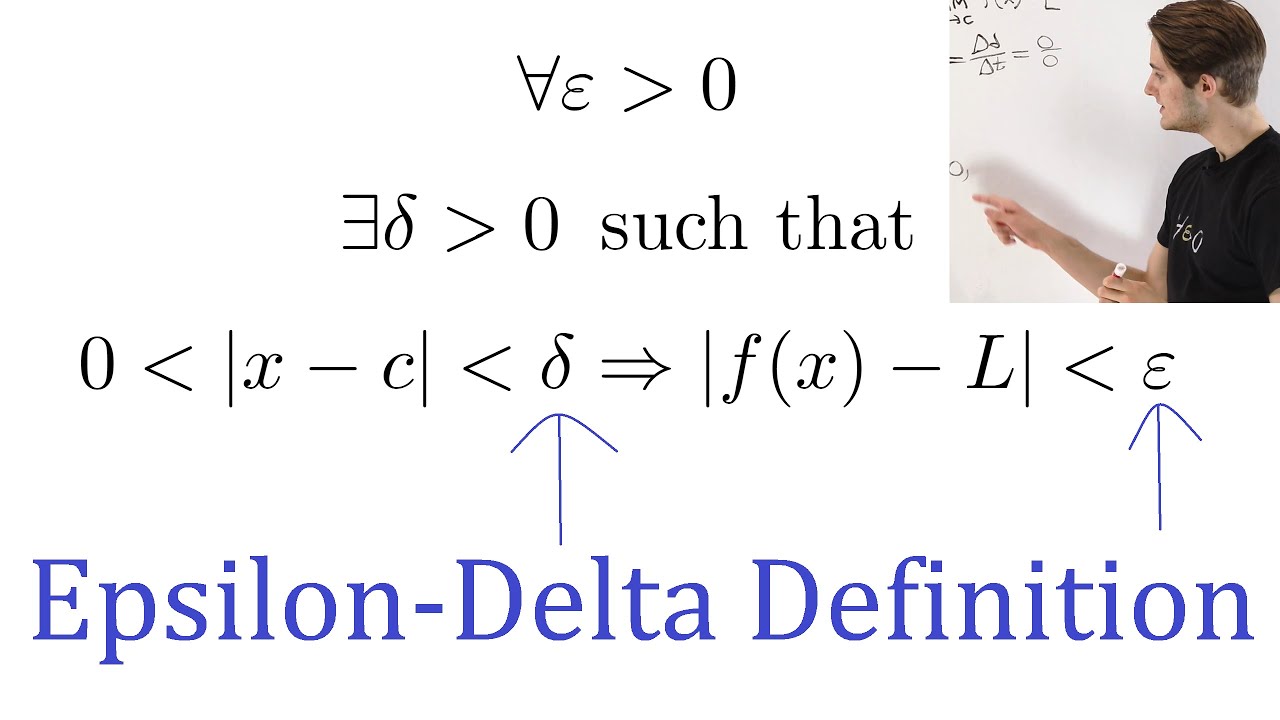
The epsilon-delta definition is the standard way we prove statements about limits rigorously. You don't need it for routine calculus work—derivatives, integrals, series tests—but if you're taking a real analysis course or debugging a numerical method that relies on limit claims, it's the foundation everything else sits on. Here's the definition: For a function f(x), we say the limit as x approaches c equals L if, for every positive epsilon, there exists a positive delta such that whenever 0 < |x - c| < delta, we have |f(x) - L|
epsilon. The way I actually use this is backward from how textbooks present it. I start with the epsilon, then work out what delta has to satisfy the inequality, then verify that derivation holds. Most students try to go forward from delta to epsilon and get lost.
Finding the right delta for Epsilon And Delta Limits
Take a concrete example. Prove that the limit as x approaches 3 of 2x minus 5 equals 1. You pick an arbitrary epsilon, which is just a positive number. Then you need to find a delta that makes |2x - 5 - 1| less than epsilon whenever |x - 3| is less than delta. Simplify the left side: |2x - 6|, which is 2 times |x - 3|. So if you choose delta to be epsilon over 2, the inequality works out cleanly. That's the general pattern for linear functions—delta is epsilon divided by the slope coefficient. Things get messier with quadratics. I ran into this when I was checking convergence bounds for a numerical algorithm last year. We needed to prove that a certain function approached its limit uniformly over an interval, and the epsilon-delta choice depended on where in the domain we were. For f(x) = x squared near x = 2, you get |x squared - 4| equals |x - 2| times |x + 2|. The factor |x + 2| isn't constant—it grows as x moves away from 2. So your delta has to account for that. I bounded |x + 2| by assuming delta is at most 1, which keeps x in the range from 1 to 3, making |x + 2| at most 5. Then delta becomes epsilon over 5, capped at 1. That intersection—minimum of 1 and epsilon over 5—is what actually works. This bounding step is the part most people skip. Textbooks often just hand you the delta without showing how it was derived, which makes it feel like magic instead of algebra. The actual process is constraint management: isolate the |x - c| term, bound any remaining x-dependent factors by restricting delta to a small preliminary value, then solve for the final delta.
There's a common pitfall that costs students points regularly. When you restrict delta to be at most 1 or some other constant, you have to remember that the final delta is the minimum of your bound and your computed value, not just the computed value alone. If epsilon is large, say 10, then epsilon over 5 equals 2, but you still need delta to be at most 1 because that was your initial restriction for the bound to hold. Using delta equal to 2 without the cap breaks the proof. Another thing that trips people up: the definition requires the inequality to hold for every positive epsilon, not just some epsilon. Proving it for one specific epsilon doesn't count. You have to show the mechanism works for an arbitrary epsilon, which is why the proof always starts with "Let epsilon be greater than 0." Quotient functions add another layer. Consider the limit as x approaches 1 of x over x plus 1 equals one half. Here you deal with |x over x plus 1 minus one half|, which simplifies to |x minus 1| over |2x plus 2|. The denominator varies with x, so again you bound it. If delta is at most one half, then x is between one half and three halves, and |2x plus 2| is between 3 and 5. You use the lower bound of 3 to get delta equals three epsilon over 2, capped at one half.
Get the Full Details

One counter-intuitive point worth noting: delta doesn't have to be unique. Any smaller positive delta also works. The definition only requires existence of at least one delta, not a specific one. This matters because sometimes you can find a looser delta that's easier to work with in a larger proof, even though a tighter one is available. The real limitation of epsilon-delta proofs is that they don't scale well to multivariable calculus or metric spaces without significant adaptation. In several variables, you're dealing with norms and spherical neighborhoods instead of intervals, and the bounding strategies become more involved. If you're moving into analysis beyond single-variable calculus, I'd recommend working through metric space definitions early rather than trying to map the one-variable intuition directly. For practical purposes outside of a math course, you rarely need to construct these proofs by hand. Symbolic computation tools can verify them, and for applied work you generally rely on theorems that were already proven using epsilon-delta arguments. But understanding the mechanics helps you spot when a limit claim might be shaky, especially with piecewise functions or discontinuous constructions where textbook examples rarely venture.