Market Equilibrium Explained Without the Textbook Fluff
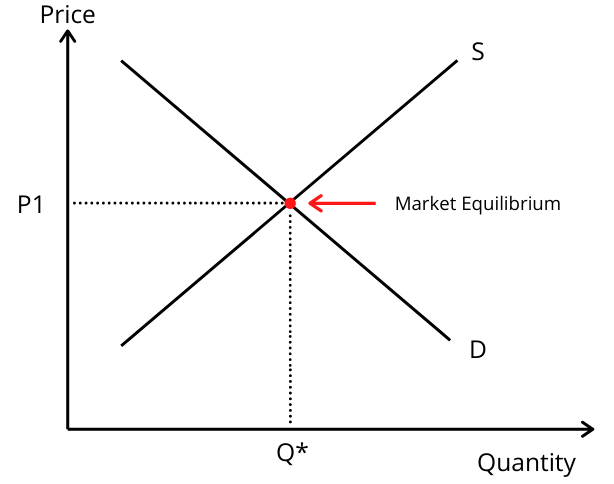
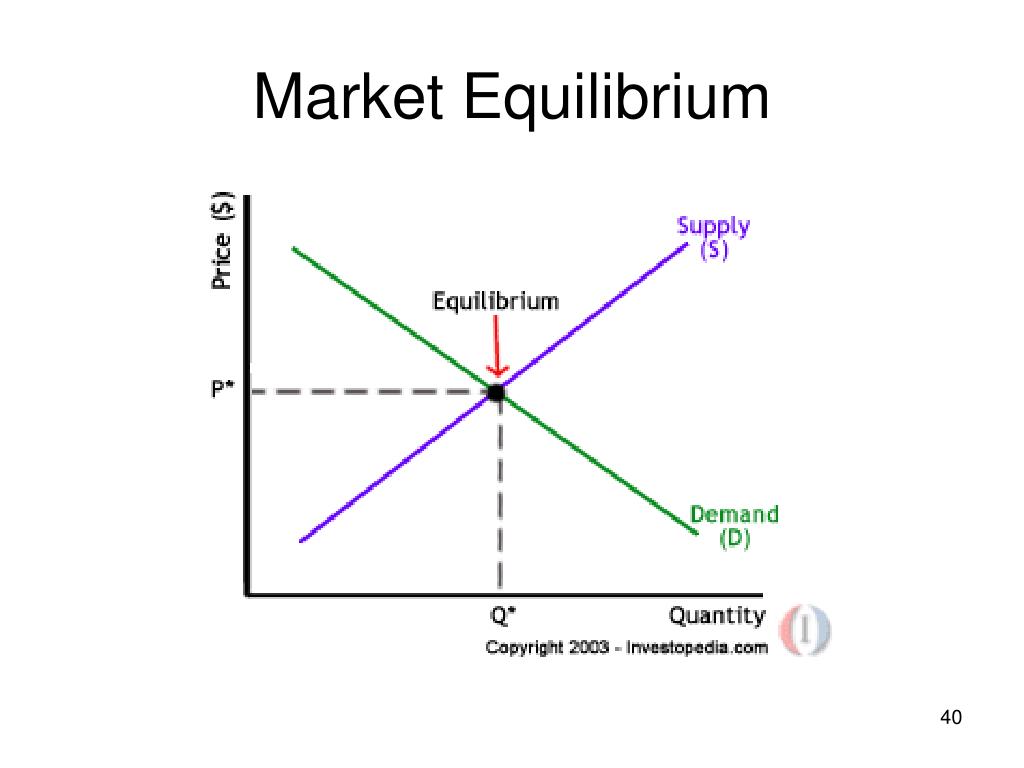
Most people learn about supply and demand curves in an intro econ class and think they understand how markets work. They don't. The gap between what happens in a textbook diagram and what actually happens in a live market is where money is made or lost. Let's talk about what equilibrium really means and how to use the concept instead of just drawing curves on a whiteboard. At its core, equilibrium is the price point where the quantity of a good or service that producers want to sell exactly matches the quantity that consumers want to buy. Below that price, you have a shortage — buyers compete, prices tend to rise. Above it, you have a surplus — sellers compete, prices tend to fall. Simple enough. The part people skip is figuring out where that intersection actually sits in any given moment. Let me give you a concrete example. Say you're tracking the market for a particular commodity — let's use crude oil futures contracts. The supply curve for crude shifts when there's a disruption in production, like an OPEC announcement or a hurricane in the Gulf. The demand curve shifts when economic data changes — manufacturing output, travel demand, geopolitical tensions affecting supply routes. The equilibrium price is wherever those two curves cross at any given moment. But here's the thing: neither curve stays still. They move constantly, and the market price you see on your screen is usually slightly ahead of or behind the actual equilibrium depending on how fast information flows.
I spent years working with commodity spreads and one specific edge case almost cost my team six figures. We were trading the crack spread — the difference between crude oil prices and refined product prices like gasoline and diesel. The theoretical equilibrium for that spread was clearly defined by refining margins, seasonal demand patterns, and storage costs. But during a particularly volatile quarter in 2019, we noticed the spread was trading at levels that suggested massive arbitrage opportunity. The equilibrium price implied you could buy crude, refine it, and sell the products for a guaranteed profit of over $4 per barrel. We ran the numbers three times. Something was wrong with the model. The problem wasn't the equilibrium calculation. It was that the market had a structural bottleneck — refinery capacity was constrained in a way that the theoretical model didn't account for. You could theoretically buy crude and refine it at profit, but the actual refineries that would process it were already running at maximum utilization with scheduled maintenance lining up for months. The equilibrium existed in theory but not in practice because physical constraints prevented the market from reaching it. We almost entered the trade and then I insisted on checking refinery operating rates and maintenance schedules before pulling the trigger. That due diligence saved us from putting capital into a position where the arbitrage couldn't actually execute. The equilibrium was real. The ability to capture it wasn't.
Equilibrium In The Market: How to Actually Find It
Here's the practical method I use, not the academic one. First, identify the market you're analyzing and define the specific good or service — not the broad category. "Oil" is too vague. "West Texas Intermediate crude futures, front month" is specific. The narrower your definition, the more accurate your equilibrium estimate will be. Second, map the supply side. Look at production costs, capacity constraints, inventory levels, and the number of active suppliers. I pull data from production reports, EIA publications for energy markets, customs data for traded goods, and proprietary dealer networks when available. The supply curve isn't a single line — it's a range of prices at which different quantities are willing to be supplied. At $60 per barrel, some producers break even. At $80, more producers enter. At $100, marginal producers who were previously idle start running again. Each price point has a corresponding quantity supplied. Third, map the demand side. Consumer preferences, income levels, substitute goods prices, and seasonality all shift demand. For agricultural commodities, weather is a massive demand driver because it affects both the supply of alternatives and the demand for feed stocks. For technology products, substitute pricing from competing platforms moves demand faster than anything else. You need current data, not trailing data. A demand curve based on last quarter's numbers is already wrong if the market has moved.
Get the Full Details
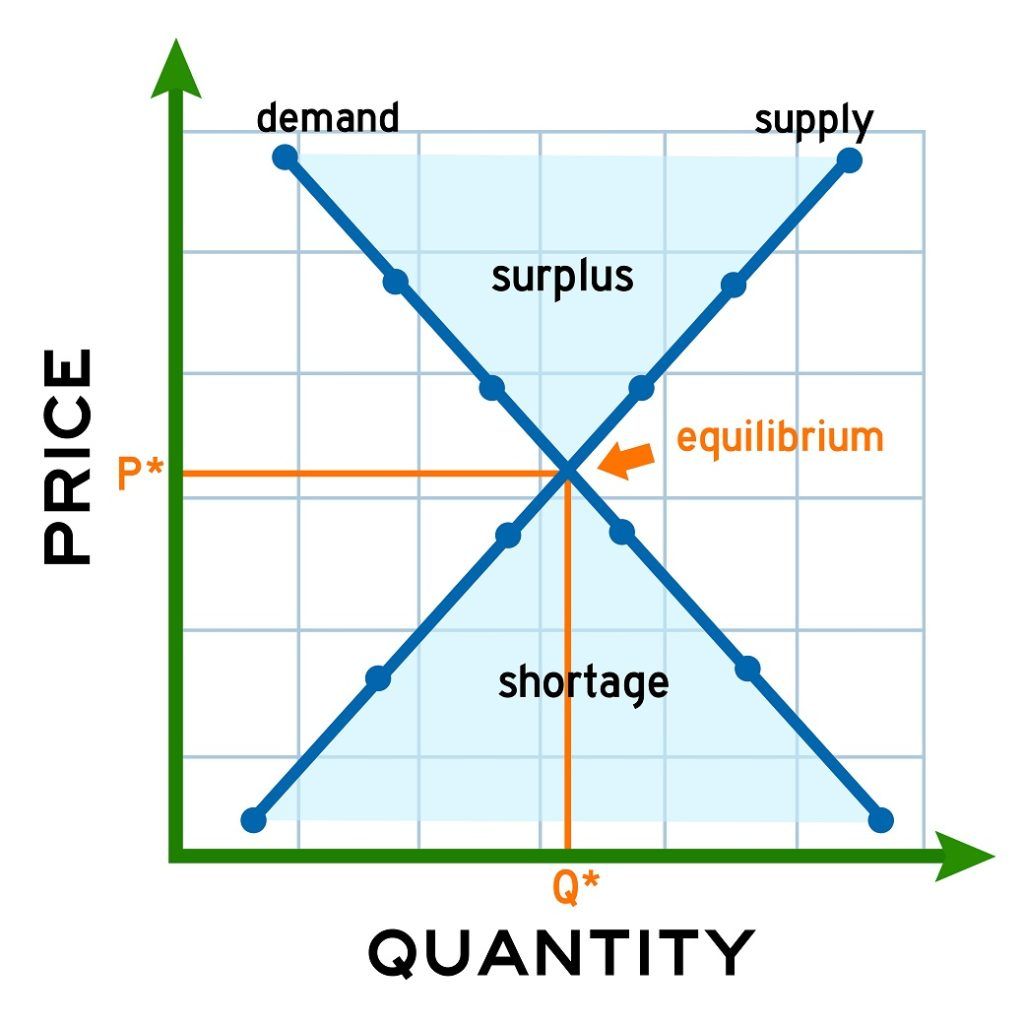
Fourth, find the intersection. This is where it gets messy in practice because real data is noisy. Supply and demand estimates come from different sources with different methodologies and time lags. I typically run multiple equilibrium calculations using different data sources and take a weighted average, giving more weight to the sources with the shortest lag and highest credibility for that specific market. The equilibrium price isn't a single number — it's a range, and the width of that range tells you how uncertain you should be. Here's a counter-intuitive insight that beginners consistently miss: equilibrium price stability doesn't mean market prices are stable. In many markets, especially financial ones, the equilibrium itself changes faster than prices can adjust to it. I've seen crypto derivatives markets where the theoretical equilibrium price was being recalculated every few seconds due to volatility, and the actual market price was perpetually lagging behind. The equilibrium wasn't a target the market was converging toward — it was a moving target that the market could never quite catch. In those situations, treating equilibrium as a fixed reference point is a mistake. You need to model the rate of change, not just the position. Another thing nobody teaches: disequilibrium can be persistent and profitable. Markets don't always converge. When there are barriers to entry, regulatory constraints, information asymmetries, or transaction costs that are large relative to the potential gain, the market can sit in a disequilibrium state for extended periods. I've worked with several markets where the gap between equilibrium price and actual market price was $2 to $5 per unit for months at a time. The equilibrium existed. The mechanism to close the gap didn't. That's not a failure of the concept — it's a feature of how real markets operate.
Now let me be straight about the limitations. Equilibrium analysis breaks down completely in markets with extreme illiquidity, where the bid-ask spread alone is larger than any theoretical equilibrium adjustment. It's useless in monopsony or monopoly situations where a single buyer or seller controls pricing. It doesn't account well for behavioral factors — panic selling, herd behavior, and speculative bubbles can push prices far from equilibrium for extended periods, and there's no equation that reliably predicts when or if they'll return. In emerging markets with unreliable data, your equilibrium calculation is only as good as your worst data point, and those markets tend to have the worst data. If you're working in a market where equilibrium analysis seems to consistently fail, check whether the issue is with your model or with the model itself. Most of the time it's the model. But in structured markets with clear supply-demand drivers and reasonable liquidity, finding the equilibrium gives you a reference point that separate from short-term noise. That's the entire point. You're not trying to predict the next tick. You're trying to understand where the market should be relative to where it actually is right now. The difference between those two points is your edge. I've built a lightweight equilibrium calculator that takes supply and demand parameters — production costs, capacity, inventory, consumption rates, substitute prices, seasonal adjustments — and outputs an equilibrium range with confidence intervals. It's not fancy. It runs on a spreadsheet with some basic optimization routines. The version I use internally is a Python script that processes about 40 data points across 6 different variables for each market I track, running in roughly 3 seconds per iteration. It doesn't replace judgment. It replaces guesswork. Where I used to spend a morning manually cross-referencing supply reports and demand forecasts to estimate where a market should price, I now get a baseline equilibrium in under a minute and then spend my time on what actually matters — validating the inputs and understanding why the market is where it is relative to the model.
The real skill isn't calculating equilibrium. It's knowing when the calculation matters and when it doesn't. In liquid, transparent markets with stable fundamentals, equilibrium analysis is genuinely useful for identifying mispricings. In opaque, illiquid, or structurally disrupted markets, it's a nice exercise that won't help you trade. The best practitioners I know treat equilibrium as one data point among many, not as a holy grail. It tells you where the market should be. Whether it gets there, how long it takes, and whether you can profit from the gap are entirely separate questions.