What closing costs actually look like for a seller
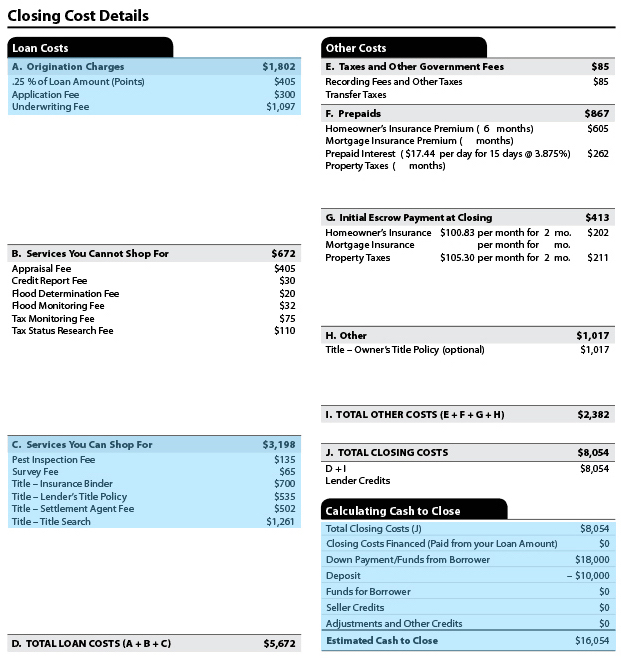
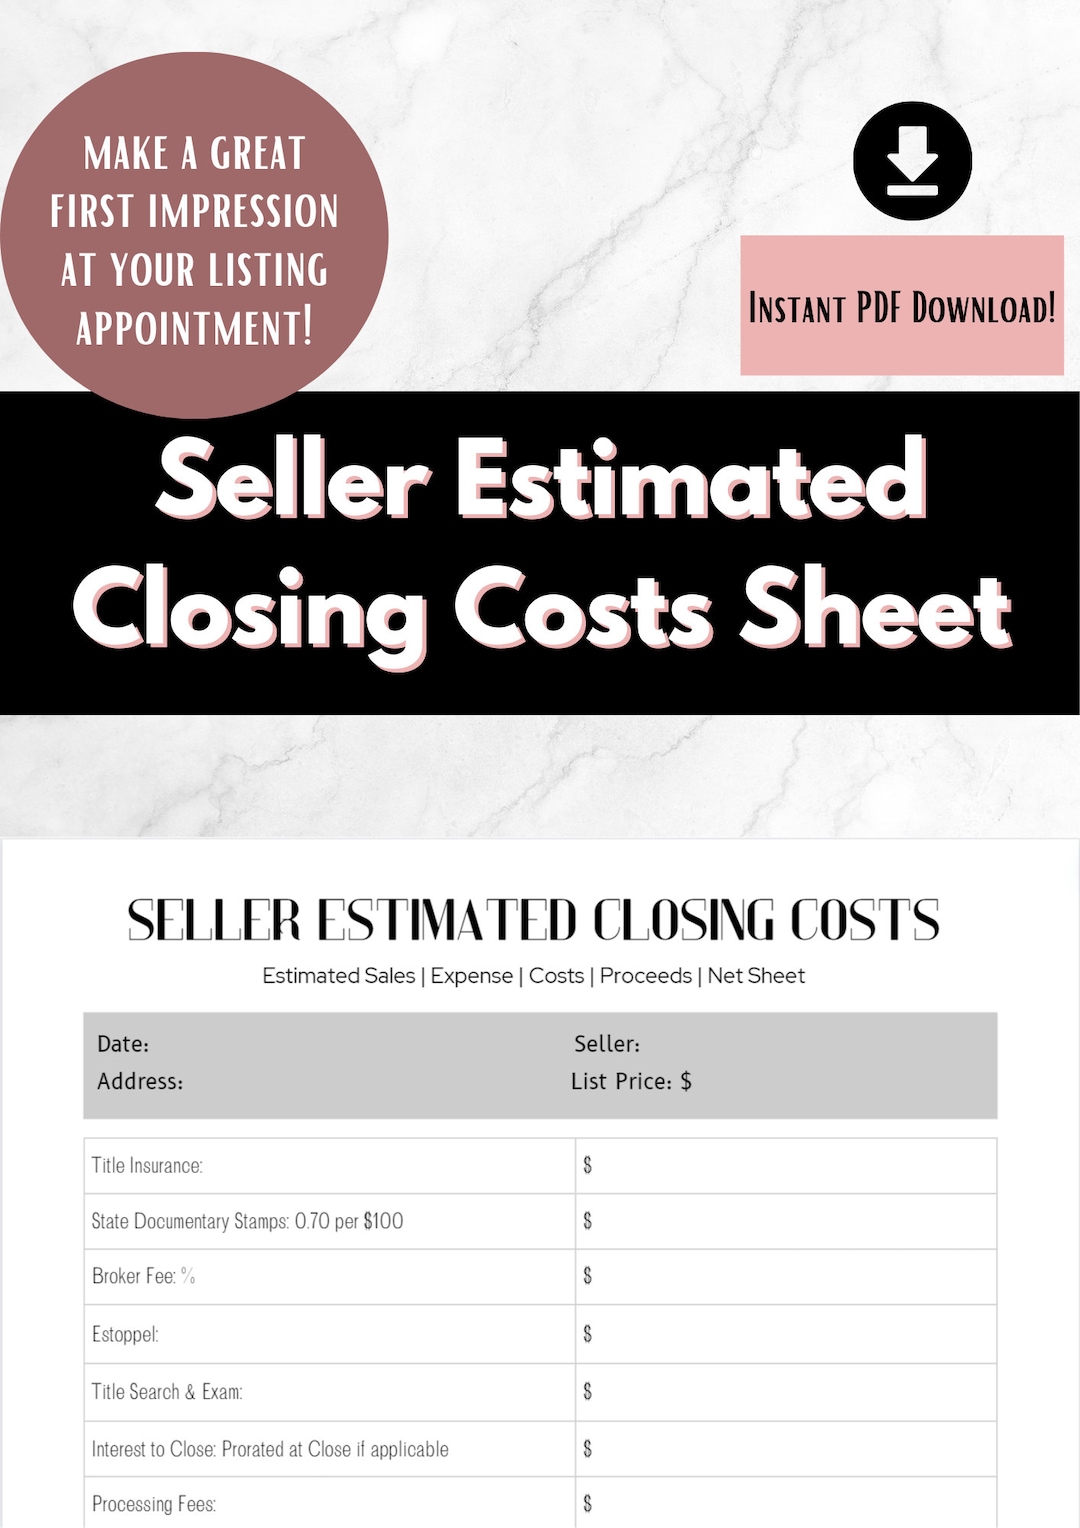
Seller closing costs run roughly 6% to 11% of the sale price in most markets. That includes the agent commission, title insurance, transfer taxes, and a handful of smaller line items that people routinely forget about until the settlement statement shows up. The range exists because every jurisdiction taxes differently and commissions are negotiable, not fixed. I have been processing transactions for a long time, and the single most common mistake I see is sellers budgeting based on the commission alone. That number is usually 5% to 6%, but the rest of the costs are where people get surprised. Transfer taxes can add another 1% to 3%. Title insurance varies wildly by state. Recording fees, HOA payout, home warranty, and a few other pieces sit on the bottom line and eat into net proceeds.
How to Estimate Closing Costs For Seller accurately
Start with the gross sale price and work downward. The standard process takes about 15 minutes if you have the county tax tables open. First, pull your local transfer tax schedule. Every county has one, and it is usually a flat dollar amount per thousand or a percentage tier. Next, look up the title insurance premium table for your state. Some states charge by rate, others use a set schedule. Then subtract the expected commission, which depends on your listing agreement. After that, add the estimated title policy, recording fees, escrow or settlement fees, and any HOA transfer charges. The final step is the prorated items. Property taxes, HOA dues, and rent if the buyer occupies part of the unit all get prorated through the closing date. That part is usually handled by the title company, but it shifts the number slightly and it matters if you have a high annual tax bill. One tool I rely on is the ATTOM or LocalInfoSeller closing cost calculator, which pulls county-level data automatically. Another option is the spreadsheet from the National Association of Realtors, though it tends to understate transfer taxes in certain states. If you want a downloadable reference, the HUD-1 comparison sheets from the CFPB are useful for learning what each line means, even though the HUD-1 itself is retired for most transactions.
Where the estimate goes wrong in practice
The biggest gap between the rough number and the actual settlement statement comes from prorations and seller concessions. A standard estimate does not capture the exact tax bill for your county, especially if your locality uses an unusual assessment cycle. The same issue shows up with mello-roos, special district fees, or utility reimbursements in planned communities. These are easy to miss on a quick calculation and hard to recover once the closing happens. I ran into a specific problem last year with a seller in a coastal county where the transfer tax is layered. There is the state deed transfer tax, the county excise tax, and a municipal surcharge that only applies inside city limits. The online calculators I had access to included the state and county portions but missed the municipal add-on entirely. The final gap was about $1,800 on a $620,000 sale. The workaround was simple: I pulled the exact municipal code for that city, confirmed the per-thousand rate, and recalculated before the listing went live. That saved the seller from having to cover the difference at closing or renegotiate terms.
Get the Full Details

Commission is not the only big number
Buyer-agent commissions are still part of seller closing costs under the current model, even after the NAR settlement changes. The structure varies now because offers can include cooperation compensation, but the cost often lands on the seller side anyway through negotiation. A realistic range for total agent-related payouts is 5% to 6%, with the seller sometimes absorbing the buyer agent portion entirely. Title insurance is another line item that people misunderstand. The owner's policy is optional for the seller in most places, but the lender's policy is mandatory if the buyer is financing. Sellers frequently pay for the owner's policy as part of the deal, which adds a one-time premium that can range from $500 to $2,000 depending on the purchase price and state. In some states, the seller pays nothing for title insurance at all. Check your local custom before assuming it is a universal cost. Recording fees, transfer stamps, and escrow or settlement fees are usually small but predictable. Recording runs about $50 to $250 depending on the county. Transfer stamps vary from zero in states without them to a few hundred in high-tax jurisdictions. Escrow fees, when they exist, typically fall between $500 and $1,500 for a mid-priced home.
Practical numbers you can use as a starting point
For a $400,000 home in a typical suburban county, expect roughly: That puts the total near $24,000 to $33,000 before proration adjustments. On a $1,200,000 property in a high-tax metro, the same line items scale up, and transfer taxes alone can exceed $12,000. Commissions also scale, so the percentage stays similar but the absolute dollar gap grows fast. A rough percentage estimate is not reliable for luxury properties, land sales, or transactions involving unusual financing. The margin of error widens significantly when the sale price deviates far from the median in your market. Transfer tax brackets often change at specific thresholds, and a small price shift can push the property into a higher bracket. That is a discrete jump, not a smooth curve, so the estimate becomes less accurate near those breakpoints.
Cash transactions also behave differently. When there is no lender, there is no lender's title policy, no appraisal contingency, and no loan-related fees. The settlement statement shrinks, which makes a percentage-based estimate overstate the actual cost. In those cases, pull a real settlement statement from a recent comparable sale in the same county instead of relying on the rule-of-thumb calculator.
What to do before you list
Get a preliminary closing cost estimate from your title company or settlement agent. They will run the exact tax rates, confirm the local transfer stamp schedule, and flag any special assessments or HOA requirements that affect the statement. That step takes about 10 minutes and eliminates the guesswork. After that, adjust your listing price expectation based on the real net proceeds, not the gross sale price. Most sellers focus on what they receive, but the estimate only matters when it is reconciled with the actual settlement figure. If you want a downloadable template for tracking these costs across multiple transactions, I use a simple three-sheet workbook with a input tab for sale price, a county rate lookup tab, and a net proceeds projection tab. I keep it in Google Sheets and share it with my clients before we set the list price. It cuts the back-and-forth about out-of-pocket costs from several emails down to a single document they can review on their own.
Estimate Closing Costs For Seller remains the right first step, but the details decide the outcome
The percentage range gets you in the right neighborhood. The county tax table, the municipality code, and the commission structure get you to the actual number. Without both pieces, the estimate is a placeholder, not a plan. That is the difference between walking into closing surprised and walking in knowing exactly what hits your account.