How to Actually Figure Out What You'll Walk Away With
The math behind Estimate Proceeds From Home Sale is technically simple, but the devil is in the details that most sellers ignore until they're three days from closing. You take the expected sale price, subtract the commission, subtract the payoff on your existing mortgage, subtract transfer taxes and closing costs, and whatever's left is your approximate proceeds. That's the skeleton. The flesh is where people get burned. I went through this process myself when selling a rental property about five years ago. I ran the numbers using a standard calculator and came out to roughly $160,000 in proceeds. Turns out, the HOA had a pending special assessment of $12,000 that wasn't reflected in any of the standard closing cost templates. It showed up on the settlement statement and cut my actual proceeds down to $147,000. After that, I started pulling HOA financials and county records before listing, not after. It takes about twenty minutes and has saved me from two surprise deductions since then.
Understanding Estimate Proceeds From Home Sale in Practice
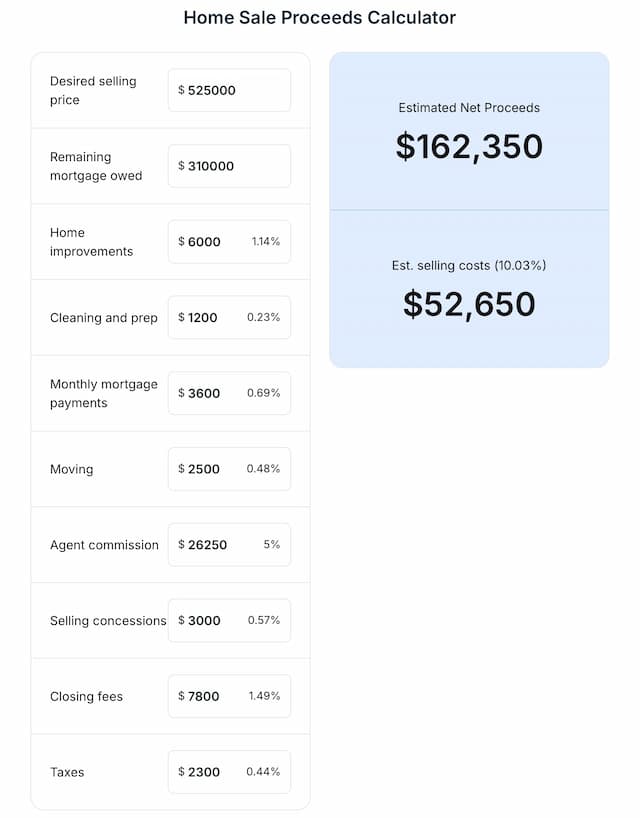
Let me walk through a real example. Say your home sells for $425,000. In most markets, the combined commission for buyer's agent and seller's agent runs about 5% to 6%, so that's roughly $21,250 to $25,500 gone. Your existing mortgage balance is $290,000. Closing costs including title insurance, escrow fees, recording fees, and prorated property taxes typically run another $8,000 to $12,000 depending on your location. That leaves you around $109,000 to $114,000, give or take. But here's where the standard calculation falls apart. Transfer taxes vary wildly by jurisdiction. In some counties they're split between buyer and seller. In others the seller eats the full amount. In certain cities there's a municipal surcharge on top of that. A $425,000 sale in a high-tax municipality could see an extra $3,000 to $6,000 in transfer taxes that a generic calculator won't account for. You need to check your county recorder's office website or ask a local agent for the exact rate before you do any math. Another detail people routinely miss: buyer concessions. If the buyer negotiates a $5,000 credit toward their closing costs, that comes directly out of your proceeds. It's not added on top. Sellers sometimes think "the buyer gets $5,000 back" means it's separate from their payout. It isn't. The concession reduces the net amount you receive at closing, and a sloppy estimate will leave you wondering where the money went.
What Most Estimates Get Wrong
The biggest mistake I see isn't in the arithmetic, it's in the assumptions. People look at a comparable sale that went for $50,000 above asking and assume their home will do the same. That's how you end up pricing too high, sitting on the market for months, and then doing a price reduction that erodes your proceeds more than a realistic initial price would have. A good estimate starts with what your home will actually sell for, not what you hope it sells for. When I run estimates for people now, I pull at least three verified closed comps from the last 90 days within a half-mile radius, adjust for square footage, condition, and days on market, and then factor in current market direction. If the market is shifting toward buyers, I trim 2% to 4% off the raw comp average. If it's favoring sellers, I might add 1% to 2%. The adjustment is small but it's the difference between a comfortable estimate and one that leaves you short at closing. There's also the issue of lien resolution. If you have a home equity line of credit, a second mortgage, an old mechanic's lien, or unpaid property taxes, those all get paid from your proceeds before you see a dime. I've seen sellers estimate they'd net $80,000 only to discover a $15,000 unreleased lien from a contractor who never got paid after a renovation three years prior. A title search before you list saves you from this. It costs a few hundred dollars and prevents a very unpleasant surprise.
Get the Full Details

A Few Things Calculators Won't Tell You
Capital gains tax is a silent destroyer of proceeds if you're not careful. If you've owned and lived in the home for at least two of the last five years, you can exclude up to $250,000 of gain if you're single or $500,000 if you're married filing jointly. Anything above that threshold is taxed. On a $425,000 sale with a $200,000 basis, a single filer would owe capital gains on $225,000. That's a meaningful number that doesn't appear on any standard proceeds calculator. You need to consult a tax professional if your gain exceeds the exclusion limits. Here's another counter-intuitive one: a higher sale price doesn't always mean higher proceeds. If you price aggressively to spark a bidding war and the home sells for 10% over asking, the commission on that extra 10% is also 5% to 6%. Meanwhile, you may have sacrificed $10,000 to $20,000 in carrying costs by being on the market longer than a properly priced home would have been. The math rarely works out in your favor the way people expect it to. The one real limitation of any estimate tool, whether it's a spreadsheet or an online calculator, is that it can't account for negotiation dynamics. If the buyer's inspection reveals a failing HVAC system, that's a $6,000 repair credit that didn't exist in your original estimate. If the appraisal comes in low and the deal renegotiates, your sale price drops. No formula predicts these events. The best you can do is build a buffer of 2% to 3% below your initial estimate and treat that as your actual floor.
What Actually Works When You Need Reliable Numbers
For a quick ballpark, a basic spreadsheet works fine. Put your expected sale price in one cell, multiply by 0.06 for commission, multiply by 0.025 for closing costs, and subtract your mortgage balance. That gives you a rough figure in about five minutes. If you want something more accurate, an agent's comparative market analysis will nail the sale price assumption better than any algorithm because it incorporates local knowledge about buyer demand, school district shifts, and neighborhood stigma that no public database captures. The workaround I use now, and I'd recommend it to anyone doing this, is a two-step process. First, run the estimate yourself using a simple calculator to establish your baseline. Second, take that number to a local agent or real estate attorney and ask them to pressure-test it against current transaction data. This usually takes 30 minutes and catches the things your estimate missed. In my experience, the adjusted number is almost always $5,000 to $15,000 different from the raw calculation, and it almost always goes lower. If you're selling a property with unusual complications like probate, divorce settlement, or partial ownership disputes, the standard estimate tools break down completely. These situations introduce legal fees, court costs, and partition expenses that have nothing to do with your mortgage or commission. In those cases, skip the calculator and go straight to a real estate attorney who handles closings in your county. The consultation fee is worth it compared to finding out six weeks into the process that your entire proceeds estimate was built on incorrect assumptions.