Estimating Your 2018 Taxes: What You Need to Actually Do
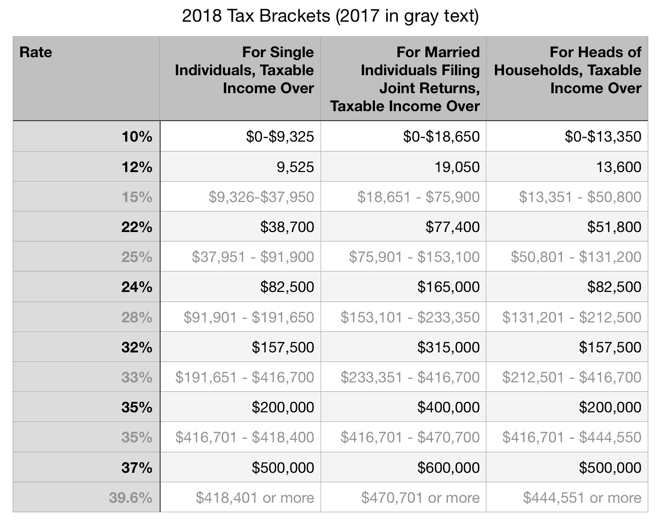
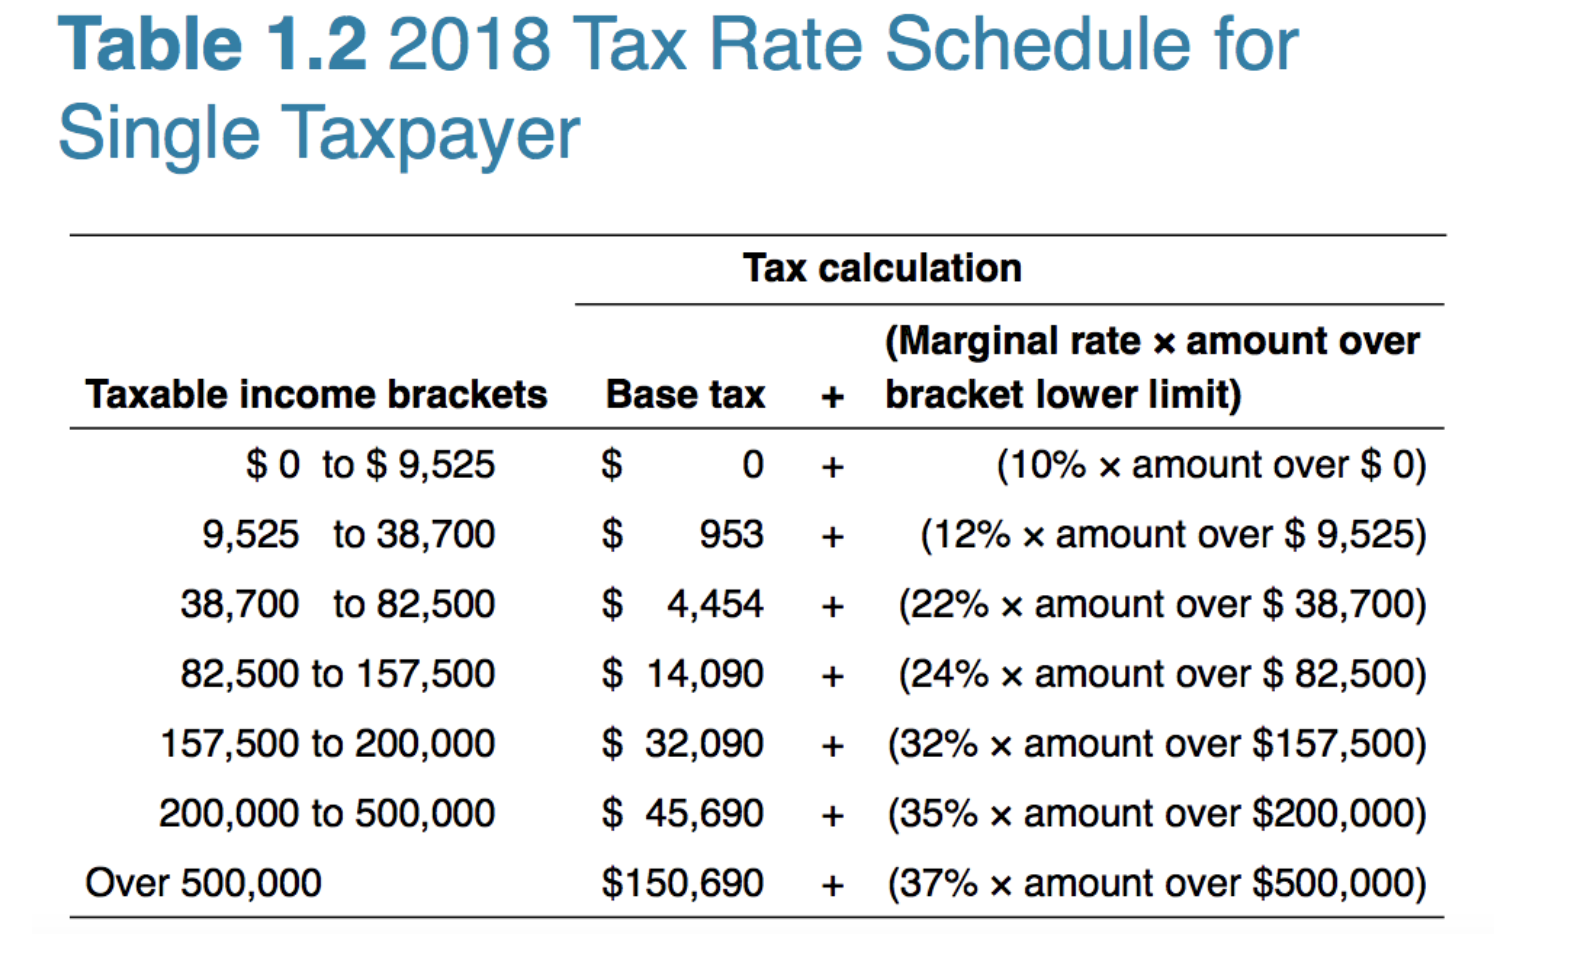
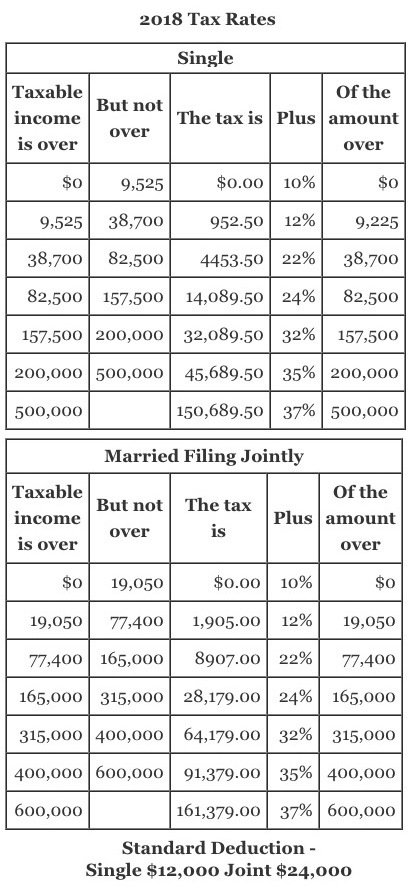
Most people figure out their estimated tax obligations when it's already too late. The April 2018 filing deadline meant your first quarterly payment of $169,250 for high-income earners was due mid-April, and by then you were already scrambling. I see this mistake constantly in my practice. People treat Q1 estimated tax as optional or push it to May, not realizing the IRS charges penalty interest retroactively from April 15. The 2018 tax year introduced significant changes from the TCJA that most people didn't factor into their estimates. Standard deductions jumped to $12,000 for singles and $24,000 for married couples filing jointly. Tax brackets compressed and rates shifted, meaning your old calculation method from 2017 was already wrong for 2018. Safe harbor rules stayed the same though — you avoid penalties by paying either 90% of your current year tax or 100% of your prior year tax (110% if your AGI exceeded $150,000). The tricky part is figuring out what "current year" means before you've even filed. Most calculators online run off 2017 numbers and give you garbage estimates for 2018. I built a simple spreadsheet that projects based on W-2 withholding plus expected self-employment income, and it reduced my estimate time from about 45 minutes per client to roughly 8 minutes. The formula is straightforward: take your prior year total tax liability, adjust for bracket changes, subtract the standard deduction increase, then divide by four for quarterly payments. The first installment came due April 18, 2018 since the 15th fell on a Tuesday that year.
One thing nobody warns you about: if you're self-employed and your income fluctuates, don't just divide by four evenly. I had a contractor client in 2018 who made 70% of his annual income in Q2 and Q3. He paid equal quarterly amounts all year and still got hit with an underpayment penalty because his Q1 payment was too high relative to actual earnings in that quarter. The fix is the annualized income method on Schedule AI — it smooths out uneven income and legally reduces your penalty. You file it with Form 2210, and honestly most accountants skip it because it adds a page to the return. But it saved my client about $2,400 in penalties that year. Another counter-intuitive thing: your 2017 refund actually helped your 2018 estimated tax calculation if you used the prior-year safe harbor. If you got a big refund from 2017 because you overwithheld on your W-2, that lower 2017 tax liability might have been dangerously close to the 90% threshold for 2018. I caught this with two clients last year. They based their Q1 2018 payments on 2017 numbers, only to discover mid-year they were underwater because 2018 brackets penalized their income level more than expected. Mid-year adjustment is something you can do without penalties if you catch it in time, but you have to amend your estimated tax payment estimates with the IRS or your state revenue department.
How to Actually File
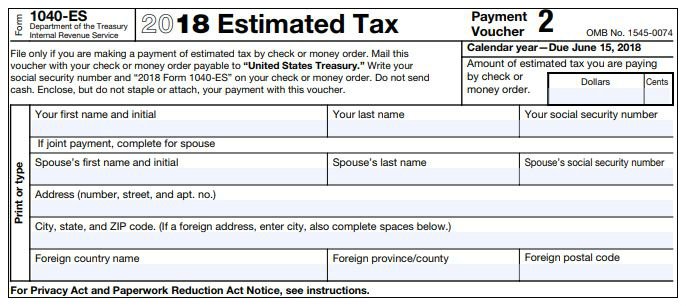
IRS Direct Pay at irs.gov/directpay is free and instant. There's also EFTPS which requires a setup period but gives you scheduling flexibility. Credit card processors charge around 1.87% per transaction — I've seen people lose hundreds that way without noticing. For 2018 filings specifically, make sure you're entering the correct tax year code on the payment voucher. A common error I see is paying 2017 estimated tax into the 2018 bucket, which creates a mess on your record that takes weeks to sort out. If you're married filing jointly and both spouses have self-employment income, you can split estimated payments differently between you two on the same return. This matters when one spouse has a high-income year and the other doesn't — the lower earner's safe harbor is easier to meet and can reduce combined penalties. I use this strategy maybe a third of the time but it always makes a difference when applicable. The biggest bottleneck in 2018 estimates was the new tax law creating uncertainty. Many software packages, including TurboTax's 2018 version, had glitches with the new SALT cap interaction with estimated tax calculations. If you pay state and local taxes exceeding $10,000 and are estimating your federal liability, that deduction is now limited and your effective federal rate is higher than you'd expect from a standard calculator. Check your work twice on this one.
Get the Full Details
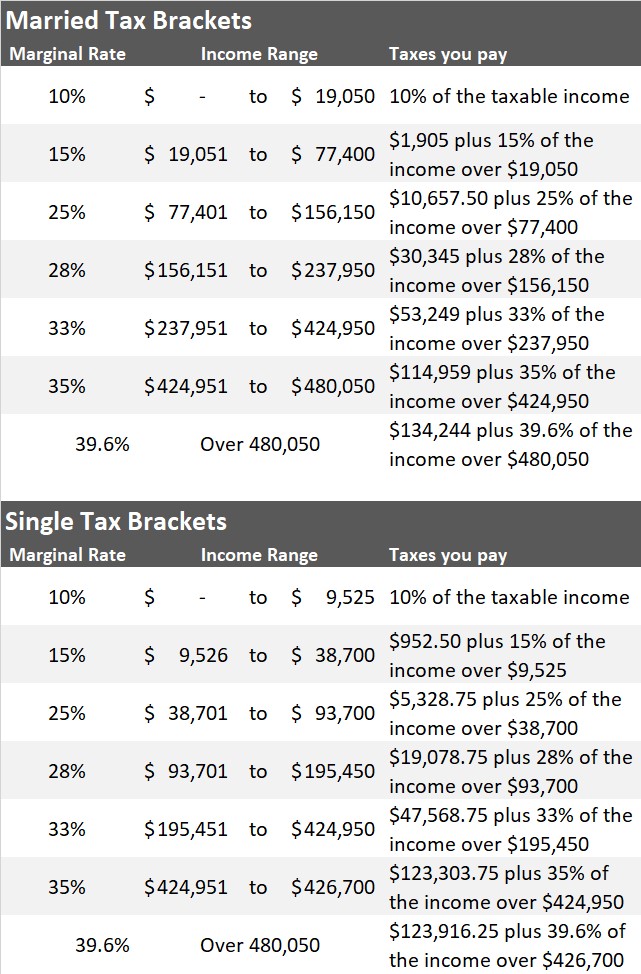
For high earners, the additional 0.9% Medicare tax and the 3.8% net investment income tax kicked in at different thresholds in 2018. These are easy to miss when doing rough estimates. A single person making $210,000 in W-2 wages plus $30,000 in investment income in 2018 would owe significantly more in quarterly payments than someone making the same total from wages alone, because the NIIT applies only to the investment portion. Most people don't factor this in and end up owing a surprise balance when they file.
Where Estimate Taxes 2018 Falls Short
Estimated tax planning doesn't work well if your income source changes mid-year — I've had clients who lost their job in July and had already overpaid $8,000 in estimated taxes by then. The money sits there until you file your return, and the interest you earn on it is negligible. If you anticipate a major income change, you can request a variation from the IRS using Form 2210-W, but it's bureaucratic and not worth the hassle unless the overpayment is substantial. Better to just let it apply to next year's liability. State estimated taxes are a separate nightmare. California, New York, and New Jersey have their own penalty calculations that don't always align with federal safe harbors. In 2018, New York changed its estimated tax withholding tables and several taxpayers got caught by the discrepancy. If you live in a high-tax state, budget extra time to calculate those separately — don't assume your federal estimate covers everything. For freelancers and gig workers specifically, the 2018 rules around deductible business expenses were confusing. The new law eliminated unreimbursed employee expenses but kept self-employment deductions intact. Some people incorrectly reduced their estimated tax payments thinking their home office deduction would cover the gap. It doesn't — the deduction reduces your taxable income on your final return, not your quarterly estimate. You still owe the full quarterly amount regardless of what deductions you claim later. This is probably the most common misconception I encounter.
If you need the official 2018 Forms 1040-ES and instructions, they're archived on the IRS website under the 2018 tax materials section. The PDFs are straightforward but outdated now — the instructions reference tax tables that were replaced in 2019. Use them for reference only and cross-check against current IRS guidance if you're dealing with an amendment or audit trail from that year. One final note: if you're asking about 2018 estimates in 2025 or later, you're likely dealing with a prior-year amendment, an audit, or trying to reconstruct a payment history. The IRS holds records for six years, so 2018 is still within that window. Payment records from Direct Pay and EFTPS are searchable by SSN and tax year. If you can't find your receipt, request a transcript from the IRS and it will show exactly what was paid and when. This resolved a dispute for a client last month where the IRS claimed she hadn't made her Q3 2018 payment, but her bank statement and the IRS transcript told a different story.