What the CPA Exam Actually Looks Like
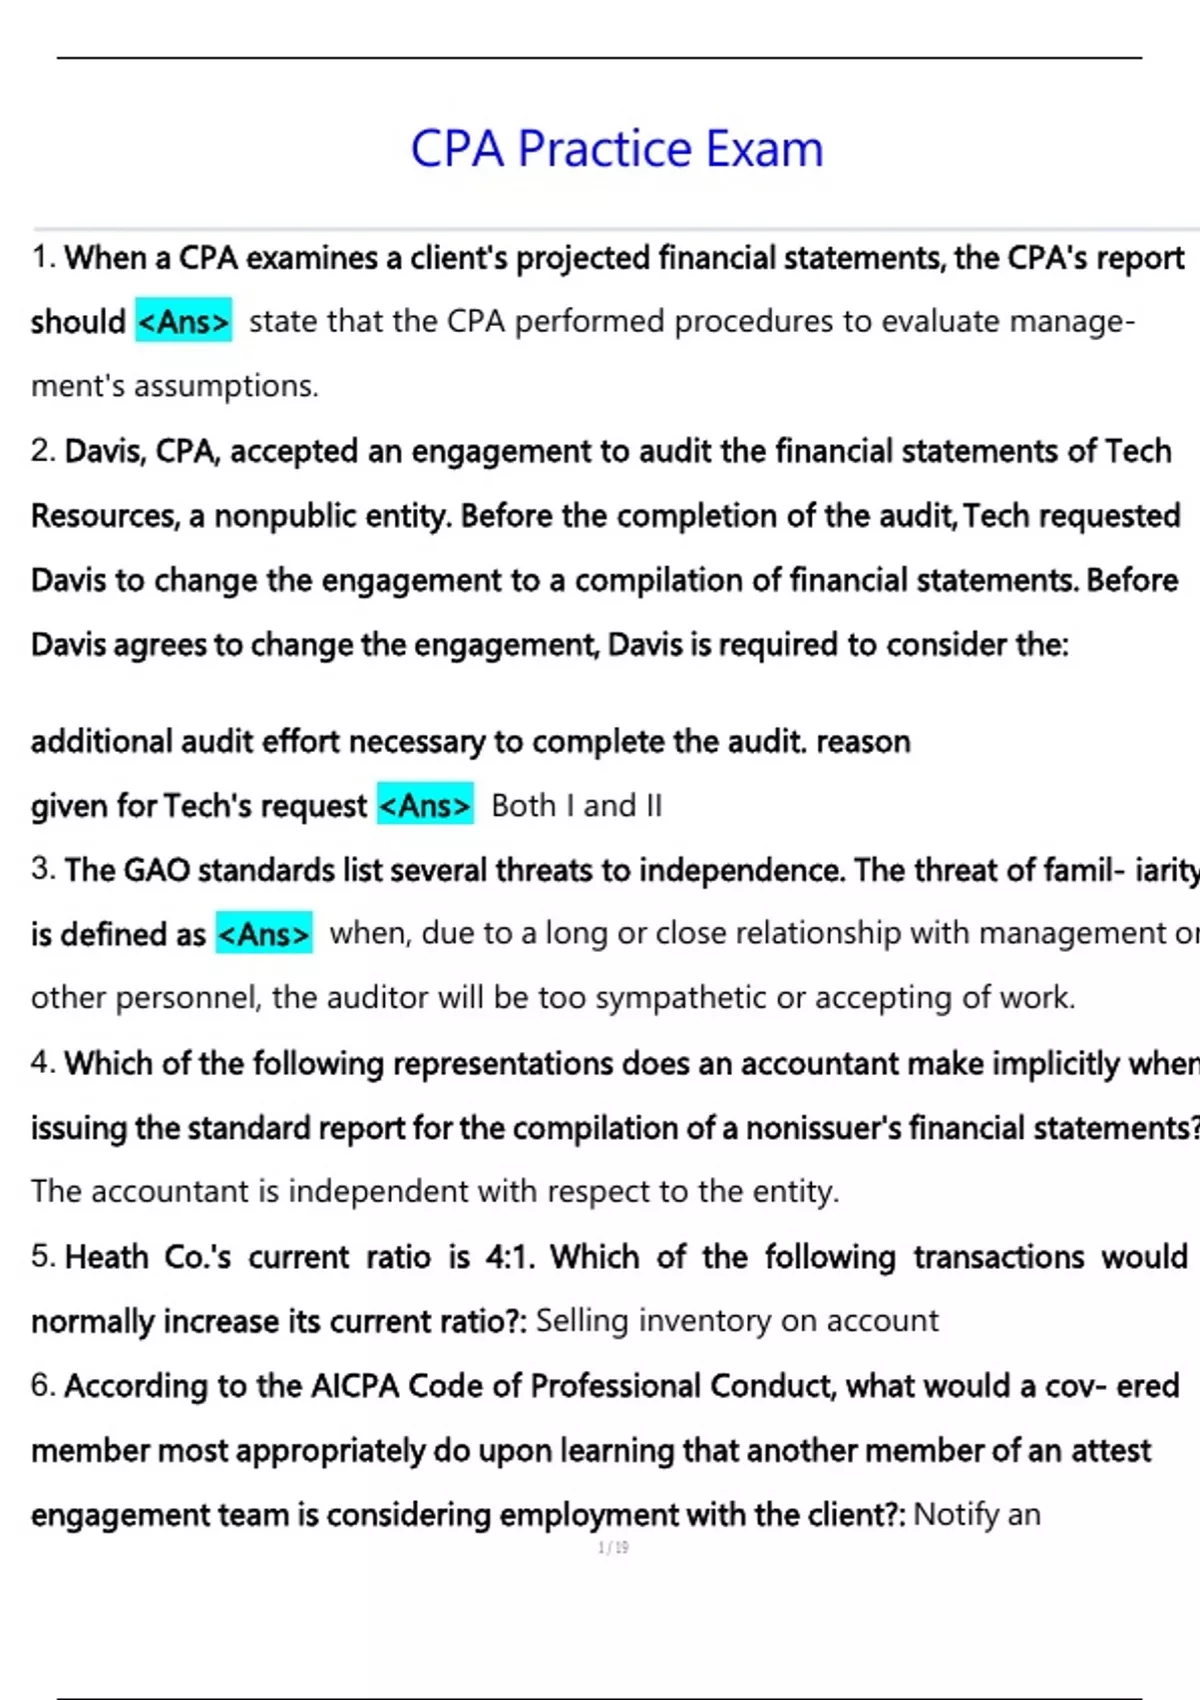
The CPA exam is four separate tests you take over a testing window that can stretch months. Each section is a standalone beast. You don't have to pass them all at once. Most people spread them out across a year or two. The sections are FAR (Financial Accounting and Reporting), BEC (Business Environment and Concepts), AUD (Auditing and Attestation), and REG (Regulation). Each one is approximately four hours long. You get a mix of multiple choice questions, task-based simulations, and in some cases written communication tasks. I remember taking the FAR section on a Tuesday morning. The testing center smelled like stale coffee and carpet cleaner. I opened the exam and immediately hit a simulation about lease accounting under ASC 842 that required me to calculate the right-of-use asset, the lease liability, and then build out an amortization schedule. It took me nearly forty minutes. I had to work through it twice because I messed up the present value factor in my first attempt. That's the reality of the exam. You're not just recalling information. You're applying it under time pressure while staring at a clunky interface that doesn't always make sense.
Example Of Cpa Exam in Practice
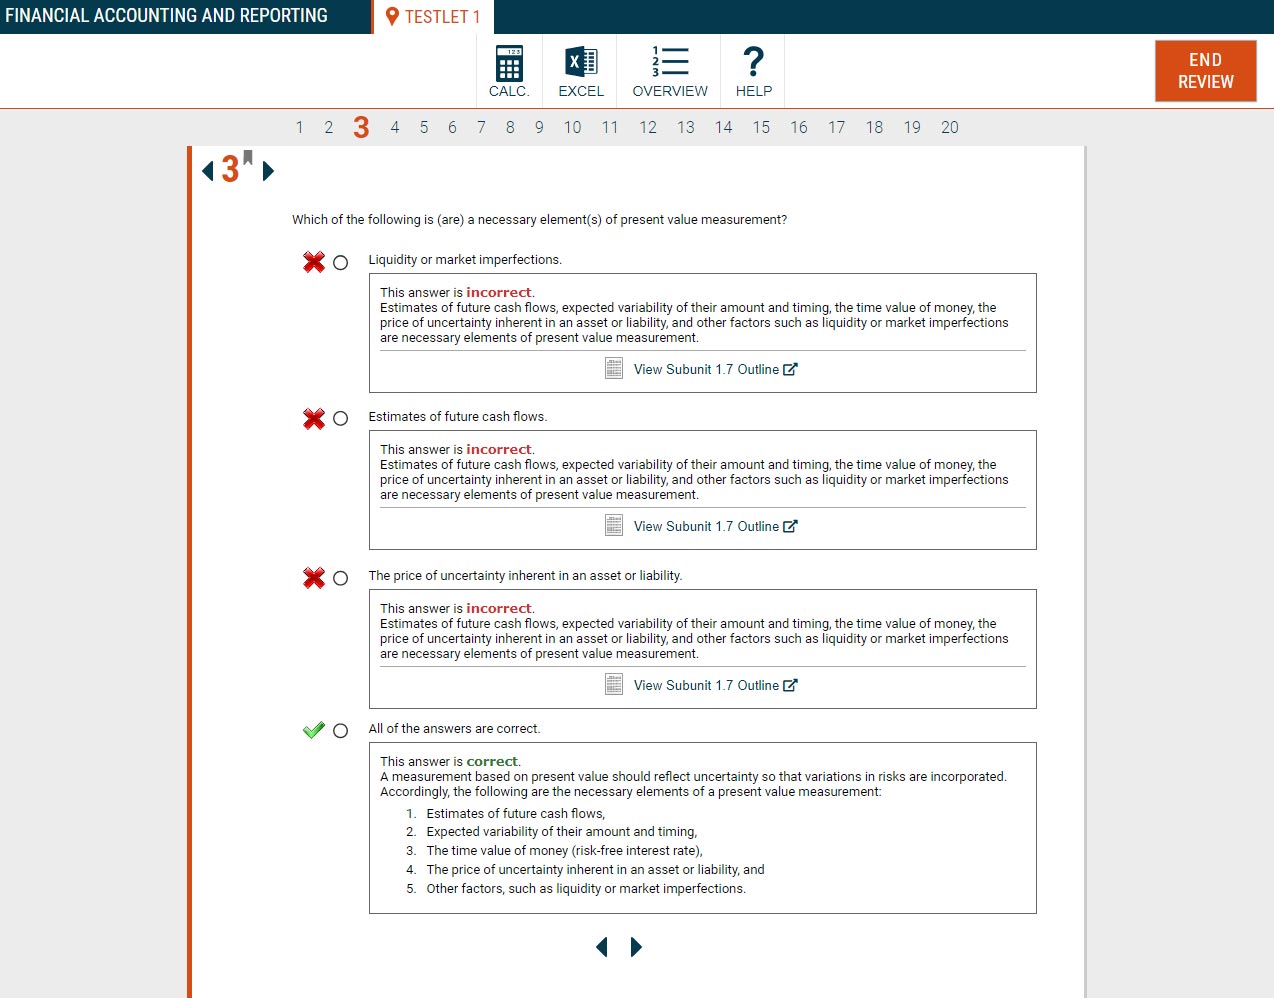
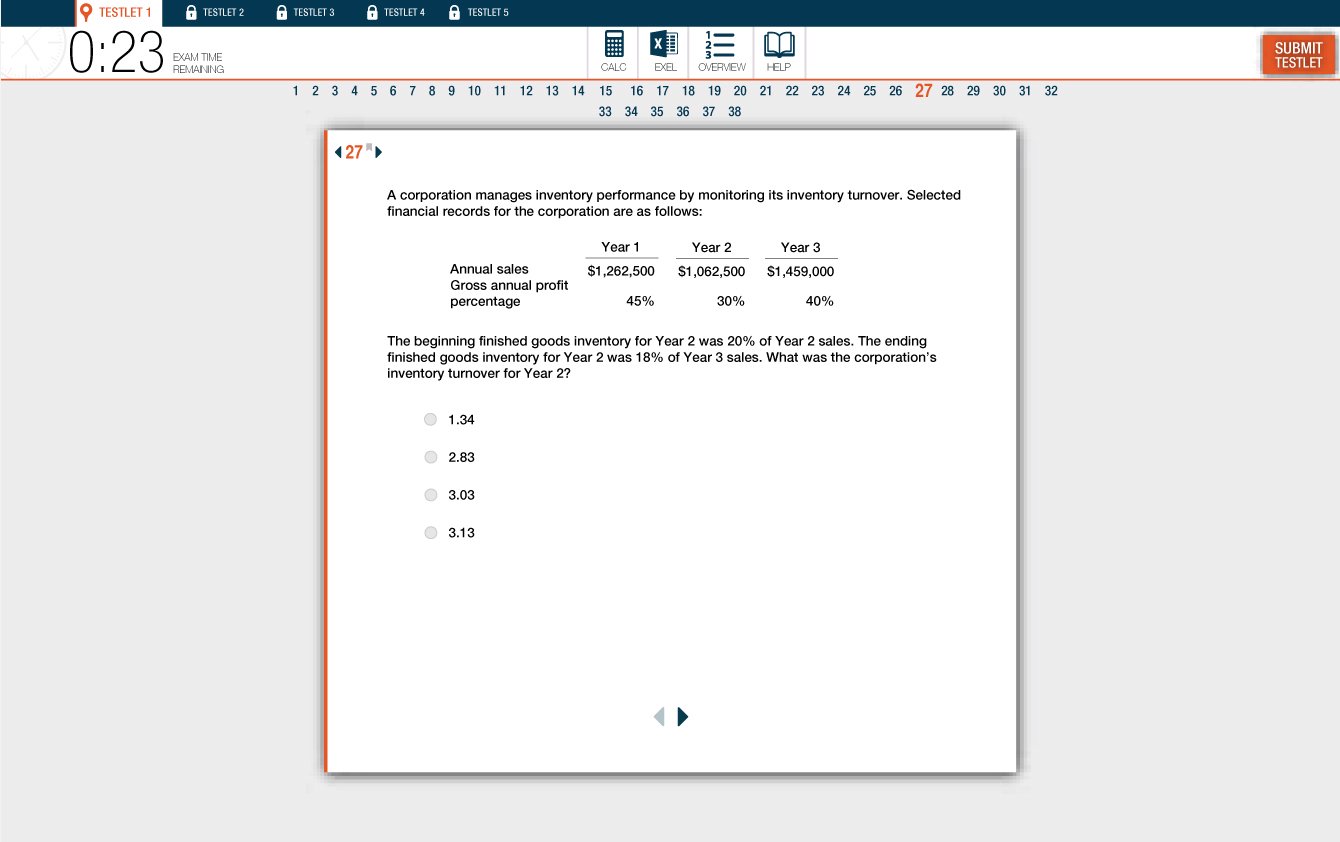
Here's a concrete walk-through. In the REG section, you'll typically see simulations that look like this: you're given a fact pattern about a client who owns rental properties, and you have to determine the depreciation method, the basis adjustments, and the correct treatment of casualty losses. The interface gives you a calculator, a tax law reference library, and sometimes a spreadsheet tool. You type your answer into text boxes or select from dropdown menus. It feels less like a traditional test and more like doing actual tax work. That's intentional. The NASBA and AICPA designed it that way. In FAR, an example simulation might give you a bond issuance scenario. You need to figure out the journal entries for issuance, interest accruals, and amortization of any premium or discount. I once spent time on a simulation involving convertible bonds where the question asked whether I should account for the liability and equity components separately under ASC 470-20. The trick was that the conversion feature had no substantial premium. Most people who rush through it just record the entire proceeds as a liability. You have to read the question carefully and follow the specific guidance. Taking an extra ninety seconds to identify which standard applies changes the whole answer. The BEC section includes written communication tasks where you have to draft a memo. You're given a business scenario and you write a professional response addressing the prompt. I wrote a memo about whether a company should capitalize or expense software development costs. There is no single right answer in terms of content quality. They're grading on structure, clarity, and whether you addressed the key points. I learned this after my first practice run. I wrote a three-paragraph wall of text and scored poorly. Breaking it into clear sections with headings fixed it. Simple but not obvious.
How the Scoring Works
Each section is scored on a scale from 0 to 99. You need a 75 to pass. The scoring blends your multiple choice performance with your simulation performance. They don't tell you which part weighted more. What they do tell you is that simulation performance matters a lot. I saw this firsthand when I reviewed my score reports after my first attempt at AUD. I did well on the multiple choice but bombed several simulations. My overall score reflected that. The takeaway is that you can't rely on multiple choice alone. You have to practice simulations until they feel routine. One detail nobody warns you about: the exam is computer adaptive in certain parts, but not in the traditional sense. The multiple choice questions don't adjust difficulty based on your answers during the exam. The scoring does use adaptive algorithms afterward. This means your raw score on multiple choice gets scaled. A hard block of questions might be worth slightly more than an easy one. This isn't something you can game. It just means you should treat every question equally. Don't spend ten minutes on a hard one and skip the next three easy ones to compensate. That strategy backfires more often than it helps.
Get the Full Details
What Most People Get Wrong About Prep
The biggest mistake I see is people who only do multiple choice questions. They grind through thousands of MCQs and feel prepared. Then they open the simulations and freeze. The simulations require you to generate answers, not just recognize them. Watching someone else work through a simulation or reading a walkthrough doesn't build the same muscle. You have to actually open the simulator, type out your answer, and grade yourself. Another pitfall is studying the wrong version of the rules. Tax law changes. Accounting standards get updated. If you're using older materials, you could be learning something that no longer applies. I used a REG review course that hadn't been updated for the TCJA provisions on qualified business income deduction. I spent weeks memorizing rules that were already modified. When I got to the exam, the questions reflected the current law and I was off by a significant margin on several items. Always check the publication date on your materials. If it's more than a year old, verify the content against the current AICPA blueprint. Time management is also a common failure point. Four hours goes fast. In FAR, I've seen people spend twenty minutes on a single simulation and then panic because they haven't started the last one. The trick is to set internal checkpoints. After the first hour, you should have completed a certain number of items. If you're behind, move on and come back later. Leave the hardest questions for last if you need to. Getting partial credit on a simulation is better than getting zero because you ran out of time before finishing it.
Where to Find Official Practice Materials
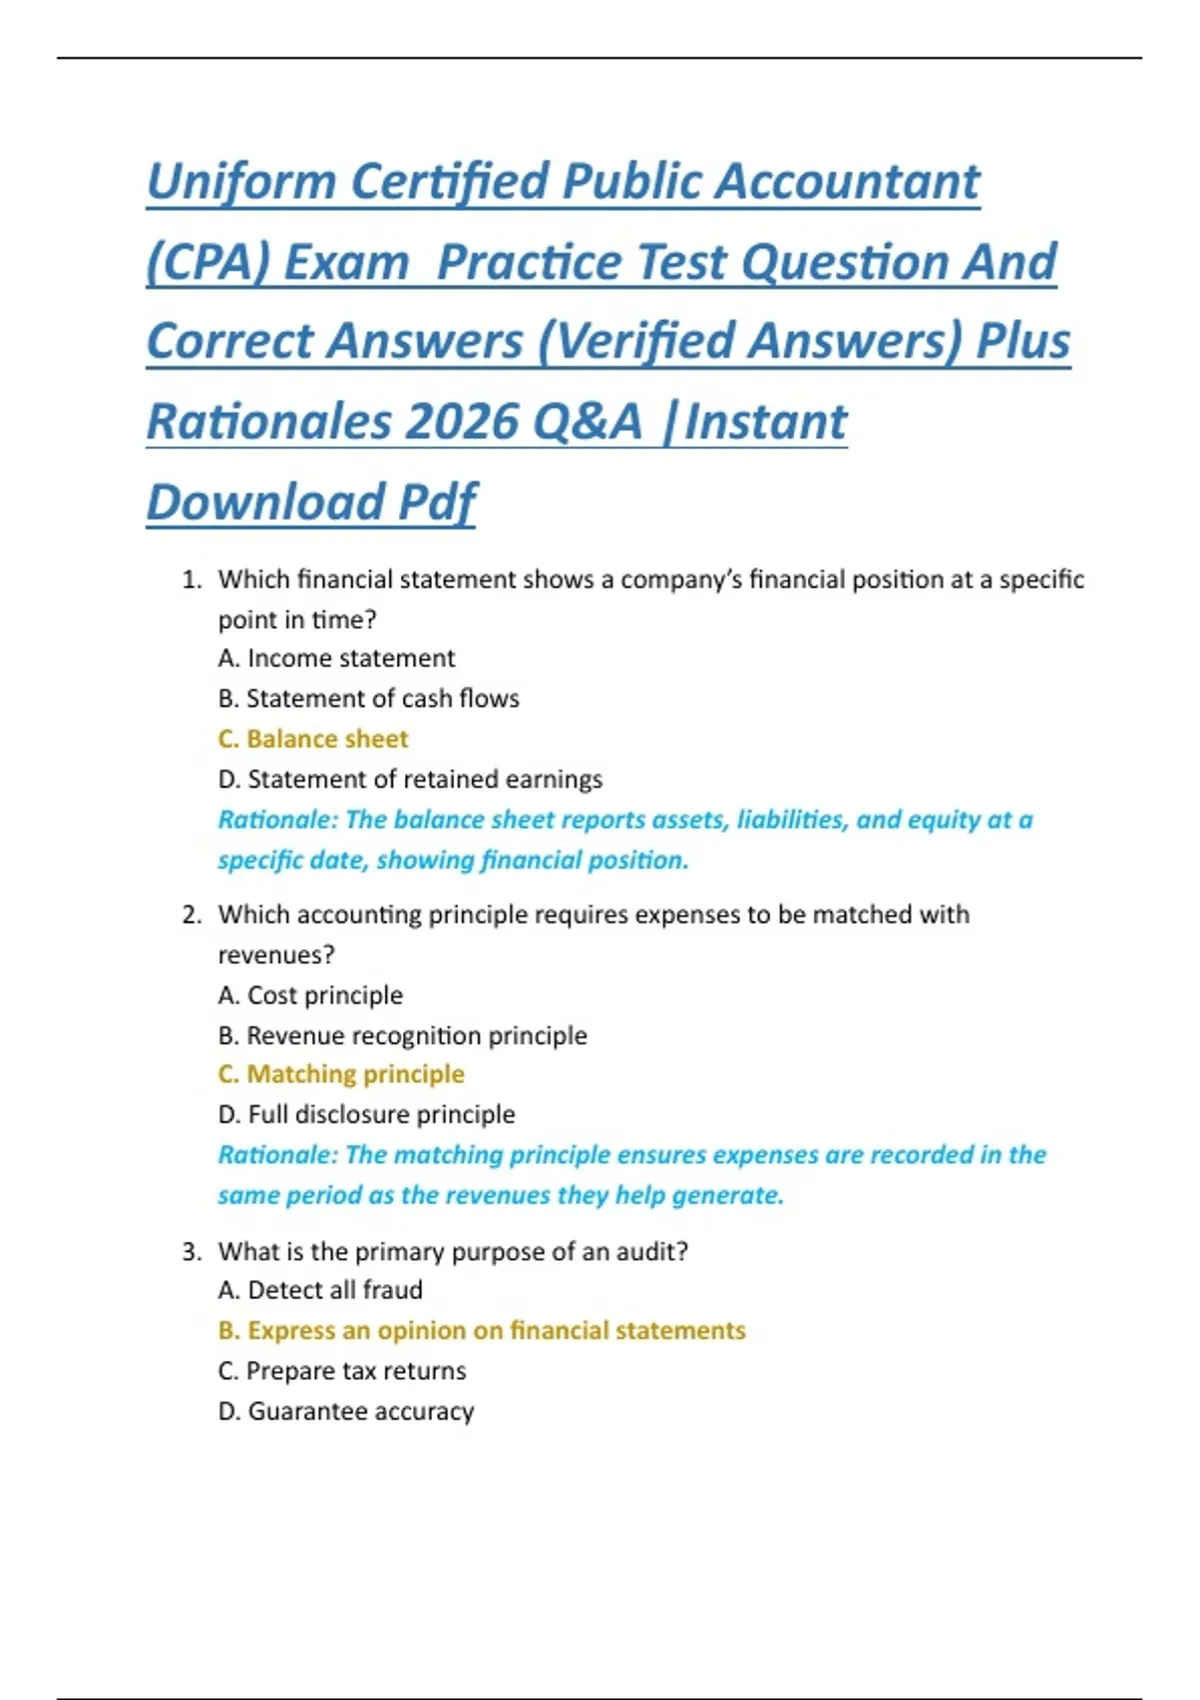
The AICPA offers free sample questions on their website. These aren't the full exam but they show the format and interface. Third-party providers like Becker, Wiley, and Roger sell review courses that include adaptive learning platforms and full-length simulations. I recommend starting with the free AICPA materials to understand the layout, then investing in a course that matches your learning style. The AICPA also publishes practice exams that you can purchase separately. Those are closer to the real thing than anything else available. There's no official downloadable version of the full exam. Anyone claiming to have one is distributing something unauthorized. Stick to legitimate sources. The test bank questions from review courses are generated by people who write for the actual exam, so they carry weight. The interface you practice on matters too. Most major providers now have simulators that mimic the actual testing environment. Use them.
Bottom Line
The CPA exam is long, stressful, and requires deliberate practice. It rewards people who treat it like a job. Studying four hours a day for eight to twelve weeks is a typical timeline for someone working full time. Studying less and hoping for the best rarely works. The exam tests application, not memory. If you can work through simulations under timed conditions without looking at the answer, you're in a good place. If you're still second-guessing yourself on basic topics like revenue recognition or bond accounting, keep working those until they click. The exam doesn't get easier. Your familiarity with it does.