The thing everyone gets wrong about business plans
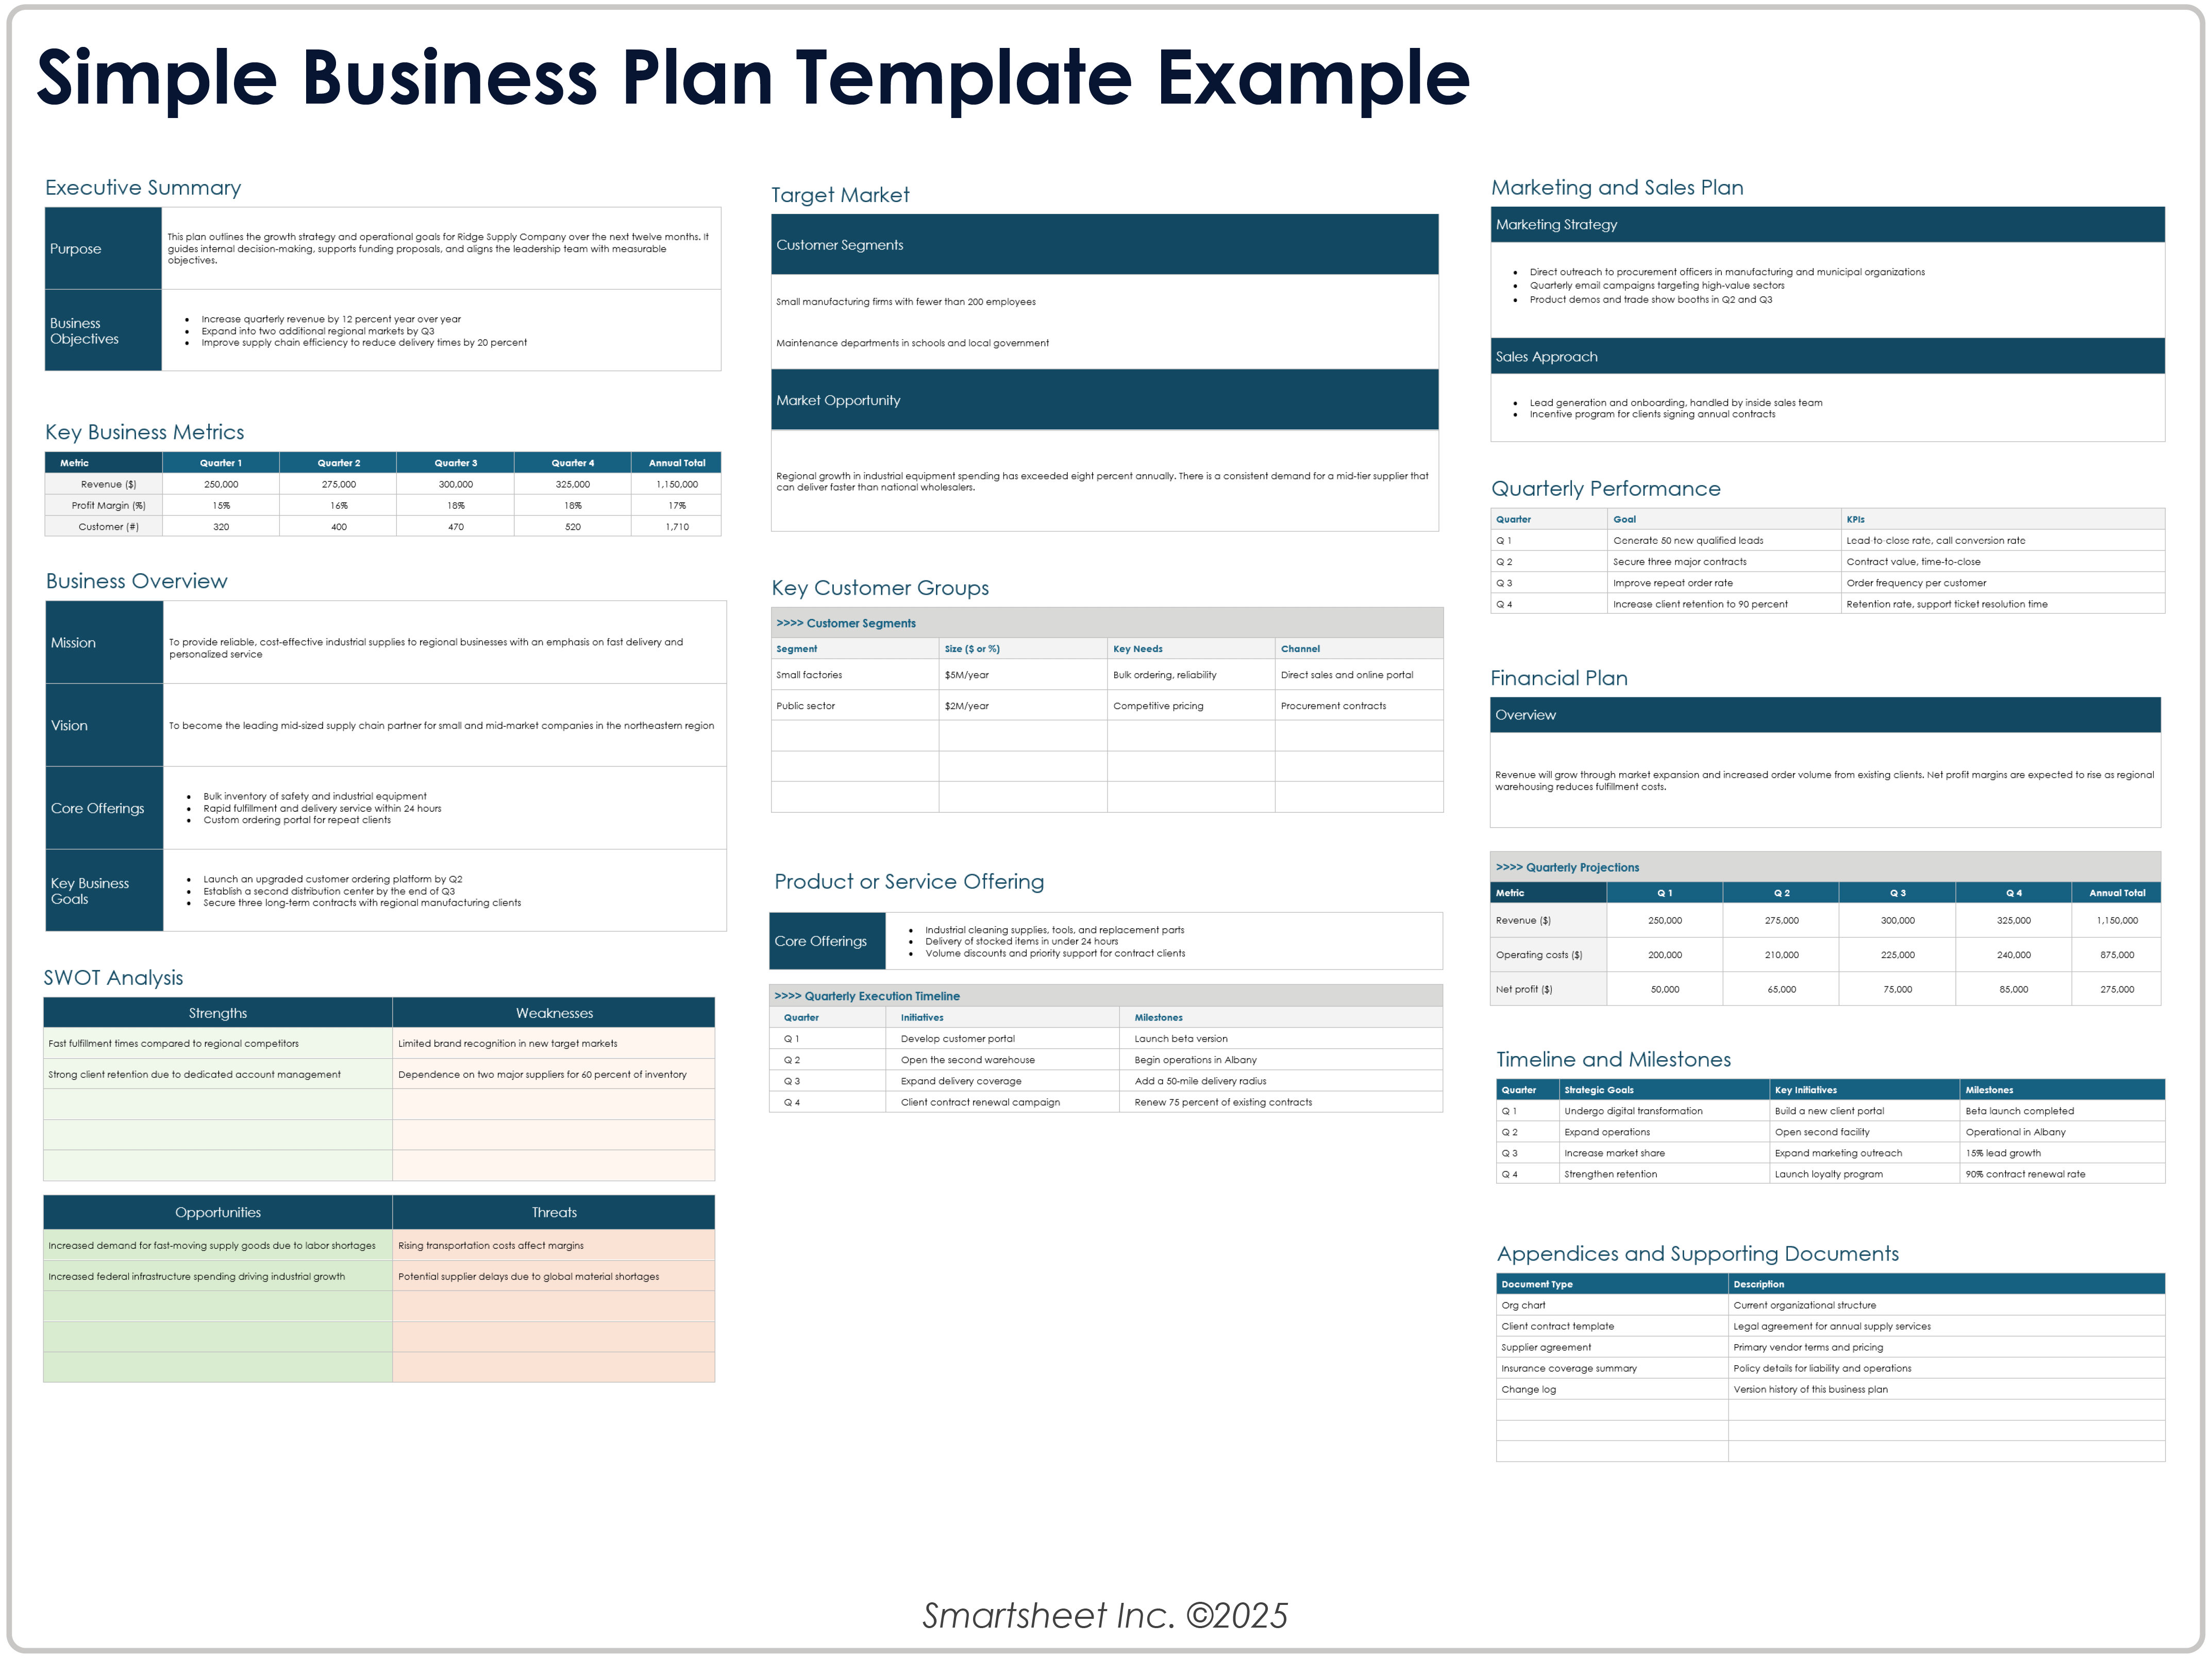
Most people think a business plan is something you write once and then frame on the wall. It isn't. It's a working document that mostly sits in a drawer, occasionally used to explain to someone else why you need money, or to remind yourself that your revenue assumptions were wildly optimistic six months ago. A simple business plan is just the stripped-down version that actually gets read. Not the twenty-page PDF with an executive summary about an executive summary. The kind where you can scan it in three minutes and know whether the math works.Example Of Simple Business Plan
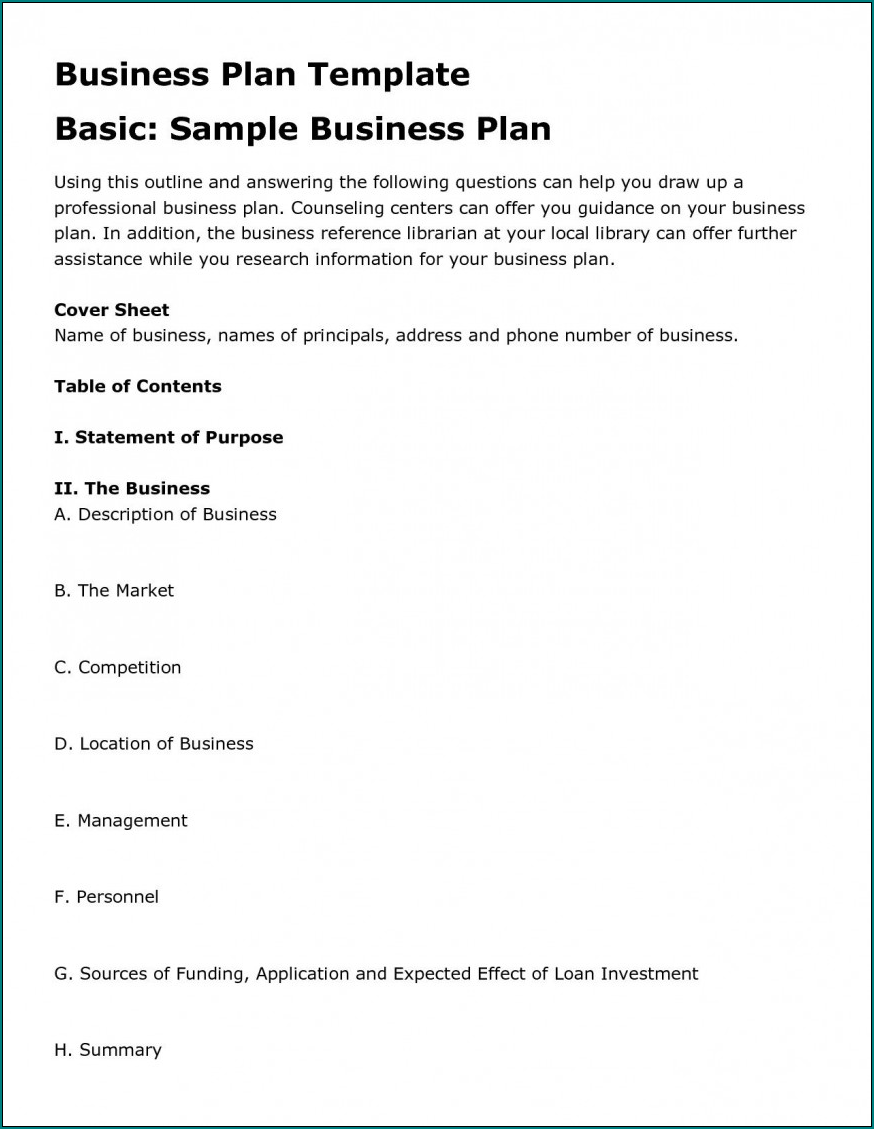
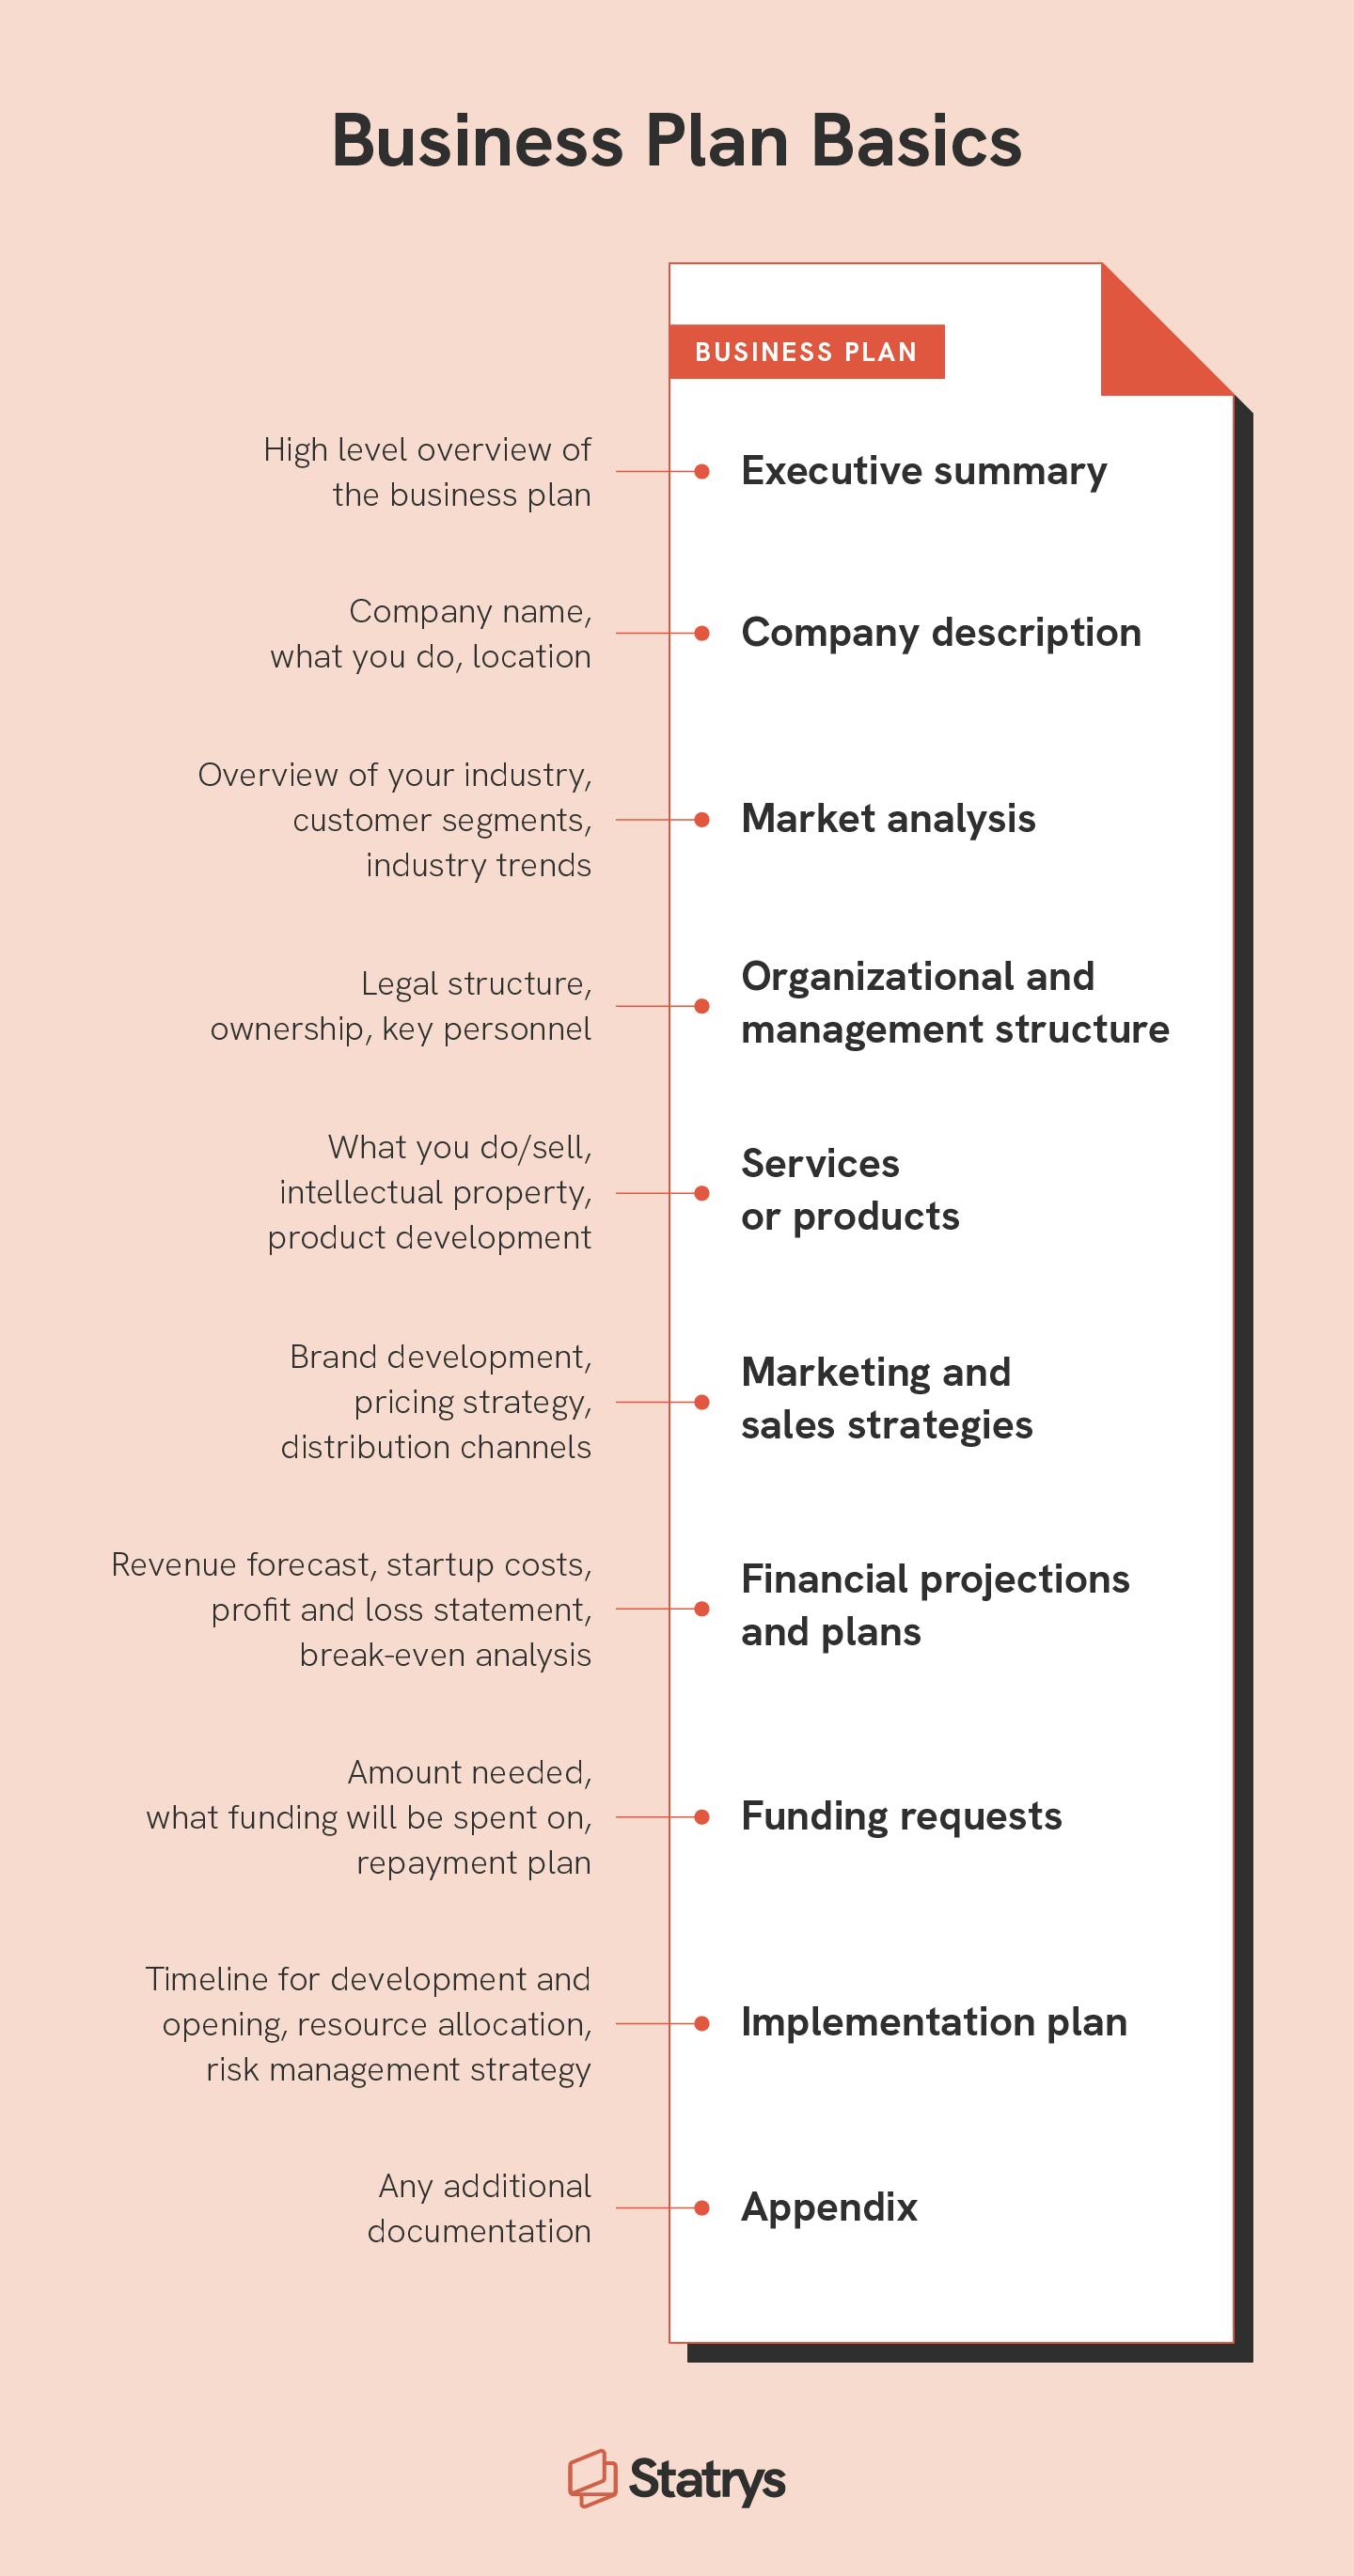
I used to spend about four to six hours drafting full plans for small consulting clients, and most of that time went into formatting and justification language. The actual content was usually three pages. Now I write a simple version in about forty-five minutes, and the investors or partners who actually need information get what they need without wading through padding. The structure is straightforward. You cover five sections and that's it. A one-paragraph description of what the business does, a brief competitive landscape, your target customer, the revenue model, and a basic financial projection for the first twelve months. That's it. Everything else is optional or speculative.
How to actually build one without losing your mind
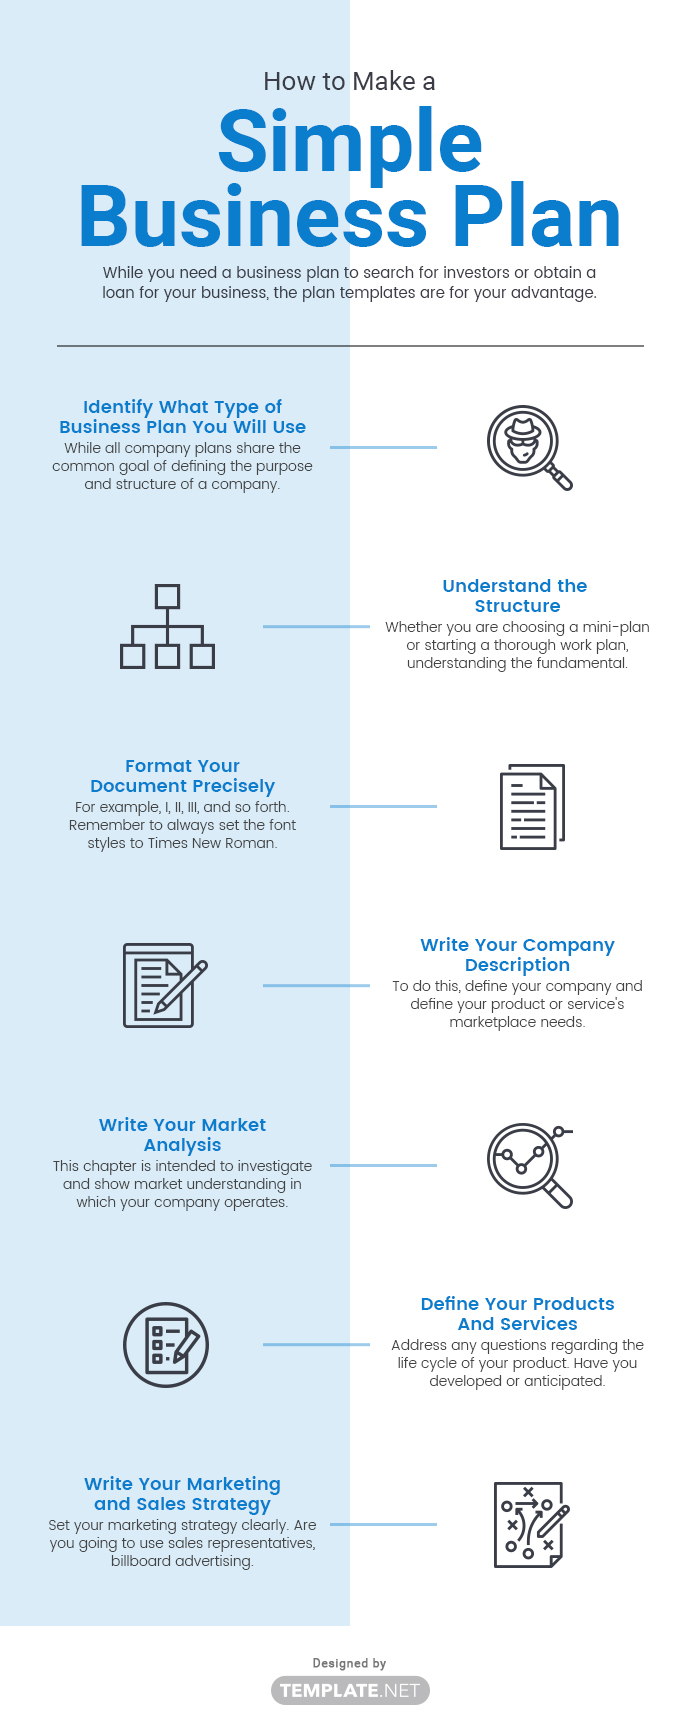
Start with the financials. I know that sounds backward, but if you can't make the numbers work on a napkin, the rest of the plan is just prose decoration. Write down your expected monthly revenue, your fixed costs, and your variable costs. Subtract. If the result is negative for more than three months in a row, go back to the top and adjust your assumptions instead of writing a longer introduction. For the customer description, be specific enough that someone else could find these people. "Small businesses" is not a customer segment. "Dental practices with two to five dentists in suburban areas" is. I learned this the hard way when I pitched a service to a vague audience and couldn't answer a single question about pricing sensitivity during a meeting. The room went quiet. It was embarrassing. Keep the competitive analysis to three to five direct competitors. Not twenty. Not industry trends. Direct competitors who are solving the same problem for the same customer in the same way you are. For each one, note what they charge and what they're missing. If you can't fill that blank, you don't have a competitive advantage, you have an opinion.
The financial section that actually matters
Most people overcomplicate this. You need three things: projected revenue, projected expenses, and projected cash flow. A spreadsheet with one row per month for twelve months is enough. Don't do quarterly. Don't do annual-only. Monthly reveals the seasons and the gaps that kill new businesses. Revenue projections should be based on conversion rates and capacity, not hope. If you're doing consulting, calculate how many client hours you can realistically sell per week, multiply by your rate, and subtract the weeks you'll be sick or traveling. If you're selling a product, estimate your website traffic, your conversion rate, and your average order value. These are guess estimates at first, but they should be educated guesses, not inspirational quotes. Expenses split into fixed and variable. Fixed costs are rent, software subscriptions, insurance, salaries that don't fluctuate with revenue. Variable costs are things like payment processing fees, shipping, raw materials, contractor costs that scale with each sale. I used to lump everything into fixed and then wonder why I ran out of cash in month four. The difference between fixed and variable matters enormously when revenue dips.
Get the Full Details
A concrete example
Say you're starting a graphic design business doing branding packages for local restaurants. Your plan might look like this: Monthly revenue target: eight clients at an average of two thousand dollars per branding package, equals sixteen thousand dollars per month once you're established. Your fixed monthly costs are about four thousand dollars: software subscriptions, website hosting, liability insurance, a part-time bookkeeper, and your own salary draw. Your variable costs run about fifteen percent of revenue: stock image subscriptions, freelance help on overflow projects, and transaction fees. That leaves roughly eight thousand eight hundred dollars in gross margin per month at full capacity, before taxes. That's the core of the plan. One paragraph for the business description, a short section on who the customers are and why they'd choose you, the revenue model with the math shown, and a twelve-month cash flow table. Done. You can print it on two pages.
Where this approach falls apart
A simple business plan does not work well if you're applying for a traditional bank loan. Banks want to see collateral schedules, debt service coverage ratios, personal guarantee disclosures, and three years of historical financials if you have them. A one-page plan will get your application rejected on technical grounds before anyone reads the actual idea. It also doesn't work for partnership agreements where multiple people are putting money in. In that case, you need operating agreement language, profit distribution mechanics, and vesting schedules. The simple format covers none of that. Use the simple version for internal planning and early-stage investor conversations. Use the detailed version when real legal or financial commitments are on the table. There's also a tendency to treat the plan as a finished product rather than a living model. I've seen people write a plan, file it away, and then run their business on autopilot while the numbers drift further from reality each month. The plan should be updated every quarter, even if the only change is revising the revenue projections based on what actually happened. A stale plan is worse than no plan because it creates false confidence.
Where to find a template or download
SBA.gov has a free business plan template that aligns with their requirements and is a reasonable starting point for a simple version.SCORE.org offers downloadable one-page business plan templates that are closer to what most small businesses actually need. Many cloud accounting platforms like QuickBooks and FreshBooks also include basic business plan builders that pull from your actual transaction data rather than forcing you to start from zero. If you want something leaner, a single spreadsheet with the twelve-month cash flow projection and a one-page Word document covering the four non-financial sections is sufficient for most early-stage decisions. Don't buy a $200 template pack. The structure doesn't change based on who sells it.
Common mistakes that waste time
Writing about your passion instead of your margins. Investors and partners don't care that you love food trucks. They care that your food truck can serve forty units per hour at a two-dollar profit margin after ingredients, fuel, and permits. Passion is irrelevant to the plan unless it drives a measurable competitive advantage. Assuming zero churn. If you're running a subscription business or a retainer model, your projections should include a monthly churn rate. Even a five percent churn rate on a recurring revenue model changes your year-one projection significantly compared to a flat line. I once built a model that looked profitable for eighteen months, then forgot to include cancellation assumptions. The actual cash flow hit a wall in month fourteen. Fixed it by adding a simple churn column and recalculating. Overestimating your capacity. New business owners tend to assume they can work eighty-hour weeks for the first six months. Most can't. Most shouldn't. Factor in realistic working hours, administrative time, and the fact that you'll get sick. A plan that assumes ideal conditions will fail under normal conditions, and normal conditions are the only ones that matter.
When to keep it simple versus when to expand
Keep it simple if you're testing whether an idea is viable, presenting to early-stage angel investors who prefer brevity, or using it as an internal operational reference. Expand it if you're applying for venture capital, seeking a traditional SBA loan, bringing on co-founders who need legal protections documented, or operating in a heavily regulated industry where compliance costs and licensing timelines materially affect your runway. The simple business plan is a tool, not a ceremony. It exists to make decisions faster and with better information. If reading your own plan takes longer than three minutes, it's too long. If you can't explain your revenue model to someone in under two minutes using the plan as a reference, it's too vague. Aim for the middle.