Understanding Fixed Income Securities in Practice
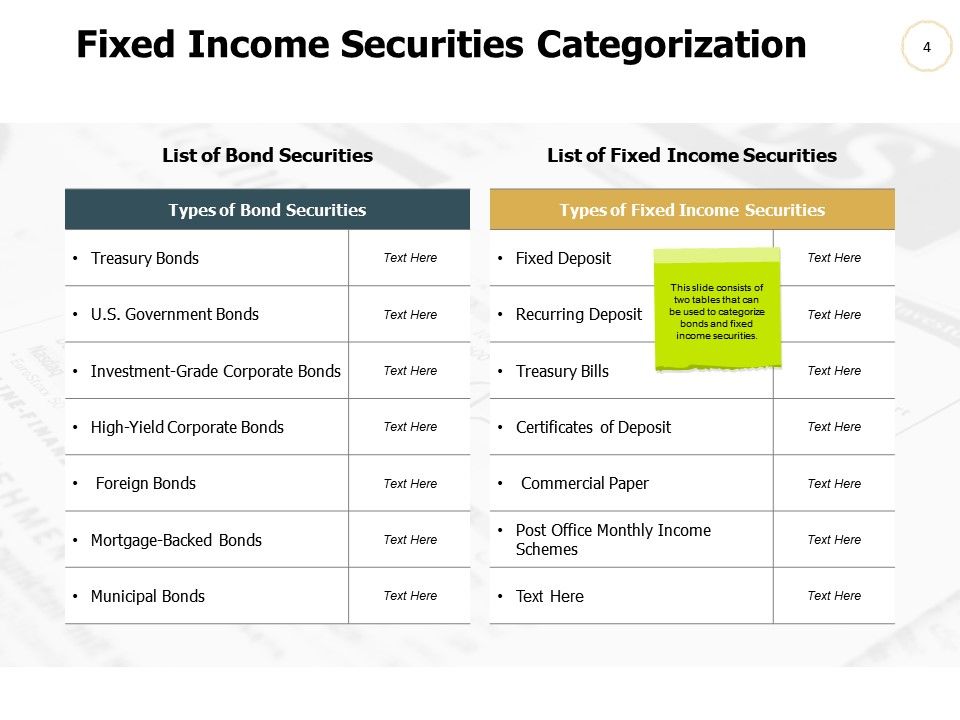
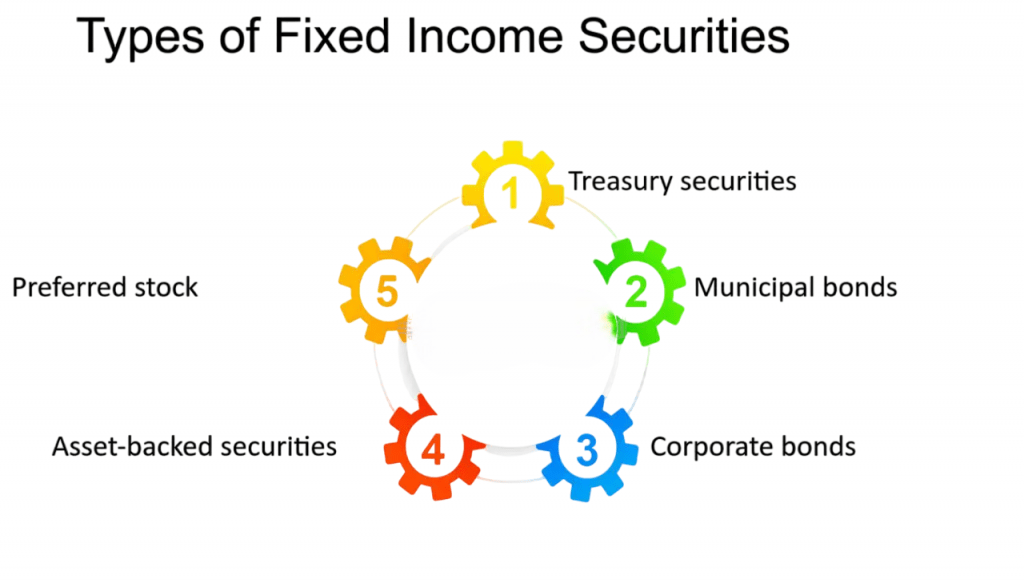
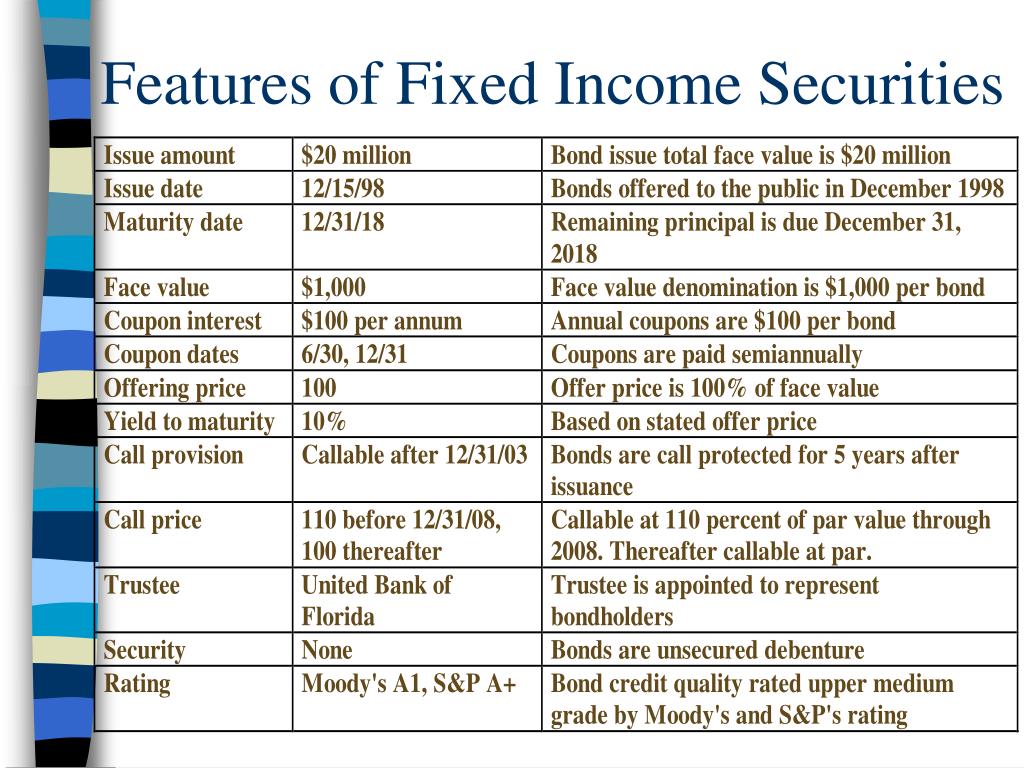
Fixed income securities are debt instruments that pay a return at a predetermined rate. You lend money to an entity, and they pay you back over time with interest. That is the basic structure. The reality of how these trade and settle is more complicated than most introductory material admits. Treasury bonds are issued by national governments and generally carry the lowest risk in any portfolio. A 10-year US Treasury note pays a fixed coupon every six months. The yield you see quoted on Bloomberg is a snapshot. It moves throughout the day as rates shift. Municipal bonds are issued by states, cities, and local authorities. Interest earned is often exempt from federal tax and sometimes state tax as well. A school district in Ohio might issue a 20-year GO bond at 4.2 percent. The after-tax yield matters more than the headline number if you are in a high bracket.
Corporate bonds come from companies raising capital. An investment-grade AAA-rated bond from a blue-chip manufacturer will yield less than a BB-rated issuer in the same sector. The spread between them is where the real risk pricing happens. You are being compensated for the chance that the company does not survive a downturn. Agency debt is issued by government-sponsored enterprises like Fannie Mae and Freddie Mac. These are not explicitly backed by the full faith and credit of the US government, but the market treats them as close enough. During the 2008 crisis, spreads on agency MBS blew out to levels that made selling them nearly impossible without taking a steep haircut. Asset-backed securities pool loans like auto loans, credit card receivables, or student loans and slice them into tranches. The senior tranche gets paid first. The equity tranche absorbs losses first. I watched a trader get burned on a 2006 vintage auto ABS pool because the model assumed housing prices would keep rising. When they did not, the prepayment speed assumptions went completely wrong and the whole thing re-priced overnight.
How Pricing Actually Works
The price of a bond moves inversely to interest rates. This is textbook. What textbooks do not tell you is that the relationship is not linear. Convexity matters more than people realize. When rates move by 50 basis points, duration gives you an approximate price change. When rates move by 300 basis points, you need the second-order term or your P&L estimate will be off by a significant margin. Most fixed income trading happens over the counter, not on an exchange. You call a dealer, get a bid and an offer, and decide whether to take it. The spread on a liquid 10-year Treasury might be 2 cents on a dollar. The spread on a 30-year Italian government bond can be 75 cents or more. Liquidity is not evenly distributed across the curve or across geographies.
Get the Full Details
Settlement and Cleaance
Most US Treasuries settle T+1 now. Corporate bonds often settle T+2. Municipal bonds can vary by issuance. If you are trading between ex-coupon dates, you owe accrued interest on top of the clean price. The dirty price is what actually changes hands. I once missed a coupon pickup because I confused the record date with the ex-date on a municipal bond trade. The correction took three business days and cost me roughly 0.15 percent of the position value. Fixed income is not a perfect hedge against equity risk. During the early months of the COVID selloff in March 2020, both stocks and bonds sold off simultaneously. Investors were liquidating everything to cover margin calls. Treasuries were not a safe haven because everyone needed cash equally. The same thing happened during the UK gilt crisis in September 2022 when leveraged pension funds faced margin calls on their liability-driven investment strategies. Credit risk models are backward-looking by design. They use historical default rates and recovery assumptions. When structural changes occur, like a shift from fossil fuels to renewables, the models do not price in the transition risk quickly enough. A coal producer with a solid BBB rating can default within a year if regulation kills its revenue model faster than the rating agencies adjust.
If you are building a portfolio from scratch, index funds and ETFs are the easiest entry point. A total bond market fund gives you instant diversification across government, corporate, and muni holdings. The expense ratio is usually under 0.05 percent. The tradeoff is that you own everything, including the stuff you might not want. Individual bond purchasing requires more capital to achieve the same level of diversification and introduces reinvestment risk at the laddered maturity points.