Individual Economic Agents in Practice
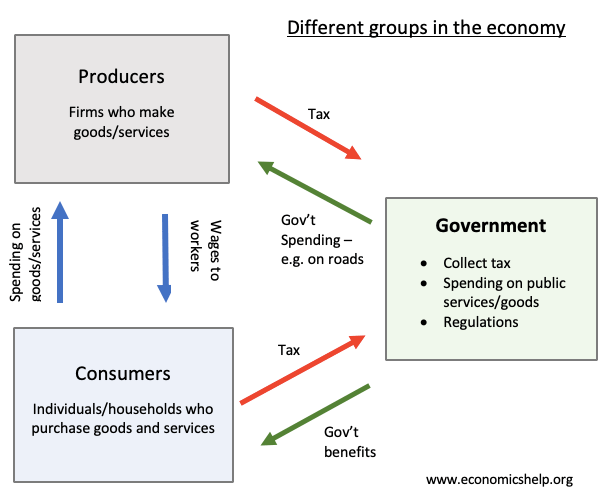
When I first started modeling consumption patterns for a regional housing authority, I needed to figure out who was actually driving demand. The textbooks called them individual economic agents, but the term is fairly loose and the practical application is messier than you would think from an intro microeconomics course. The four standard categories are households, firms, governments, and the foreign sector. Households supply labor and consume goods. Firms produce and invest. Governments collect taxes and spend. The foreign sector handles cross-border trade and capital flows. That is the framework. Getting it to work on real data is another thing entirely. Households include virtually everyone, but they do not all behave the same way. A dual-income family in a metro area with a mortgage behaves differently from a retired household drawing from fixed assets. In my work modeling local labor markets, I found that treating all households as a single aggregate unit produced predictions that were wildly off. Wages shifted in one direction but employment didn't move as expected because the aggregate assumption masked the fact that different household types responded differently to the same incentives. Firms range from sole proprietorships to multinational corporations, and the distinction matters enormously for any kind of accurate modeling. A small retail business responding to a local minimum wage change will make entirely different decisions than a manufacturing firm with capital-intensive production. The elasticity of substitution between labor and capital determines how a firm actually reacts when input prices shift. Most back-of-the-envelope calculations ignore this and end up with predictions that look reasonable but fall apart under scrutiny.
Governments at different levels operate as distinct agents with separate budget constraints and objective functions. A municipal government makes infrastructure and zoning decisions. A state or provincial government handles education and transportation. A national government manages monetary policy, defense, and transfer payments. Each level constrains and interacts with the others. When I was building a model for a state-level economic development program, the federal tax credit provisions completely changed how local firms responded to incentives. The state-level analysis alone produced a net positive estimate that was wrong by roughly forty percent once federal spillovers were accounted for. The foreign sector encompasses residents and businesses in other countries that engage in trade or financial transactions with the domestic economy. Exchange rate movements, tariff changes, and shifts in foreign demand all flow through this channel. A depreciation of the domestic currency does not uniformly benefit all firms. Exporters gain, but import-dependent firms face higher input costs. The net effect depends on the composition of trade and the elasticity of demand for exports and imports.
Working With Agent-Specific Data
The hardest part is usually getting data that reflects individual agent behavior rather than aggregates. Macro-level statistics smooth over the variation that actually drives outcomes. I ran into this repeatedly when trying to evaluate a targeted employment subsidy. The official employment figures showed modest improvement overall, but the program evaluation required understanding how different household types responded. One-parent households increased labor supply significantly. Two-earner households largely did not. The aggregate mask made the program look more effective across the board than it actually was. Microdata sources like household surveys and firm-level administrative records are necessary but imperfect. Household surveys suffer from recall bias and nonresponse. Firm-level data often has confidentiality restrictions that limit how finely you can break things down. Income underreporting is another persistent problem, especially for self-employed households and smaller firms operating in cash-heavy sectors. I found that triangulating between survey data, tax records, and transaction-level data from payment processors reduced estimation error substantially compared to relying on any single source. Behavioral assumptions also introduce significant error. Standard models assume rational utility maximization with consistent preferences, but actual decision-making involves bounded rationality, framing effects, and status quo bias. A household might delay retirement not because of a calculated optimization but because of inertia. A firm might maintain an existing supplier relationship despite better alternatives available because switching costs feel larger than they objectively are. Ignoring these behavioral components leads to systematic prediction errors, particularly for policy interventions that require agents to change established patterns of behavior.
Get the Full Details

Pitfalls To Watch For
One common mistake is assuming that individual agents can be aggregated without loss of information. The aggregation problem is real and often severe. Different agents face different constraints, have different expectations, and respond differently to the same shocks. An aggregate model might capture average behavior well but miss distributional effects that matter for policy. Another mistake is treating the boundaries between agent categories as fixed. Households can become firms when someone starts a side business. Firms can behave like households when family-owned businesses pool personal and corporate finances. Government entities can act like firms when they compete in market activities. Time lags are another issue that gets underestimated. Policy changes take time to affect agent behavior. A tax credit announced in one quarter may not show up in spending data for three or four quarters as households and firms adjust their plans. Expecting immediate responsiveness produces models that look wrong in the short run even when they converge to reasonable long-run estimates. Discount rates also vary considerably across agent types. Households with low income tend to discount the future much more heavily than well-capitalized firms, which affects how they value delayed benefits versus immediate costs. There is no clean way to solve every identification problem in agent-level modeling. Sometimes the data simply does not contain enough variation to separate competing explanations. In those cases, adding more complex behavioral assumptions tends to produce overfit models that look impressive internally but fail on new data. A simpler structural model with clearly stated assumptions often outperforms a flexible reduced-form approach that claims to capture everything. The tradeoff is between interpretability and fit, and I have found that interpretability usually wins out in practice because policy decisions require understanding mechanisms, not just predicting outcomes.