Building a Functional Excel Amortization Calculator
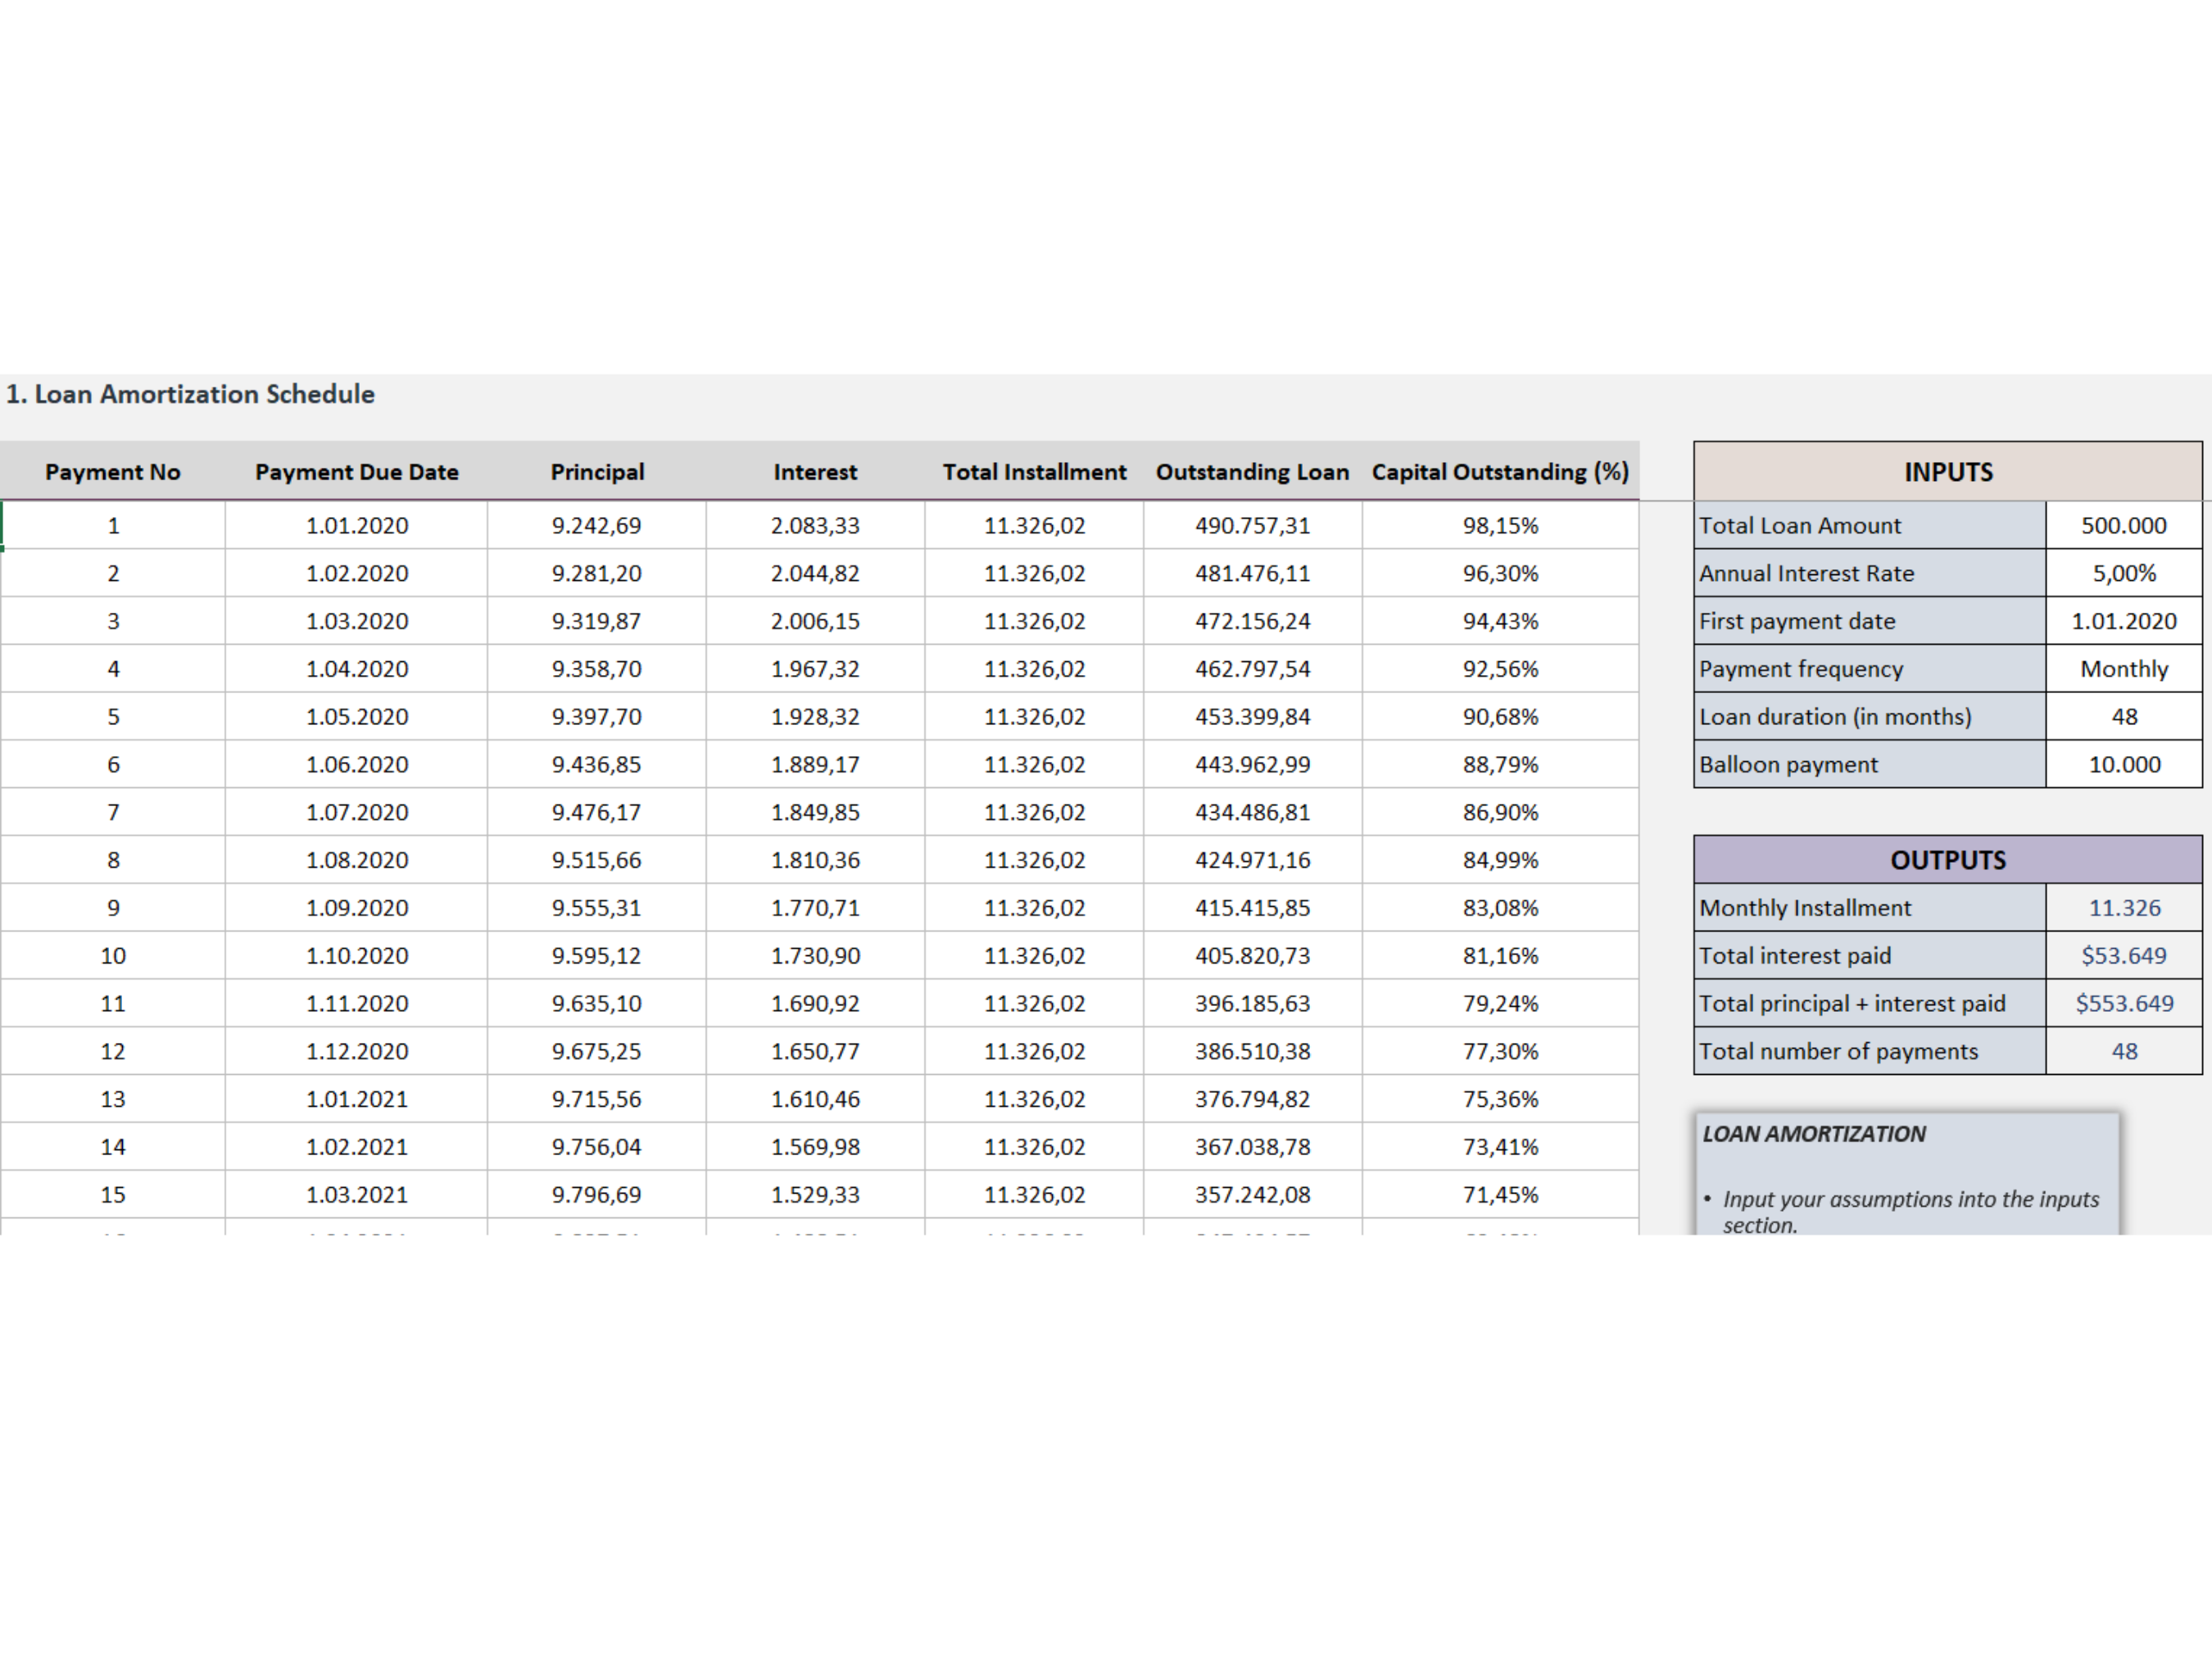
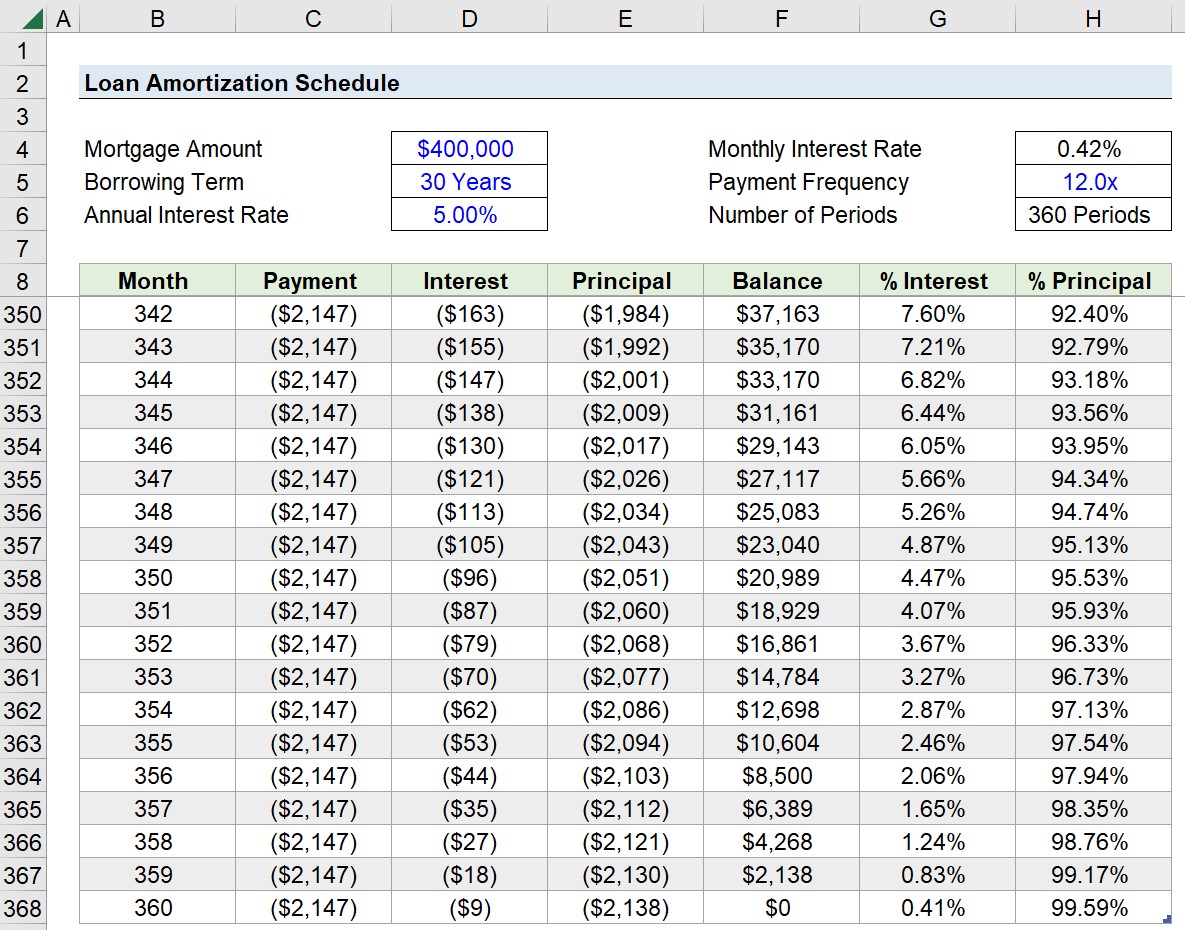
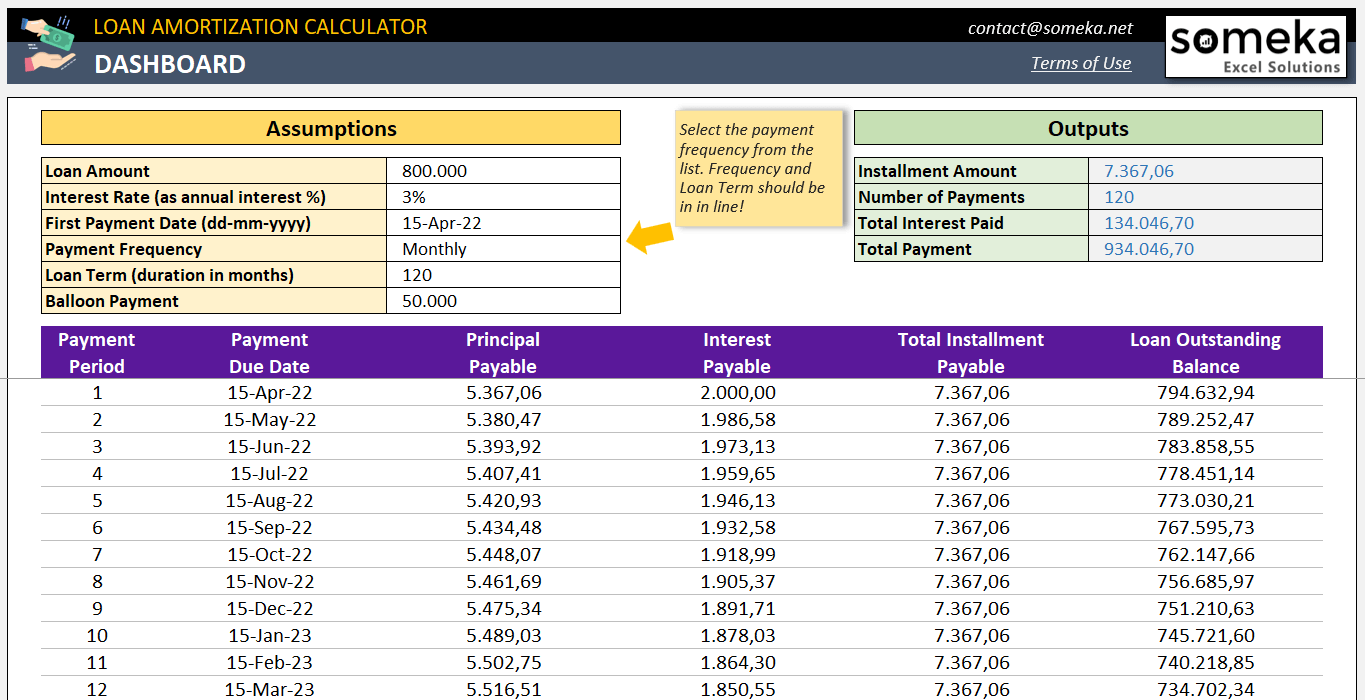
Most people try to build an amortization table from scratch by typing out formulas row by row. It takes forever and breaks easily. The faster approach is to combine a few built-in financial functions into a structured table. I spent years fixing broken loan calculators at my last job before I stopped rewriting them from scratch and started using a template-based approach. Here is the practical layout. Put your inputs in the top section: loan amount, annual interest rate, loan term in years, and start date. Then build a table below with columns for period number, payment date, beginning balance, principal portion, interest portion, total payment, and ending balance. The trick most people miss is that PMT calculates the total monthly payment automatically. You do not need to hardcode the formula for it. Use =PMT(rate/12, nper*12, -loan_amount) and it spits out a consistent monthly figure. The rate needs to be divided by 12 because PMT expects a per-period rate, and nper multiplies years by 12 for total months. Negative loan amount forces the payment to display as a positive number, which reads cleaner on the spreadsheet.
For the principal portion in each row, use =PPMT(rate/12, period_number, total_periods, -loan_amount). For interest, =IPMT(rate/12, period_number, total_periods, -loan_amount). The period_number increments down the rows. Beginning balance starts as the full loan amount and subtracts the cumulative principal paid so far. Ending balance becomes the next row's beginning balance. That loop is what makes the table work without manual entry. I ran into a specific problem once with a commercial loan that used a 360-day year convention instead of the standard 365. Excel's PMT and PPMT functions assume equal periods and do not account for day-count fractions. The amortization schedule I built was off by several hundred dollars over the life of the loan because the bank was calculating interest differently than the formula assumed. The workaround was to keep PMT for the payment amount but switch to a manual interest calculation: =BeginningBalance * (AnnualRate/360) * DaysInPeriod. It added complexity but matched the actual contract terms exactly.
Common Pitfalls When Building These Tables
The biggest mistake I see is referencing the wrong cell ranges when copying formulas down. PPMT and IPMT require the period argument to be absolute or correctly relative. If you copy the formula down without adjusting, every row returns the same value and you spend an hour debugging what looks like a broken formula. It is never broken. The reference just shifted wrong. Another issue is rounding. Every payment schedule should round the payment to two decimal places, usually with ROUND(). If you leave it unrounded, the final payment will be a fraction of a cent off and the ending balance will not hit zero. That fractional discrepancy triggers audit flags in any professional setting. Round each principal and interest component as well. Let the last row absorb any remaining rounding difference rather than forcing the math to balance artificially. Prepayment changes everything. The basic structure above assumes a fixed payment with no extra principal. If someone pays additional principal in a given month, the table needs a separate input cell for that extra amount and the principal column must add it. The ending balance drops faster, the interest portion shrinks the next month, and the term shortens. Recalculating the payoff date requires either a goal seek setup or a simple formula that counts rows until the balance reaches zero. Neither is elegant but both work.
Get the Full Details

When This Approach Fails
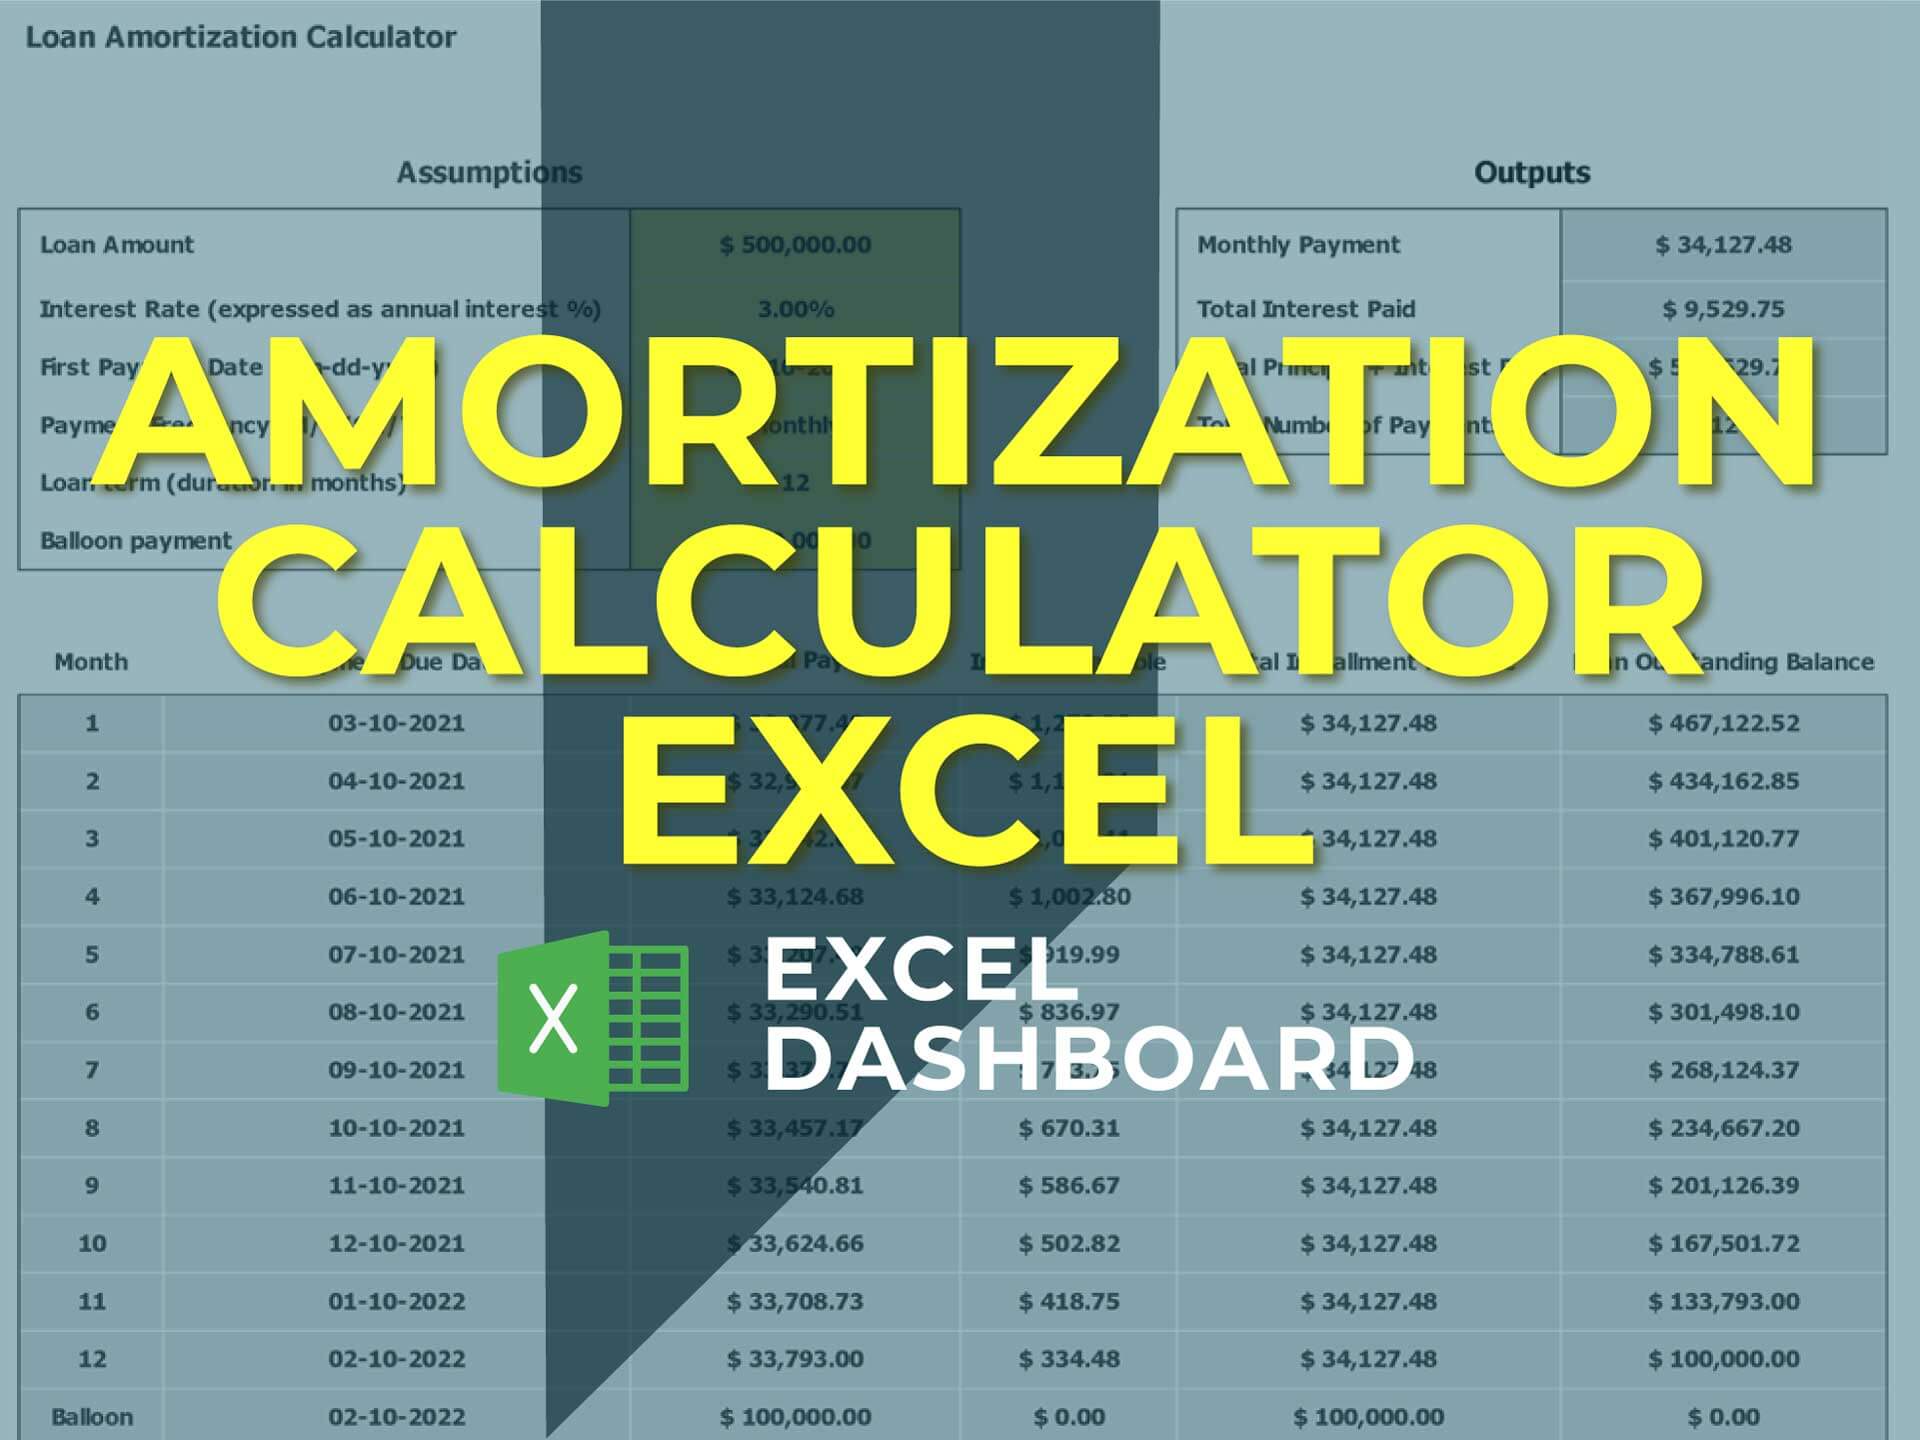
Excel amortization tables break down with variable-rate loans where the rate adjusts at irregular intervals. PMT locks in a single rate. Once the interest changes mid-term, you have to manually recalculate the remaining payment amount and rebuild the table from that adjustment point forward. It is doable but error-prone. For adjustable-rate mortgages or commercial lines with rate resets, a database-driven solution or dedicated loan management software handles the recalculation automatically. Excel can approximate it with VLOOKUP tables mapping rate change dates, but the maintenance burden grows quickly. Another scenario where this falls apart is balloon payment loans. The payment calculated by PMT assumes the loan is fully amortizing over the full term. If there is a large lump sum due at the end, the monthly payment is lower than a standard amortization would produce. You need to adjust the PMT function by treating the balloon amount as a future value parameter: =PMT(rate/12, nper*12, -loan_amount, -balloon_payment). Without that fv argument, the schedule will show a remaining balance at the end instead of zero, and you will need an extra row to clear it.
Practical Recommendations
Use structured references. Convert your input cells and the amortization table into Excel Tables so formulas auto-fill and remain readable. It cuts development time significantly and prevents the common reference errors that happen when you copy formulas across ranges manually. Named ranges for the loan amount, rate, and term make the formulas much easier to audit later. =PMT(AnnualRate/12, TotalMonths, -LoanAmount) is instantly understandable. =PMT(B2/12, B3*12, -B1) is not. If you need a ready-to-use version rather than building from scratch, there are several template sources available online. Search for a free Excel Amortization Calculator template and verify that the underlying formulas match the ones described here before trusting the output. I have seen templates that misalign the period numbering or forget to divide the annual rate, producing schedules that look correct but calculate interest incorrectly. Always spot-check against a known value before relying on anyone else's template for actual financial decisions. The process of building or validating one of these typically takes about 20 to 30 minutes if you know the functions. First-timers often spend an hour or more wrestling with cell references. The payoff is a reusable tool that generates a complete amortization schedule in seconds once the inputs are filled in.