Why your amortization schedules keep breaking
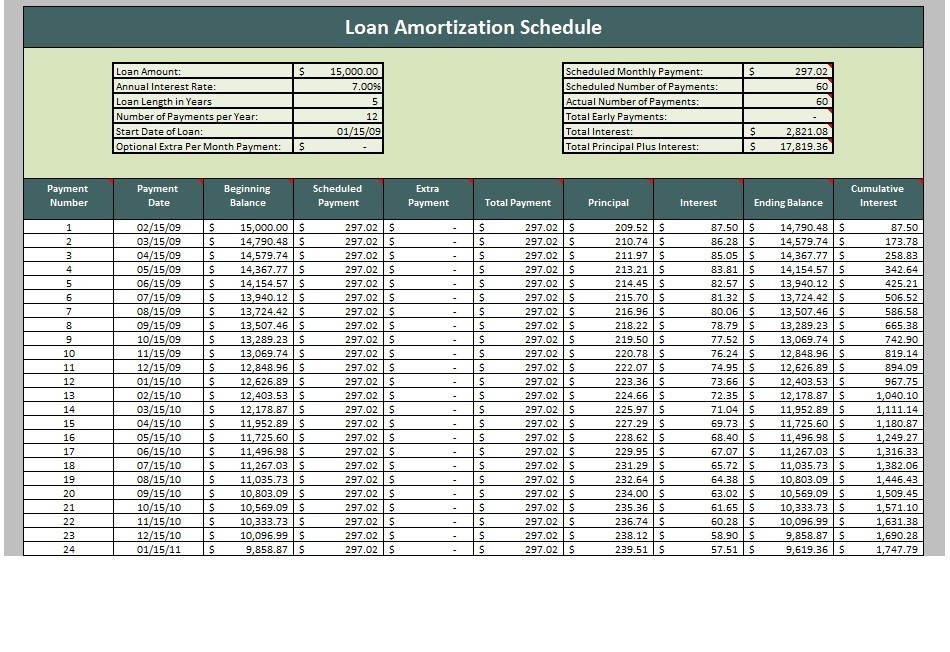
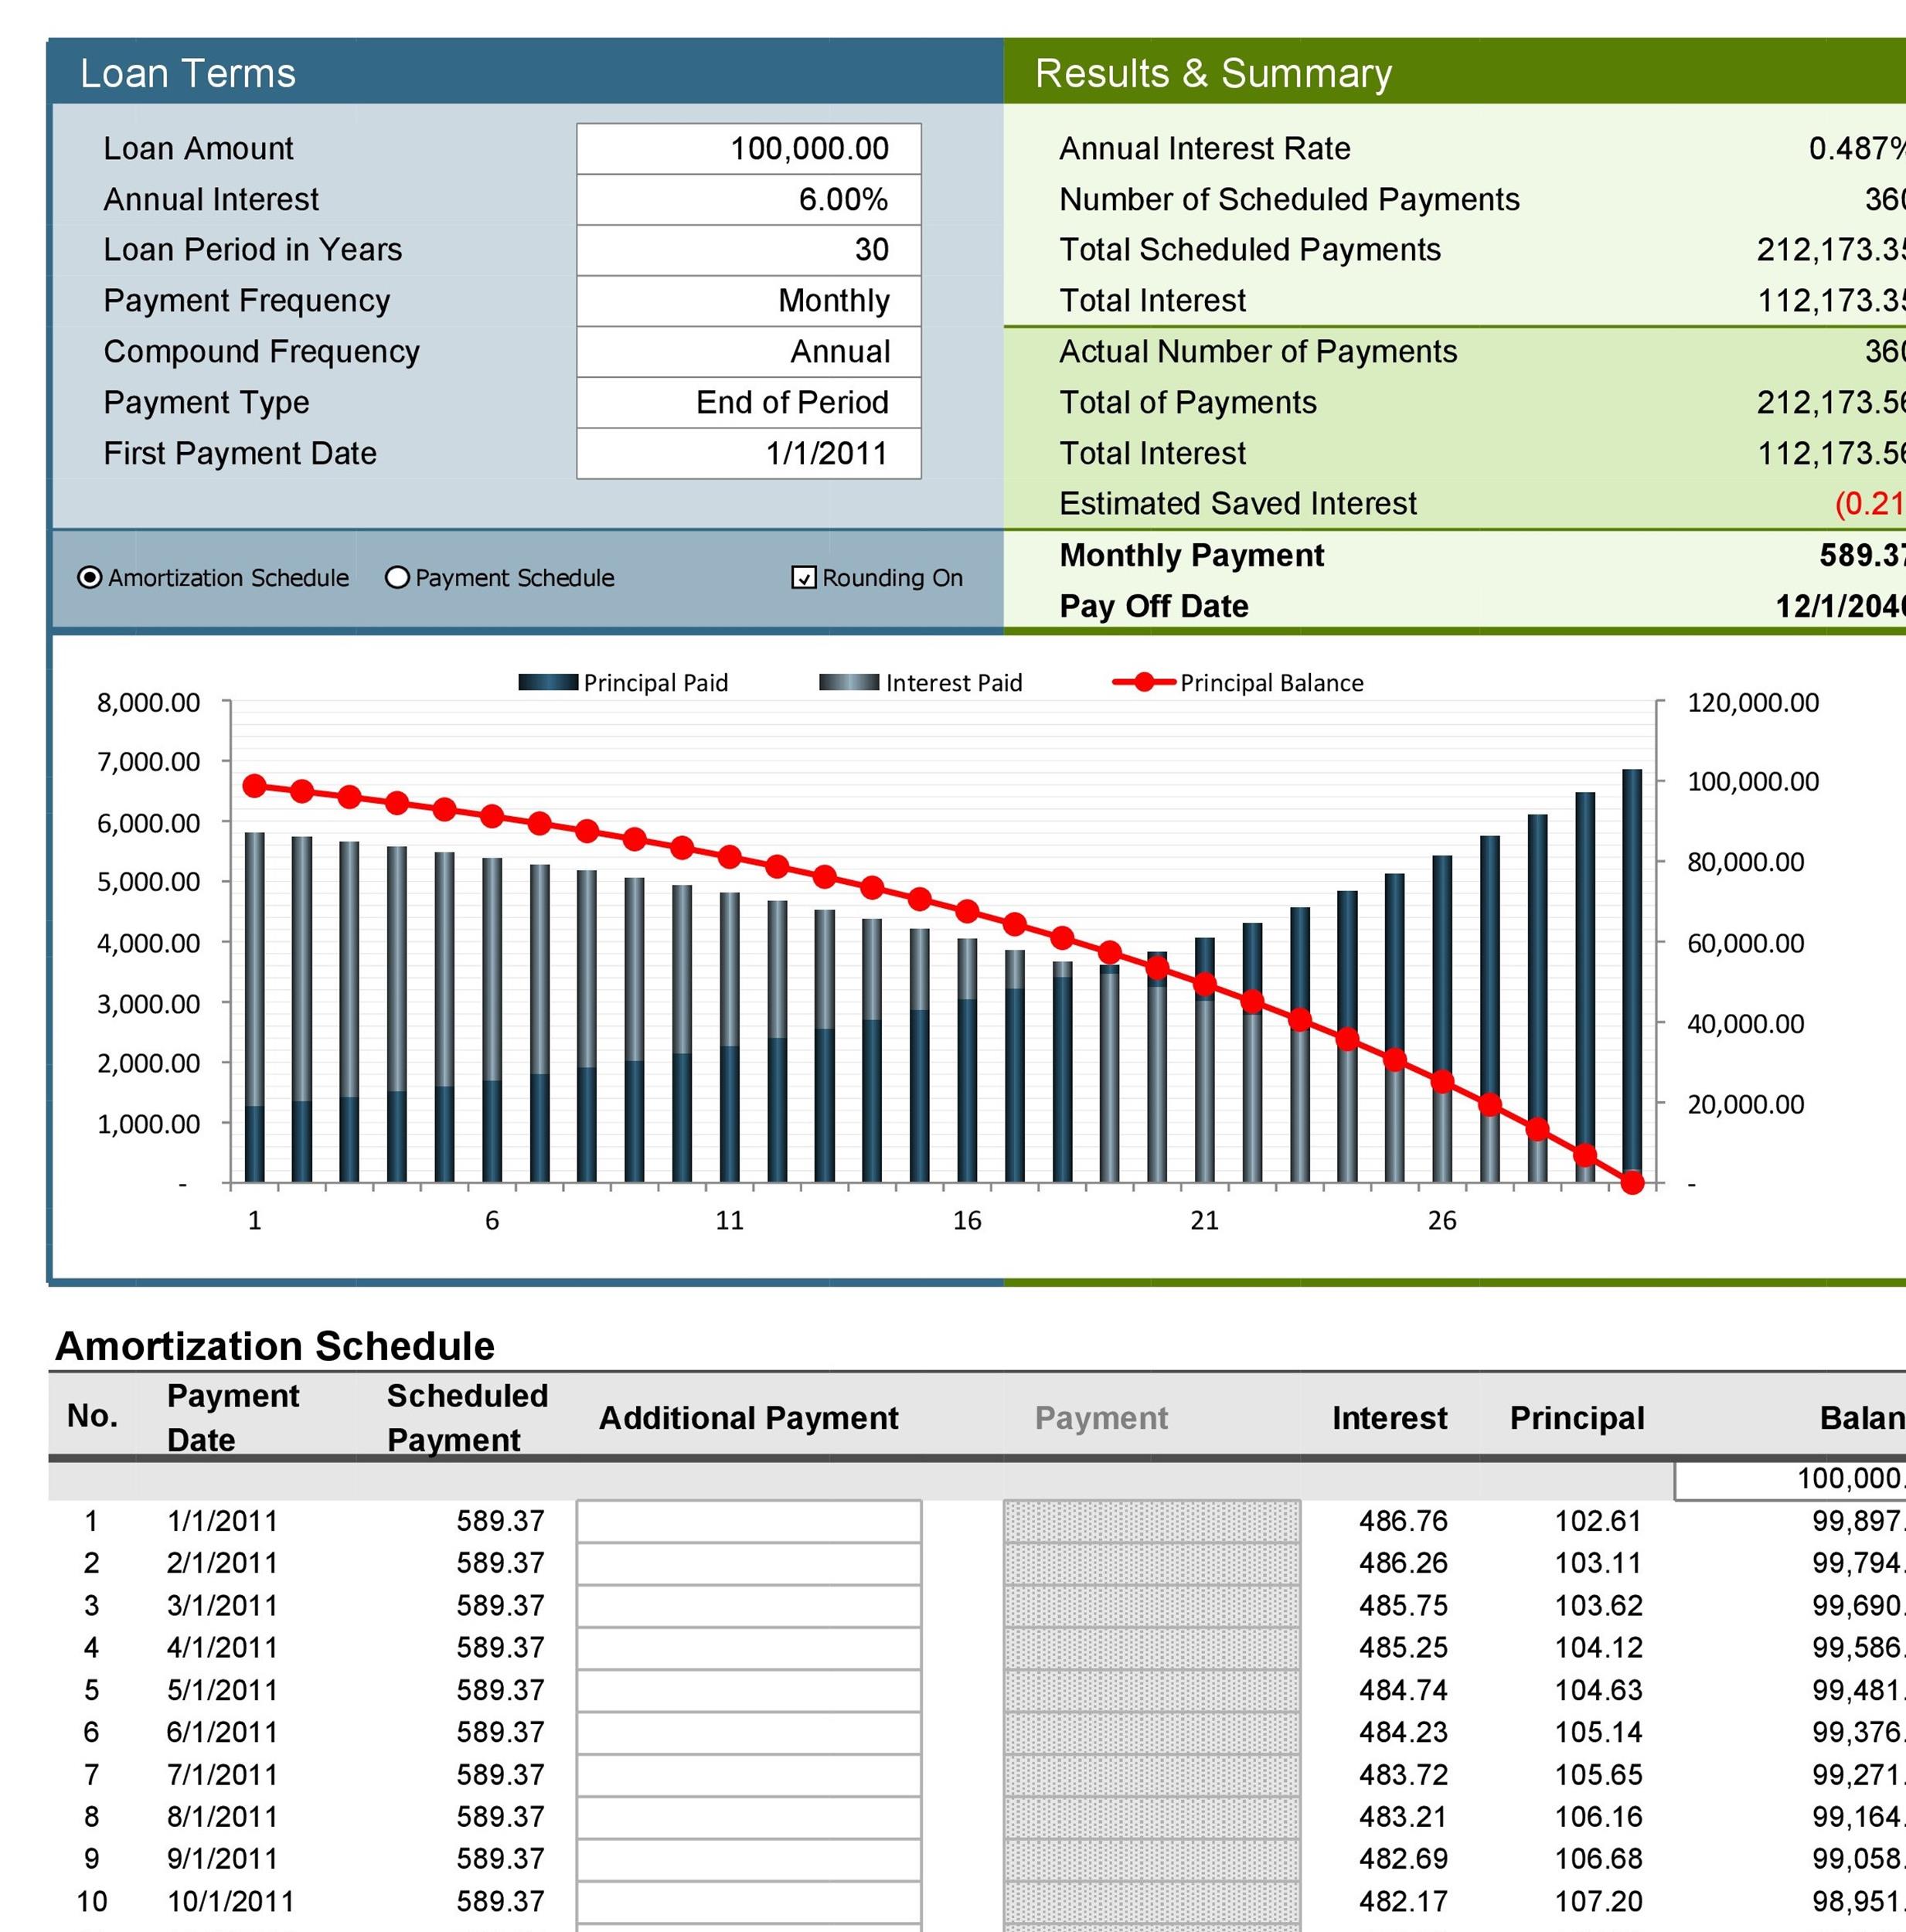
Most people build loan schedules in Excel and spend three weeks debugging balance mismatches before they realize what went wrong. It happens because the PMT function rounds differently than the interest calculation, and suddenly your final row is off by sixty cents. That sixty cents compounds across rows and looks like a structural error when it's just floating point arithmetic. Forget the templates you download from questionable websites. The real mechanics are straightforward, which is part of why people overcomplicate them. You need six columns at minimum: Period, Payment, Principal, Interest, Remaining Balance, and Cumulative Interest Paid. Here is the layout most people get wrong right away. The payment column uses PMT with the rate divided by periods per year, total periods as nper, and the present value as a negative number so the result comes out positive. That negative present value trick is the first thing that catches people out.
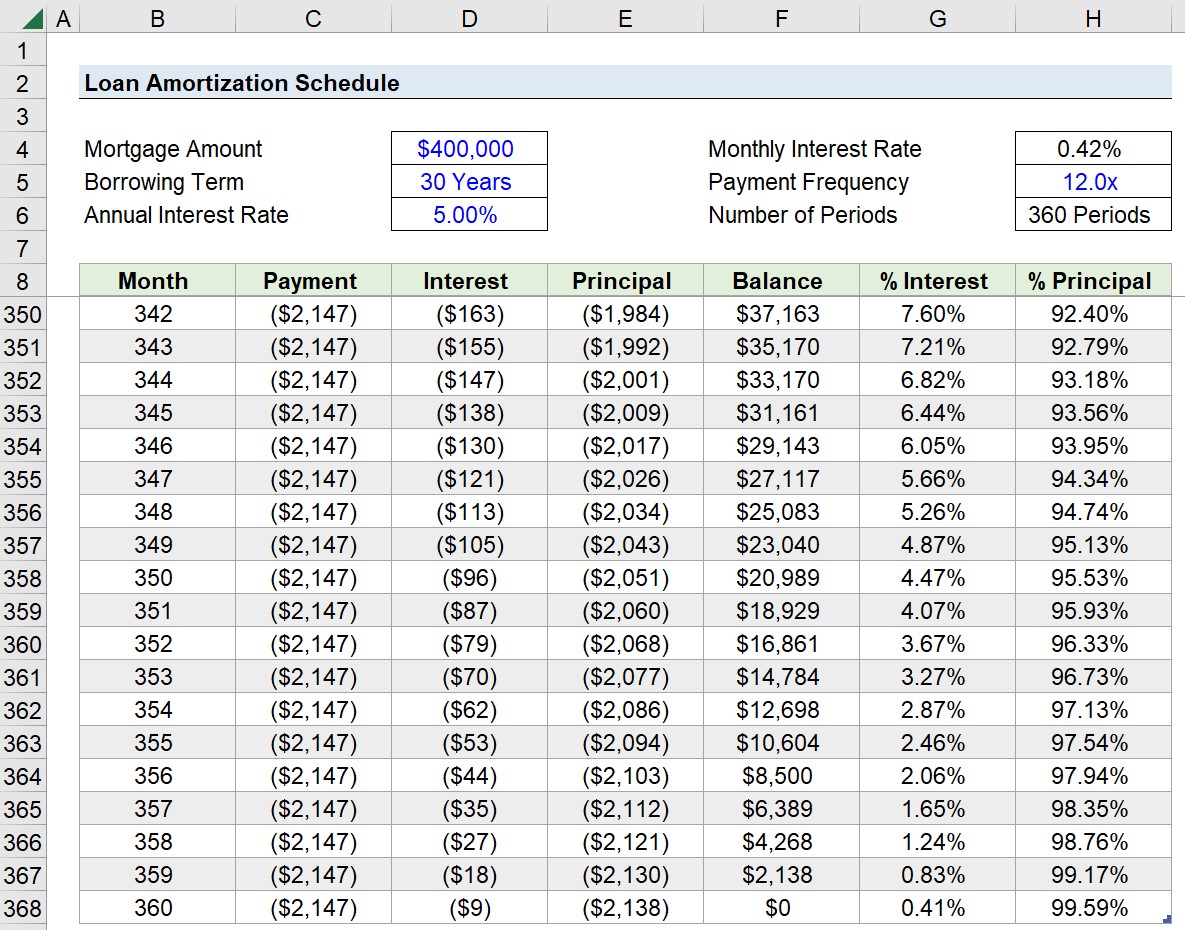
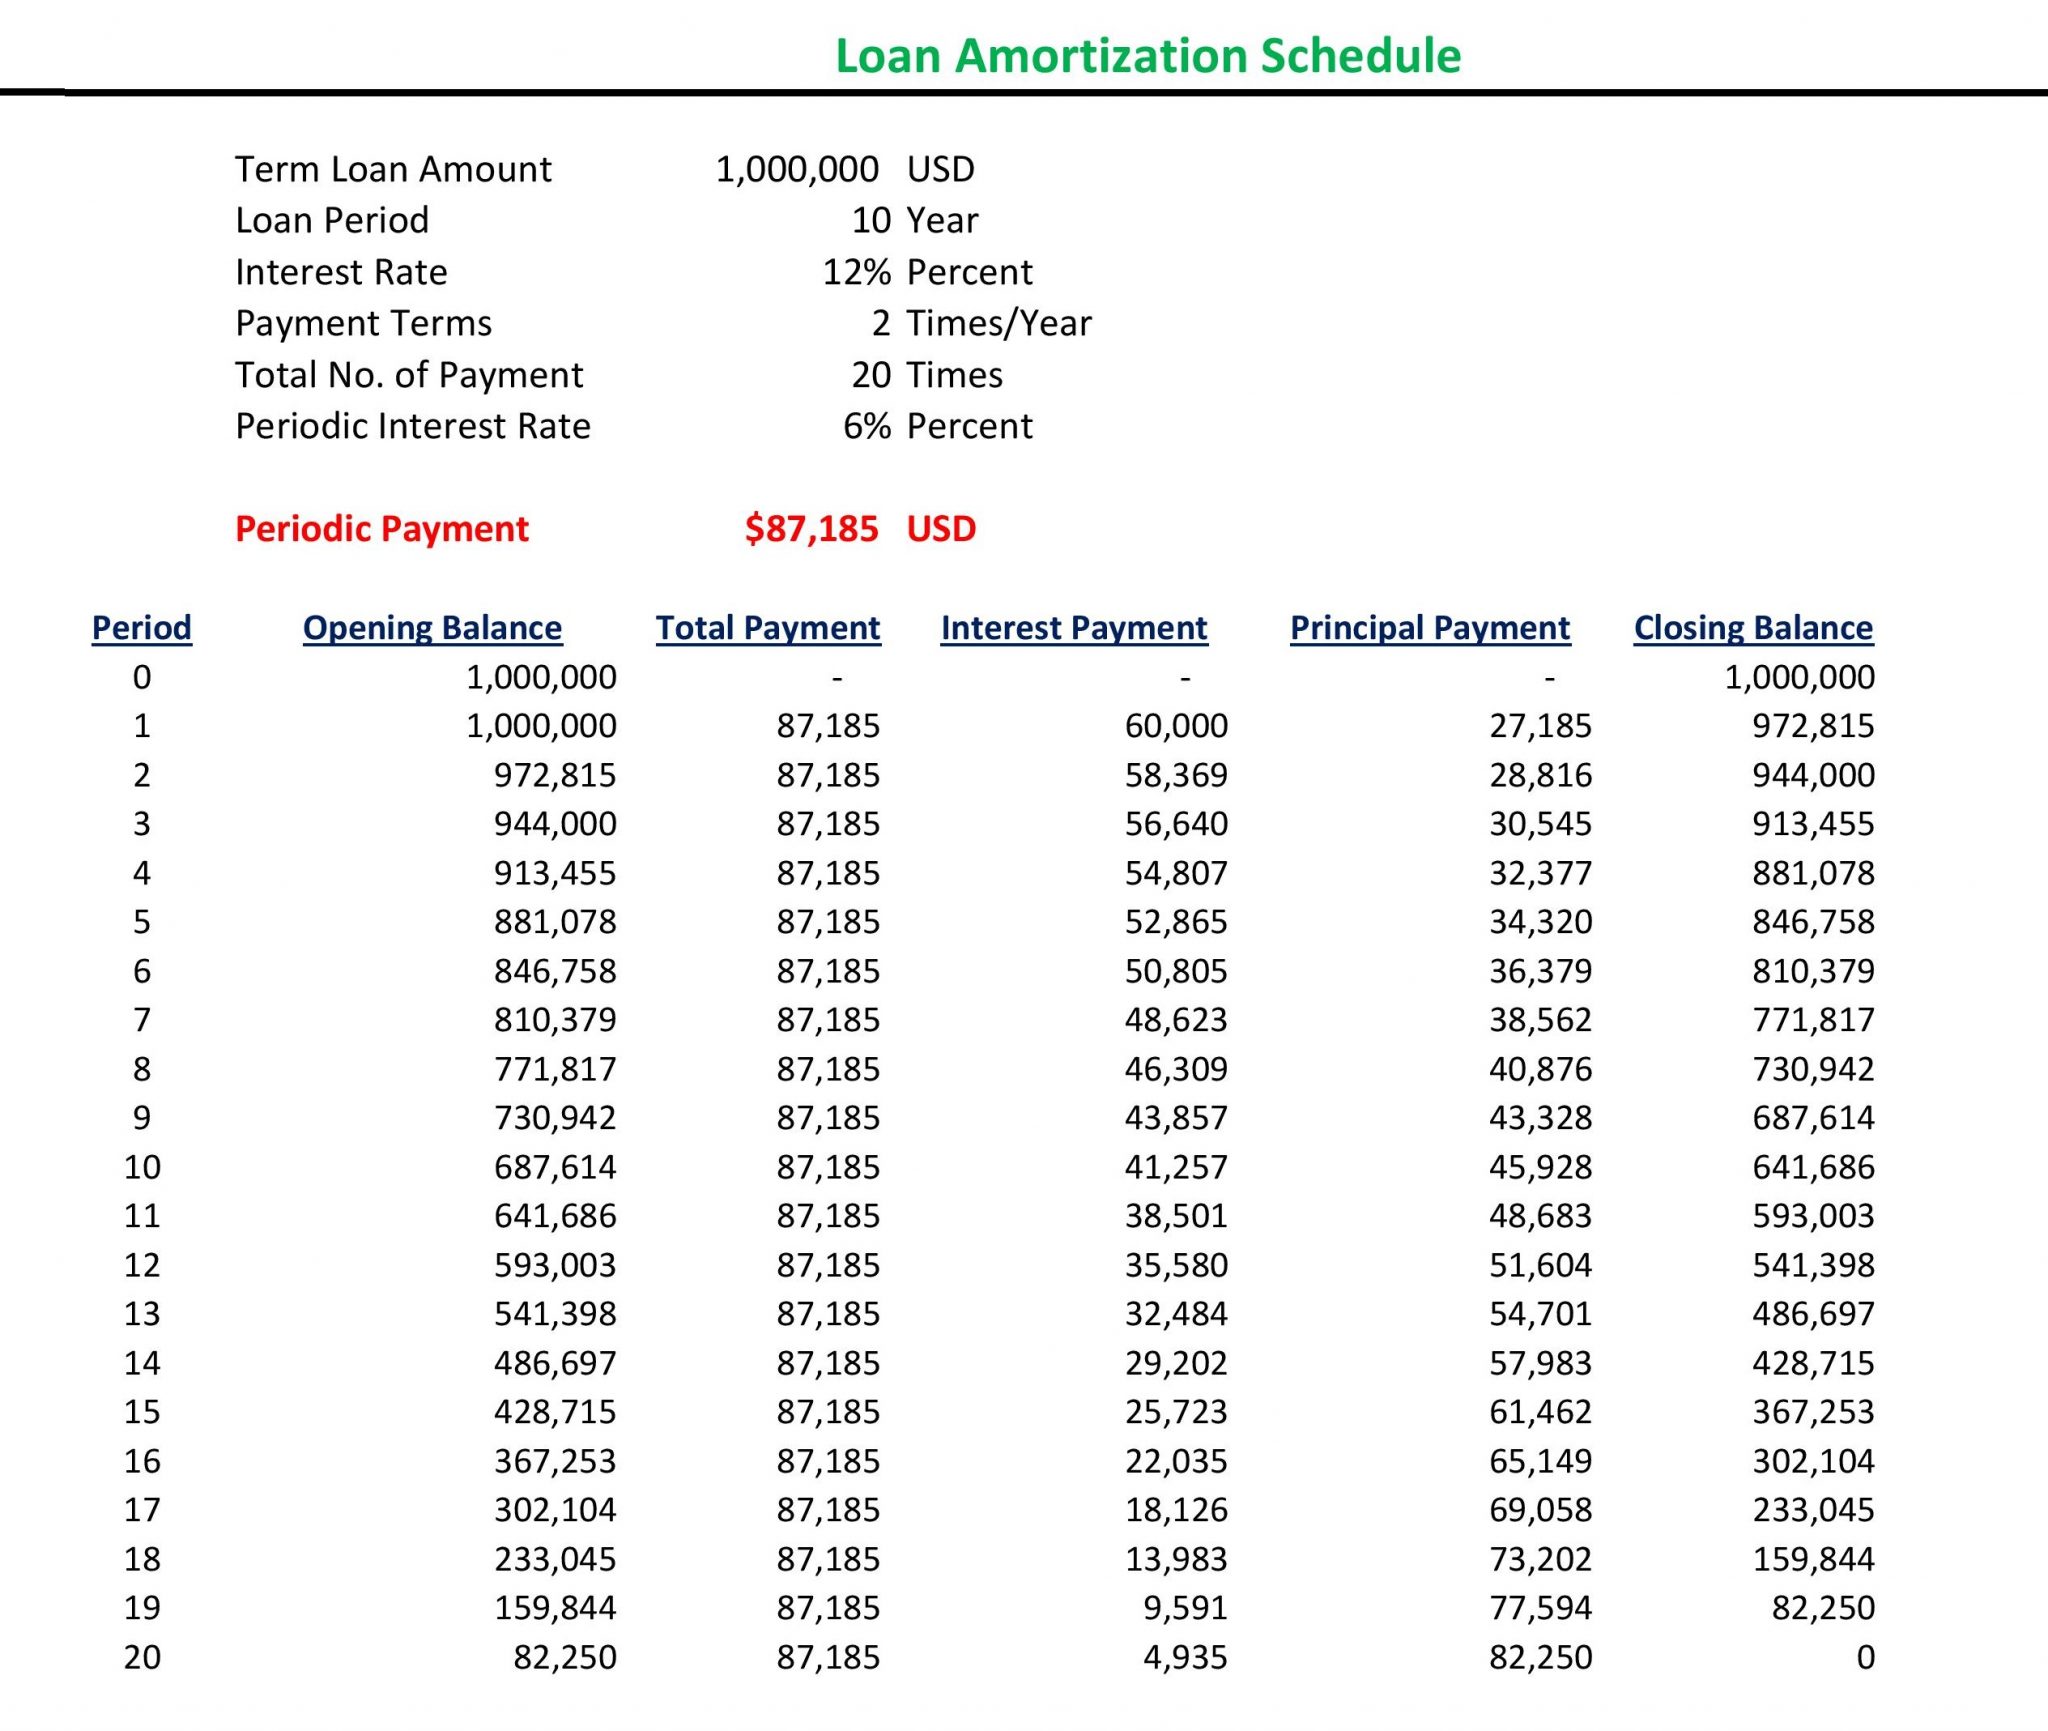
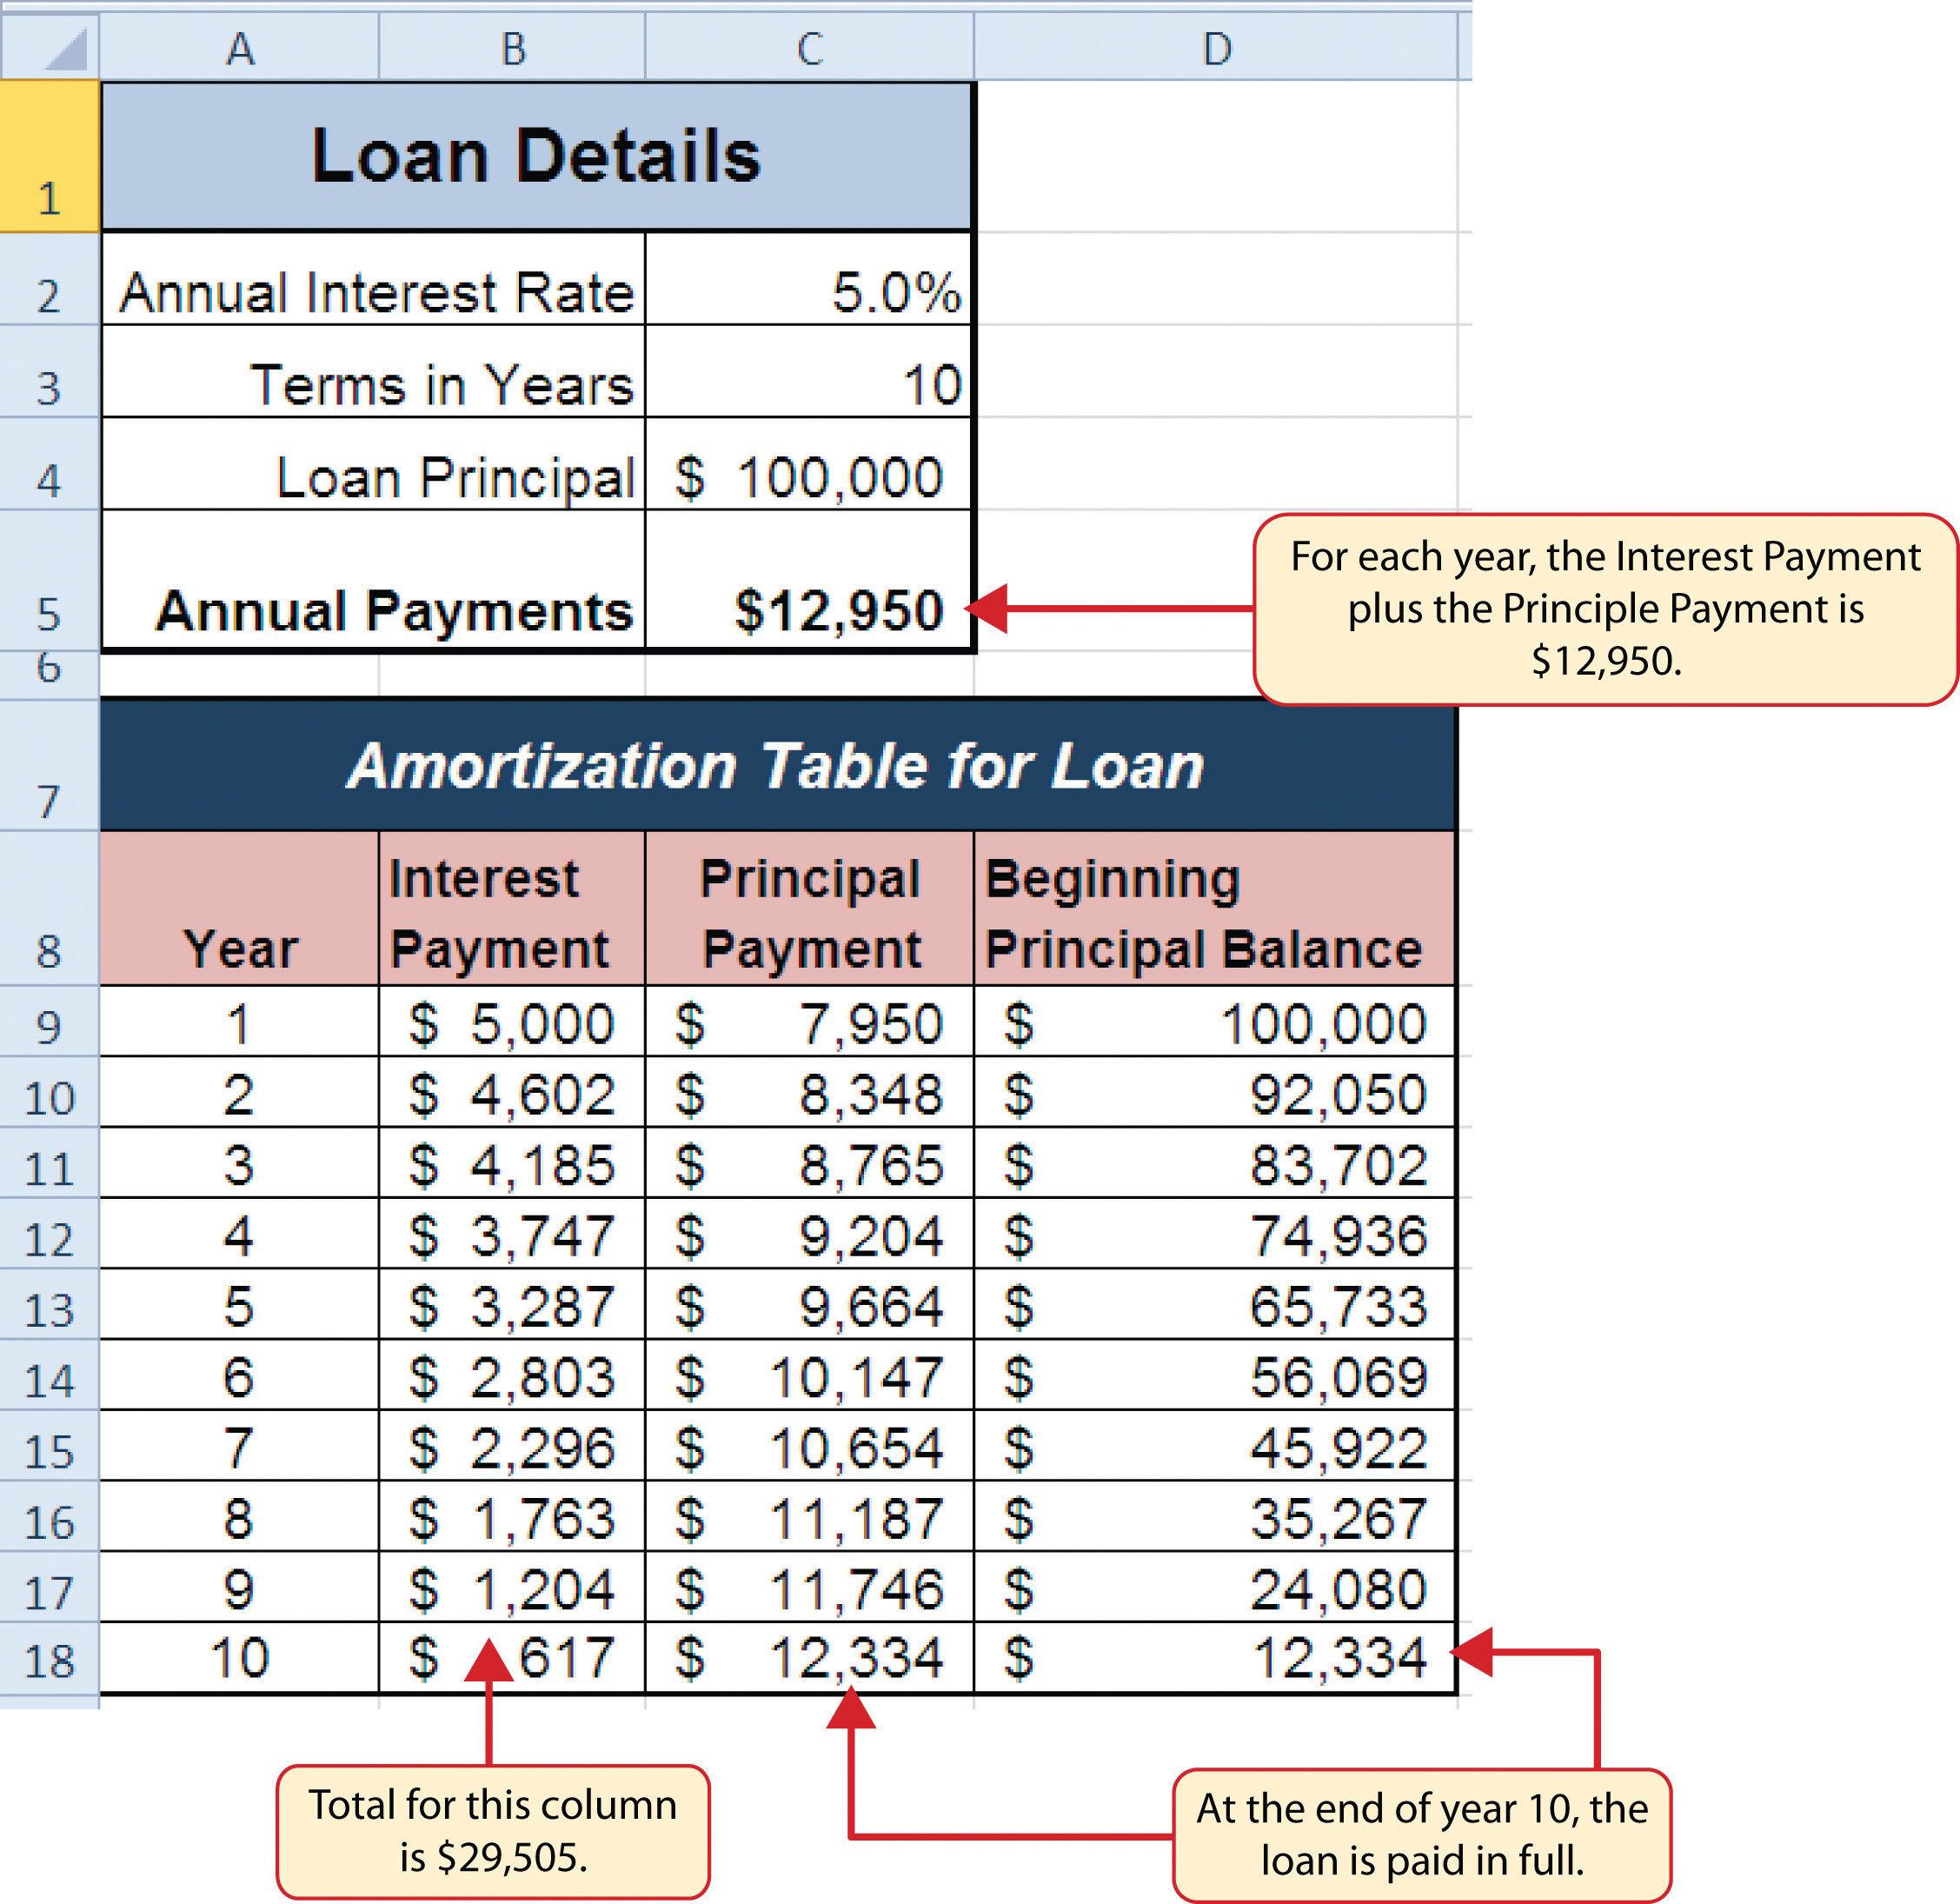
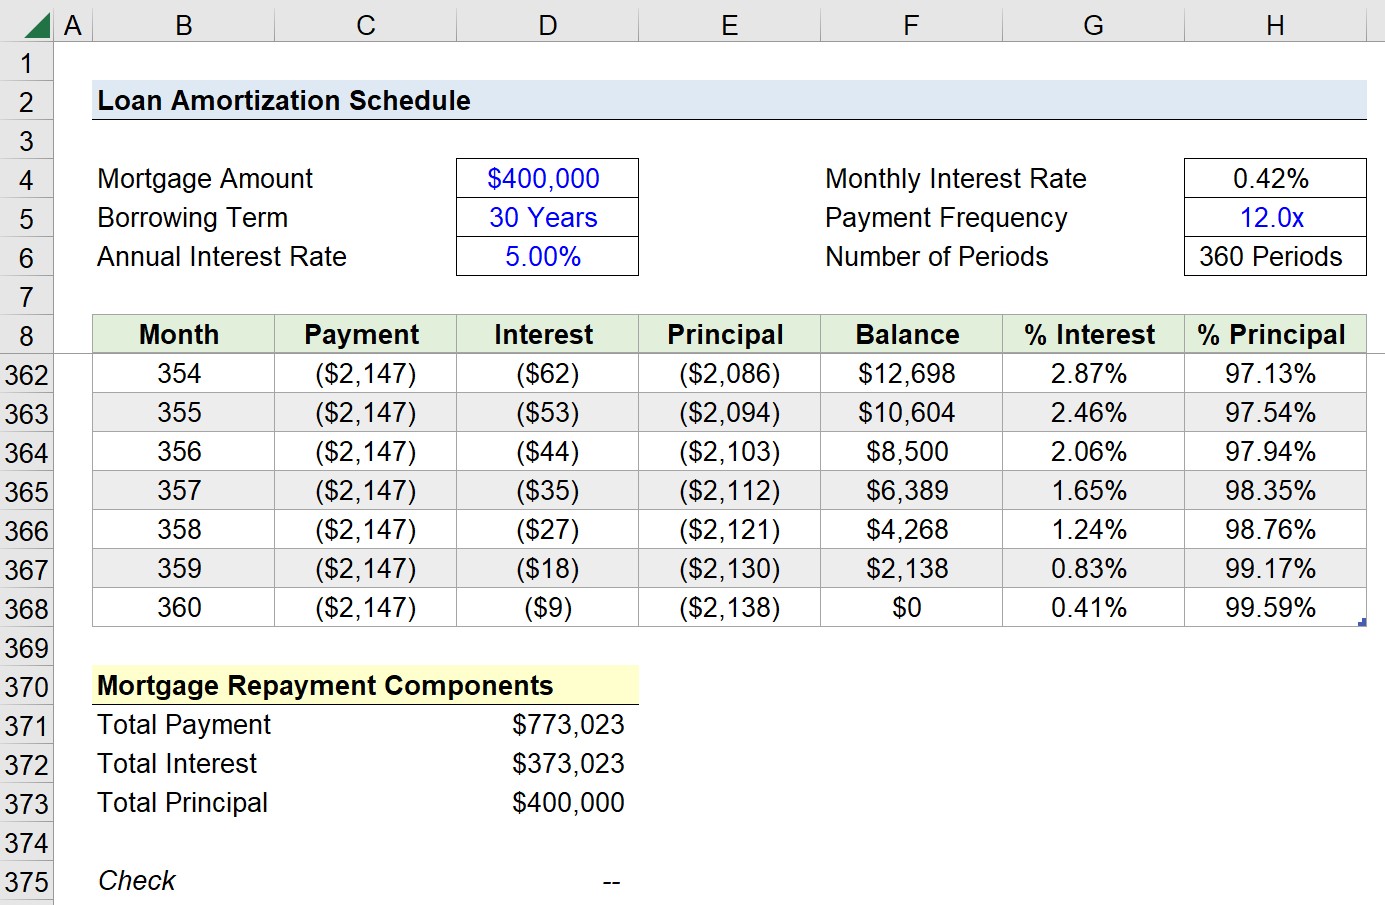
The interest for any given period is simply the remaining balance from the previous period multiplied by the periodic rate. The principal portion is the total payment minus the interest. The new remaining balance subtracts that principal from the old balance. Repeat for every period. The last row sometimes needs adjustment because of rounding, and that is where the real pain starts. I built a schedule once for a commercial mortgage at 6.75 percent over twenty-five years with monthly payments. Everything looked clean until the final payment was four dollars short of zeroing out the balance. The issue was that PMT rounded the payment to two decimals but the internal interest calculations kept more precision. I solved it by setting the final principal payment equal to whatever remained on the balance column rather than forcing it through the standard formula. The schedule balanced exactly after that change.
Details beginners consistently get wrong
The RATE function deserves more attention than it gets. When you know the payment amount, the loan size, and the term but not the interest rate, RATE converges on the answer iteratively. You can supply a guess parameter to speed things up, but if your guess is wildly off the function returns a #NUM! error instead of telling you anything useful. A reasonable starting guess of ten percent usually works for consumer loans. Another thing nobody warns you about: the FV parameter in PMT. If you omit it, Excel assumes zero future value, which is correct for a fully amortizing loan. But if you are modeling a balloon payment or a lease with residual value, leaving FV blank silently gives you the wrong payment. I learned this the hard way on a equipment financing model where the vendor quoted a payment that did not match my spreadsheet. The PV was correct, the rate was correct, but the FV of eight thousand dollars was sitting there unaccounted for, making my calculated payment roughly one hundred twenty dollars too high each month. The PPMT and IPMT functions exist for a reason but they are easy to misuse. They return negative values when the present value is positive because Excel treats cash outflows as negative by convention. If you do not wrap them in ABS or flip the sign manually, your principal and interest columns will show as red numbers and your balance calculations will go negative immediately. Most online tutorials skip this detail entirely.
Get the Full Details
Edge cases that break standard templates
Extra payments are the most common source of schedule corruption. When someone makes an additional principal payment in month fourteen, every subsequent row shifts. A static template does not account for this. You have to either rebuild the entire schedule from that point forward or use a dynamic structure where the remaining balance references the previous row rather than using a fixed multiplier approach. Variable rate loans introduce another layer. If the rate resets annually, you need separate sections for each rate period and you must recalculate the payment using the remaining balance and remaining term at each reset date. The PMT function handles this cleanly if you structure the periods correctly, but the cumulative interest column becomes messy because you are summing across different rates. I use a helper column that tracks the current rate for each period and multiplies it against the prior balance rather than hardcoding the rate into the interest formula. French amortization versus German amortization produce very different schedules even with identical inputs. French amortization keeps the payment constant and shifts the principal interest ratio over time. German amortization keeps the principal payment constant and lets the total payment decrease as interest drops. If a lender sends you a schedule in the German format and you model it using PMT, it will not match. You need to construct the principal column as a flat division of the loan amount by the number of periods, then calculate interest on the declining balance separately.
When Excel is the wrong tool
Amortization schedules with irregular payment dates, daily compounding, or grace periods are where Excel starts to show its age. The standard PMT function assumes end-of-period payments with a fixed compounding frequency. If your loan compounds daily but payments are monthly, the effective rate diverges from the nominal rate divided by twelve, and your schedule will drift. I encountered this with a credit union loan that used the 365-day exact interest method. The published amortization table differed from my Excel model by about two hundred dollars in total interest over the life of the loan. I resolved it by building a day-count column that computed interest as balance times annual rate times days elapsed over 365, then summed to the payment date. It added significant complexity but produced a matching result. For high-volume loan portfolios with thousands of accounts, manual Excel models become unsustainable. At that scale, database-driven solutions or dedicated loan servicing software handle the accounting correctly and audit-trail every calculation. Excel is fine for single loans or small portfolios. It breaks down when you need to process hundreds of schedules with varying terms, prepayment penalties, and rate caps simultaneously. The fundamental issue with any amortization model is that it is only as reliable as the assumptions baked into it. Check the day-count convention, verify whether the rate is nominal or effective, confirm the payment timing assumption, and always reconcile the final balance to zero. Skipping any of those steps produces a schedule that looks professional and is structurally wrong.