Building a working mortgage calculator in Excel
Most people download a spreadsheet template, plug in their numbers, and assume the result is final. It isn't. An Excel Mortgage Payment Calculator can give you the right figure for the principal and interest portion of your payment, but it will silently omit escrow, PMI, HOA fees, and any tax adjustments your lender actually charges. The formula itself is simple. The places where it breaks are not. The core of this thing is the PMT function. It takes three essential arguments and two optional ones. Here is the basic shape: =PMT(rate, nper, pv, [fv], [type])
Rate is your periodic interest rate. If your annual rate is 6.5%, you divide by 12 to get the monthly rate. Nper is the total number of payments. A 30-year loan is 360 periods. Pv is the present value, or the loan amount. Fv and type are usually left blank for standard mortgages. Fv is the future value, which defaults to zero. Type is when payments are due: zero for end of period, one for beginning. One detail nobody warns you about until they need it: PMT returns a negative number. This is by design, because the function treats cash outflows as negative and inflows as positive. If you are pulling this value into a report or building an amortization table that feeds other formulas, the negative sign will compound mistakes. Wrap the whole thing in a NEG function or add a minus sign in front. =-PMT(rate, nper, pv) is the form I use on every sheet I build.
How to build an Excel Mortgage Payment Calculator from scratch
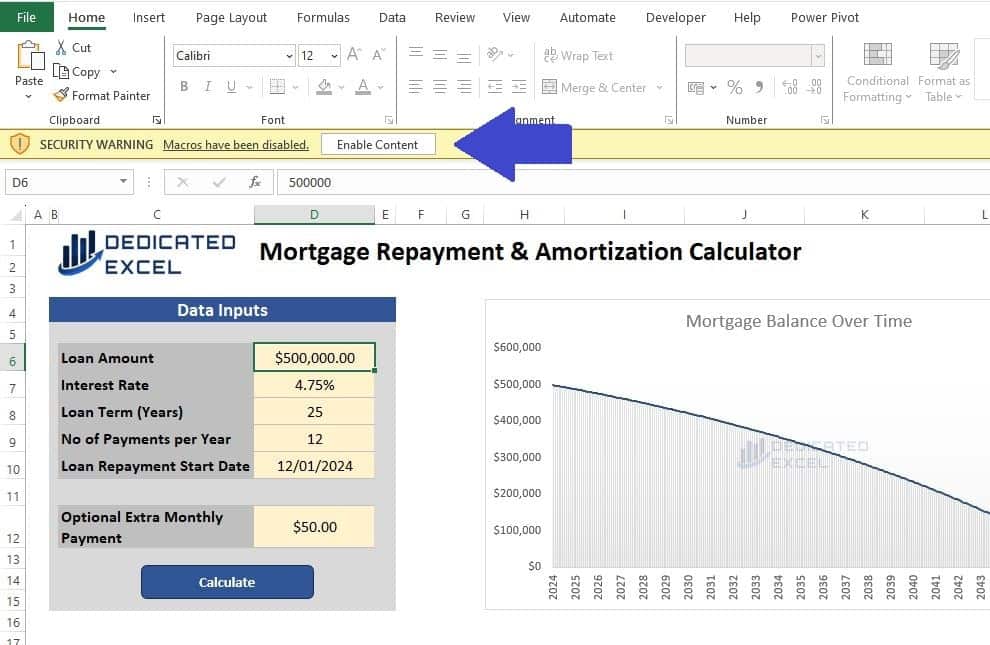
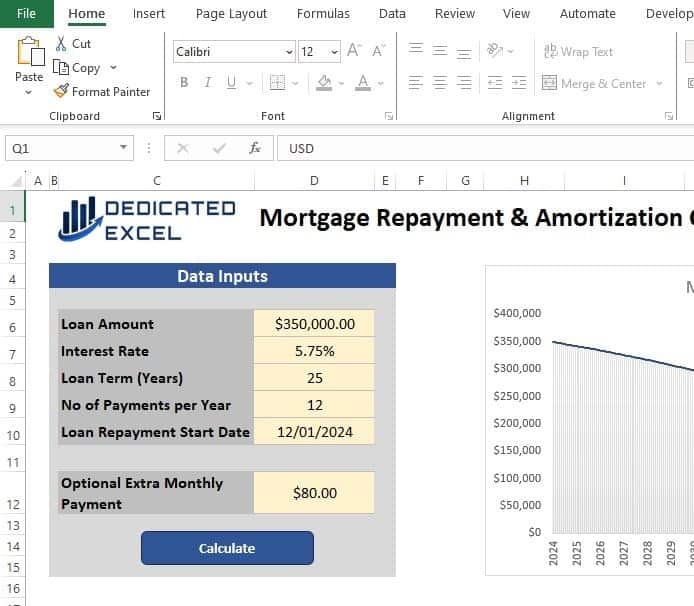
Start with a clean input section. List loan amount, annual interest rate, loan term in years, and start date in separate cells. Name them using the Name Box on the left of the formula bar. Something like LoanAmt, AnnualRate, TermYears. You do not have to name them, but once you stop using cell references like B3 and C3, debugging a broken sheet at 11pm becomes significantly less painful. In a separate cell, compute the monthly rate. Formula: =AnnualRate/12. In another cell, compute total periods. Formula: =TermYears*12. Then place the PMT formula. =-PMT(monthly_rate, total_periods, loan_amount). That single cell now shows your monthly principal and interest payment.
Get the Full Details
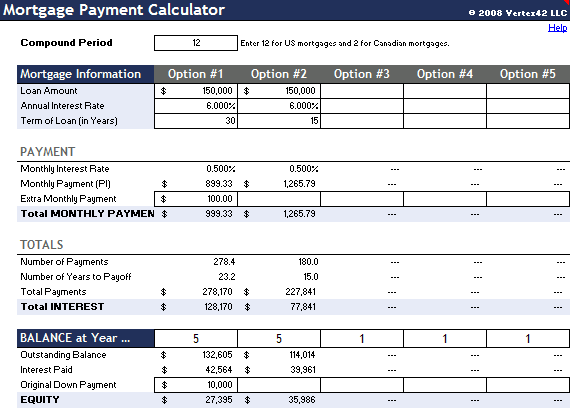
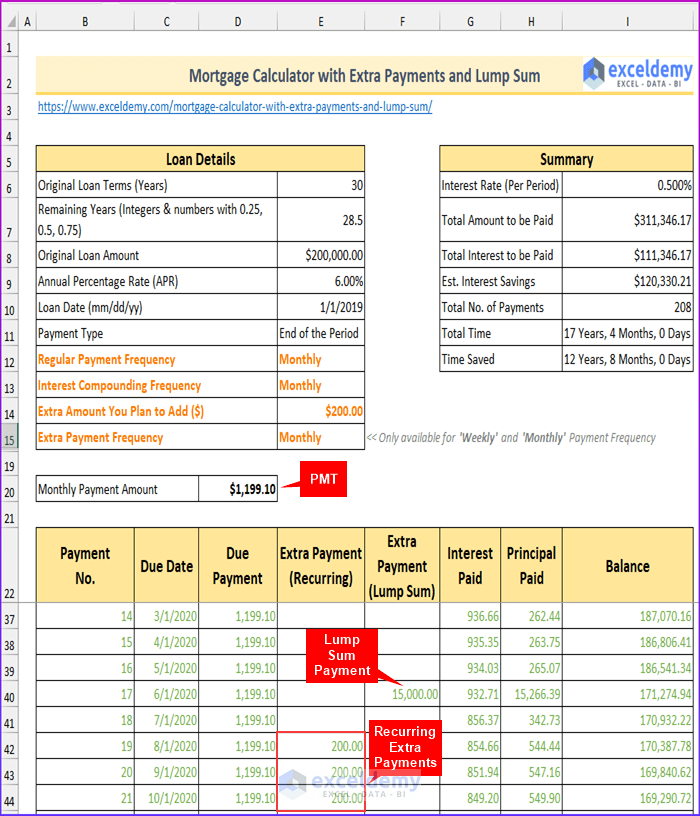
If your loan includes escrow for taxes and insurance, calculate those separately and add them. Typical property tax is annual divided by 12. Insurance follows the same logic. PMI is usually an annual percentage of the loan balance when your down payment is under 20%. Add each component at the bottom of the sheet for a total monthly housing payment. Here is the practical limit most people hit. PMT assumes equal periodic payments at a fixed rate. That works fine for a standard 30-year fixed. It does not work for an ARM where the rate resets, a balloon mortgage, or a loan where you make extra principal payments. I learned this the hard way on a jumbo loan with biweekly payment options. The template showed one payment. The lender's system calculated interest daily using a 365-day year and applied partial-period adjustments when the biweekly schedule shifted leap years. My Excel output was off by about $47 per year because it used a simple 30/360 convention instead of the actual daily interest method the servicer used. The workaround was to build a custom amortization schedule using the IPMT and PPMT functions row by row, feeding each row the remaining balance forward. It took longer to set up, but the numbers matched the statement within a dollar. The IPMT and PPMT functions are worth knowing because they let you see how much of each payment goes to interest versus principal over time. Early in the loan, interest makes up the vast majority. IPMT(rate, period, nper, pv) shows the interest slice for a specific period. PPMT does the same for principal. Running these across 360 rows gives you a full schedule in about ten minutes. Most template download sites sell spreadsheets that do exactly this. You rarely need to buy one.
A couple of things beginners consistently miss. First, the rate argument must match the payment frequency. Monthly payments require a monthly rate. Annual payments require an annual rate. Mixing them produces wildly wrong results. Second, rounding. Excel keeps full precision internally, but displayed values round to two decimal places. If you build an amortization schedule and manually round each payment line, your final balance will not reach zero. It will often land a few dollars off. Force the last payment to absorb the remainder, or use the ROUND function consistently at the schedule level rather than relying on cell formatting alone. Third, negative loan amounts. If you enter the loan amount as a negative number, PMT returns a positive payment. That is mathematically fine, but it flips the sign convention and confuses anyone else who opens the file later. Stick with positive loan amounts and wrap PMT in NEG, or just accept the negative output and label the cell clearly as a payment outflow. There are also scenarios where an Excel Mortgage Payment Calculator simply cannot give you a reliable answer. Variable-rate loans with caps and floors require a schedule built around each adjustment date. Tax credit programs, down payment assistance, or grant structures change the effective cost in ways the standard PMT function does not capture. Government-backed loans sometimes have up-front financing fees rolled into the loan balance, which shifts the PV and therefore the payment. For those cases, either build a custom model or use a lender-provided calculator that already encodes those rules. Another realistic issue: escrow shortages and overages. Your calculated monthly payment will not predict whether your escrow account will run short next year. Property tax reassessments and insurance premium changes happen on local schedules, not on a mortgage amortization timeline. If you need to model escrow variability, you have to pull in actual tax and insurance data and update it manually. The spreadsheet will not do that for you.
For a functional setup, your sheet should contain inputs at the top, the PMT formula in a highlighted cell, a supporting breakdown of escrow and PMI below it, and an optional amortization table if you want to see the balance decline over time. That structure usually cuts the time it takes to stress-test a new loan offer from an hour down to roughly fifteen minutes, assuming you already have a template saved. Keep a master copy. Modify copies, not the original. If you prefer not to build from scratch, there are numerous free templates available online. Look for ones that include a full amortization schedule and at least one cell for escrow and PMI. Avoid templates that only show the PMT result without any breakdown. They are fine for a quick estimate, but they hide the parts of the payment that change year to year and will mislead you if you use them for real financial decisions.