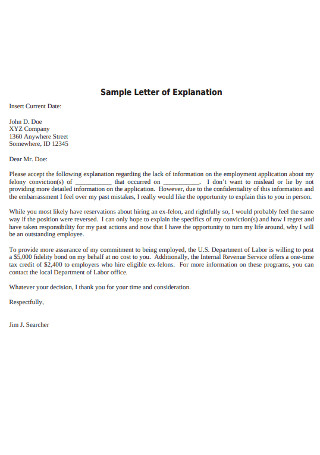
What an Explain Letter Sample Actually Is
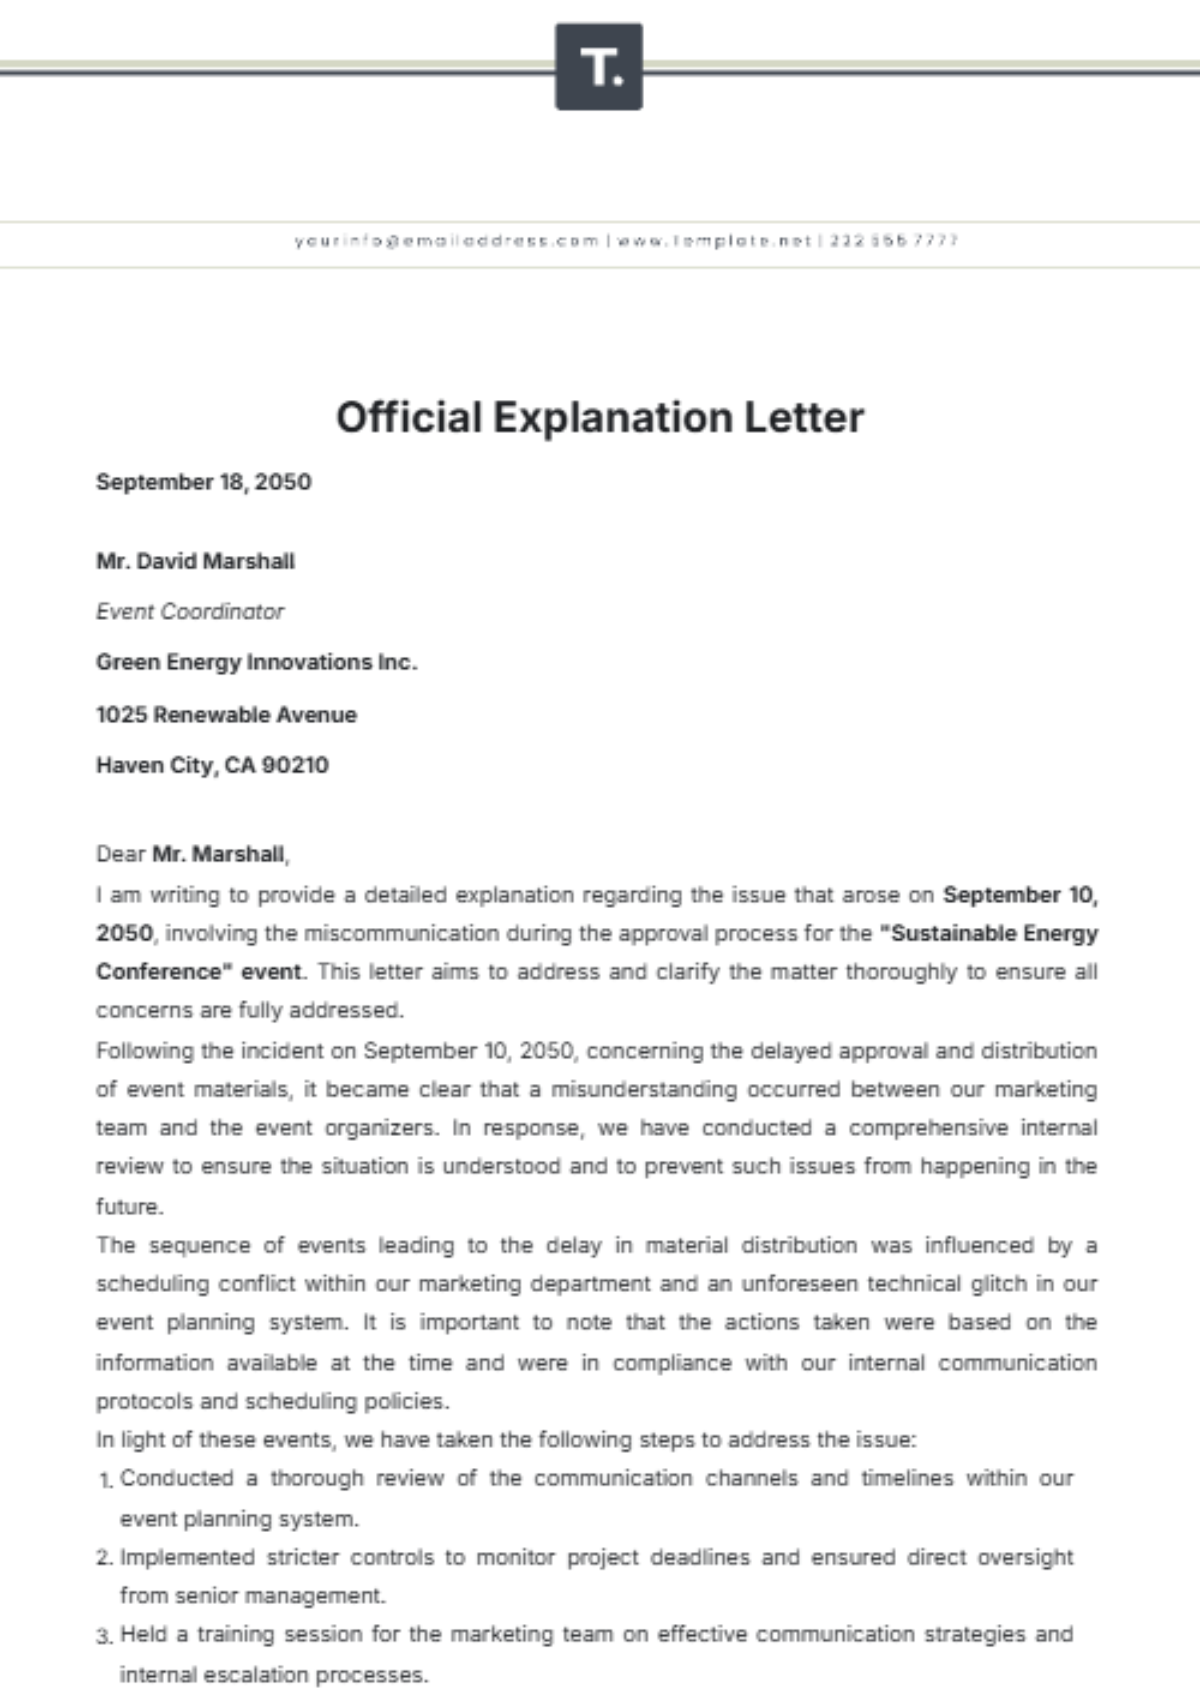
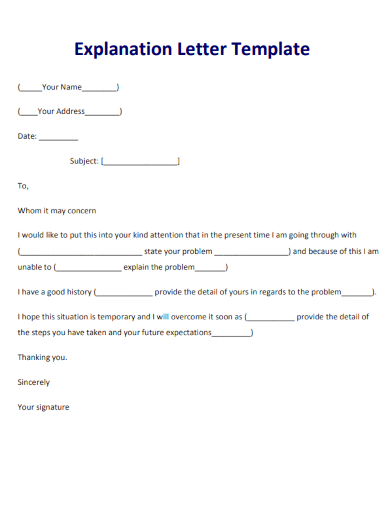
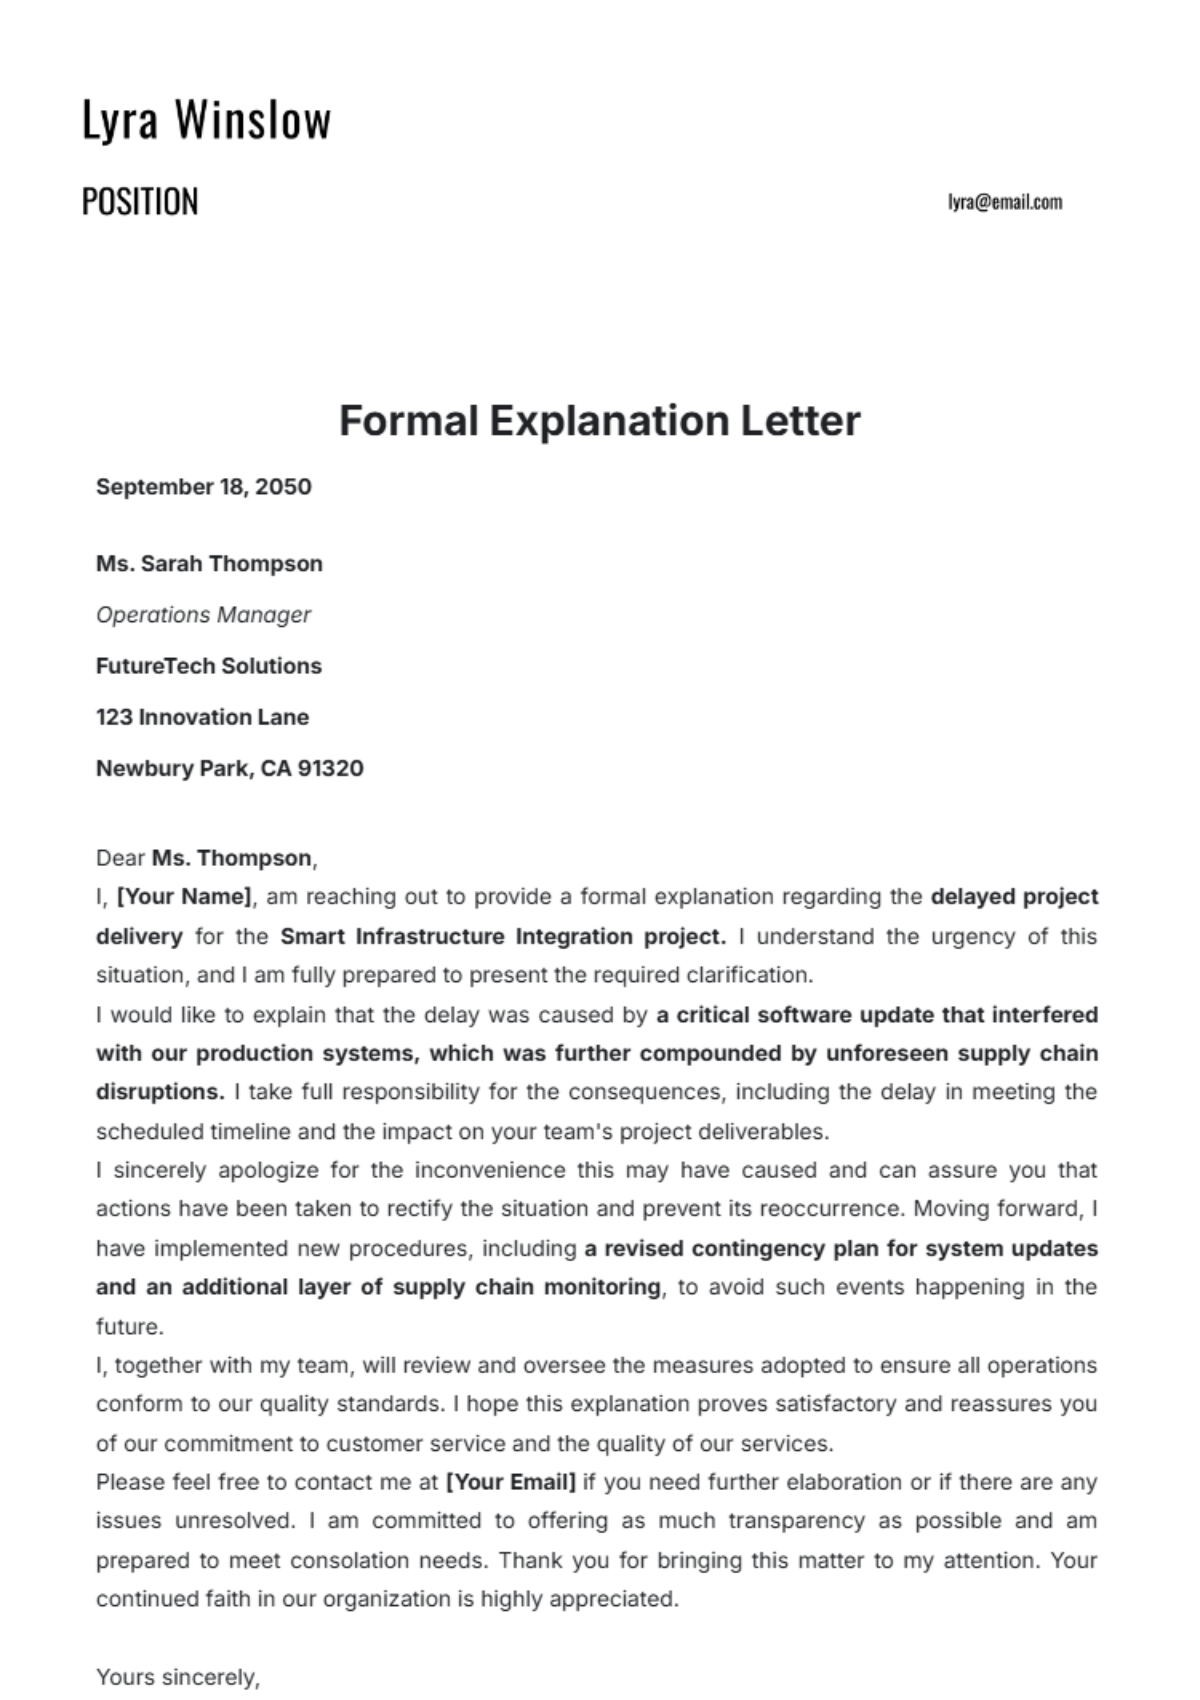
An explain letter sample is a reference document that demonstrates how to structure a letter meant to clarify, justify, or contextualize a situation to a third party. It is commonly used in compliance, legal correspondence, HR disputes, and mortgage or loan reconsiderations. You are not writing from scratch every time. You are taking a template and adapting the facts. The structure is deceptively simple but most people mess up the middle section. You start with a header block — your information, recipient information, date, and subject line. Then you open with one sentence stating the purpose. The body contains three things in order: what happened, why it happened, and what you are requesting. You close with a sign-off and attachments list. I spent years drafting these for clients going through underwriting reviews. The ones that get approved share a specific trait: the gap between the documented fact and the narrative explanation is small. If the underwriter has to guess your reasoning, they will assume the worst. I once had a client whose credit was denied due to a medical collection. The standard template would have them write two paragraphs of explanation. Instead I cut it to four sentences. I included the claim number, the payment date, and a request for removal. The lender accepted it on resubmission in eleven days. The longer version would have added three weeks of back-and-forth.
Here is the practical breakdown of how to build one without wasting time.
How to Build One Properly
Start by gathering the evidence before you write a single word. You need the dates, reference numbers, account numbers, and any supporting documents. I keep a running spreadsheet of all these elements because I have seen people write a solid letter and then realize five minutes later they forgot the claim ID. That forces a revision cycle nobody wants. Write the opening sentence first. It should look like this: "I am writing to provide context regarding [specific item] on account [number]." Not "I hope this letter finds you well." That wastes the reader's attention. The first line determines whether the rest gets read carefully or skimmed. The body paragraph follows a cause-and-effect pattern. State the event. State the cause. State the current status. Do not bury the resolution at the end. Put it in the second sentence if it exists. Lenders and compliance officers process hundreds of these monthly. They scan for the resolution before they read the rest.
Get the Full Details
I ran into a specific edge case last year that I still think about. A client needed to explain a gap in employment that lasted fourteen months. The standard explain letter sample would suggest filling that space with a career break narrative. But the real issue was that the gap caused a income verification failure during a loan application. Writing about the career break missed the actual objection. I restructured the letter to address the income verification specifically, included a letter from the client's spouse confirming household income, and cited the applicable section of the lender's overlay policy. The application moved forward on the first pass. The lesson is straightforward: address the actual rejection reason, not the surface-level topic.
Common Pitfalls That Wreck These Letters
The biggest mistake is over-explaining. Every additional sentence introduces noise. A thirty-line explanation letter is almost always worse than a ten-line version. I have seen people write four paragraphs about a late payment that was late by twelve days due to a bank processing error. Three sentences covers that. The extra text makes the writer sound evasive rather than transparent. Another pitfall is mixing tone. You might switch from formal to conversational mid-letter. Pick a register and hold it. "Hey, I just wanted to let you know" followed by "Pursuant to the terms outlined" reads like two different people wrote it. That inconsistency raises red flags more often than the actual issue does. You also need to understand what an explain letter sample cannot do. It cannot override documented facts. If the record shows a balance owed and you write a persuasive letter claiming it was paid, the letter goes nowhere. These documents work best when they provide context that the raw data cannot convey, not when they attempt to contradict the data outright. I have turned away clients who wanted to use an explanation letter as a substitute for actual documentation. That approach never works and it damages credibility for future requests.
When to Use One vs. When to Do Something Else
Use an explain letter sample when you need to add narrative context to an existing record. Do not use it when you need to correct a factual error in the record itself. That requires a formal dispute or correction request, which follows an entirely different process. Confusing the two will slow you down and may trigger additional reviews. There is also a scenario where a letter alone is insufficient. If you are dealing with a regulatory body or a formal audit, the receiving organization may require a sworn statement or notarized declaration in addition to the explanatory letter. I learned this the hard way during a compliance review for a small mortgage brokerage. We submitted six explanation letters without notarization and were asked to resubmit everything. That added seven business days. Always verify the submission requirements before you finalize the document. The bottom line is that an Explain Letter Sample is a tool, not a solution. It works well within its limits and fails quickly when you push it beyond them. Know what it is for, know what it is not for, and keep the letter short enough that the reader finishes it in under a minute.