What You Actually Pay for an Eye Exam
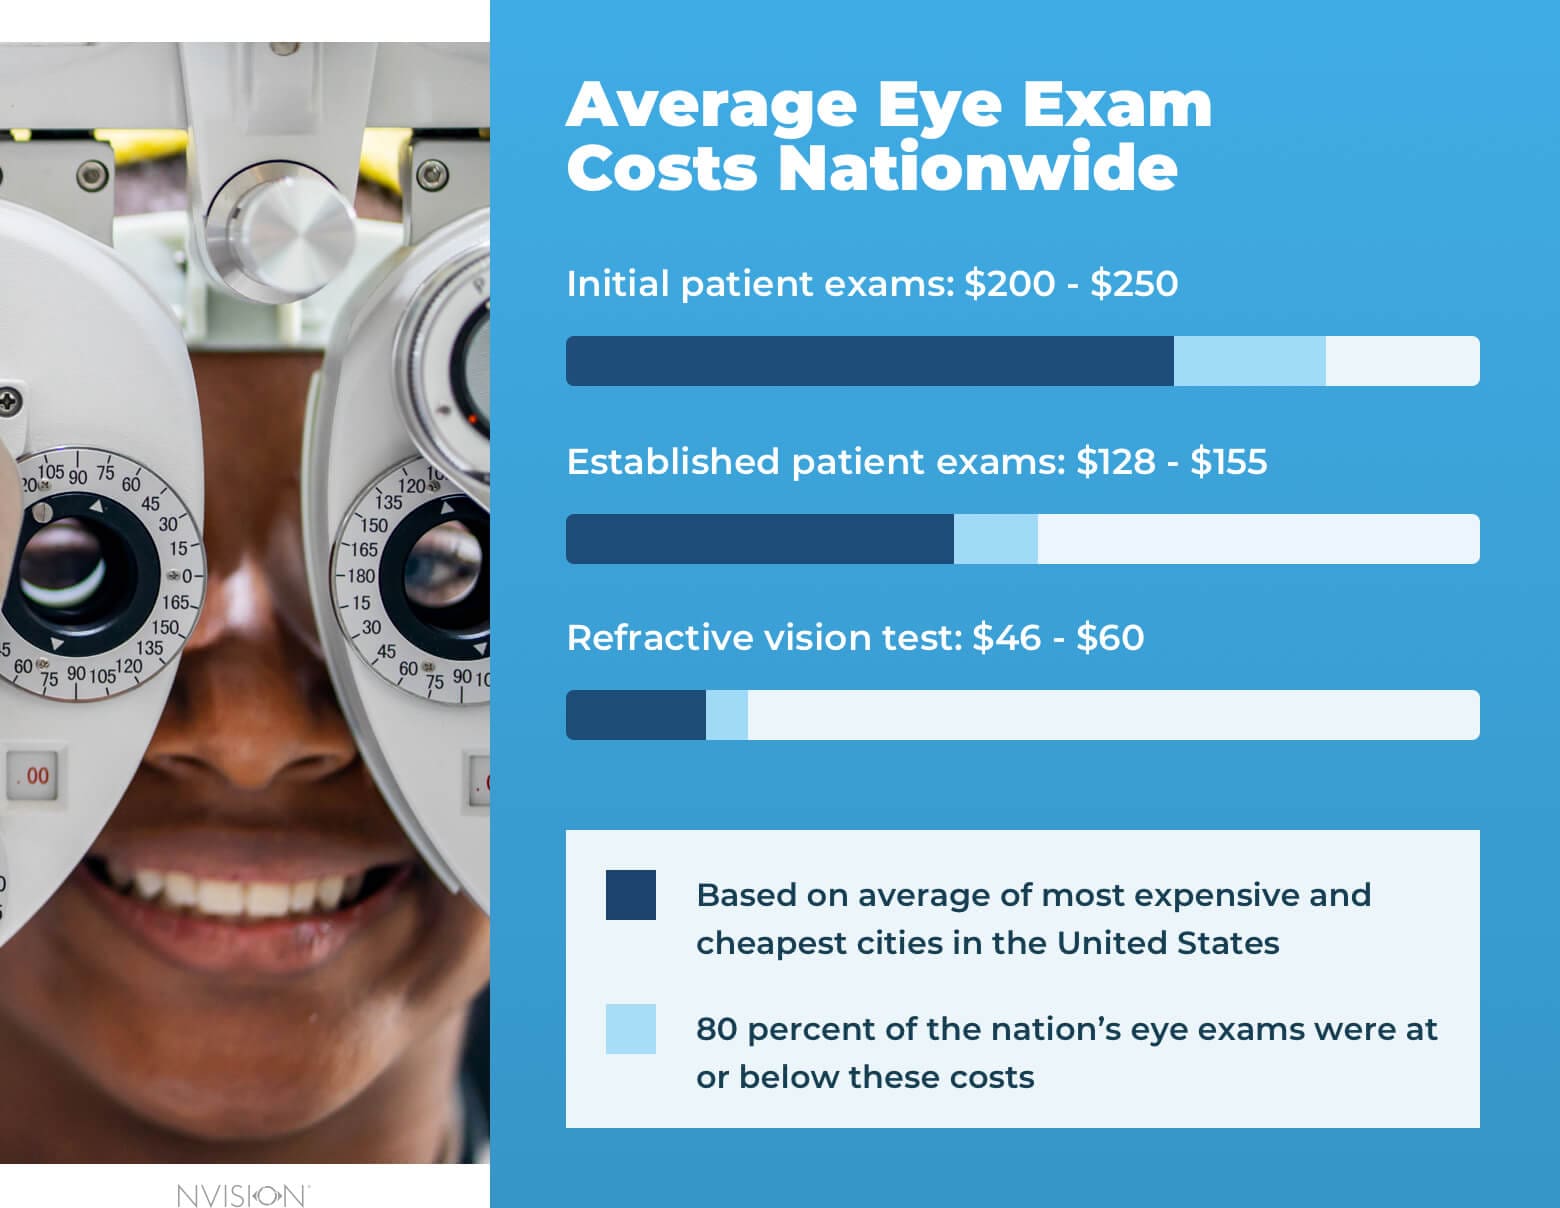
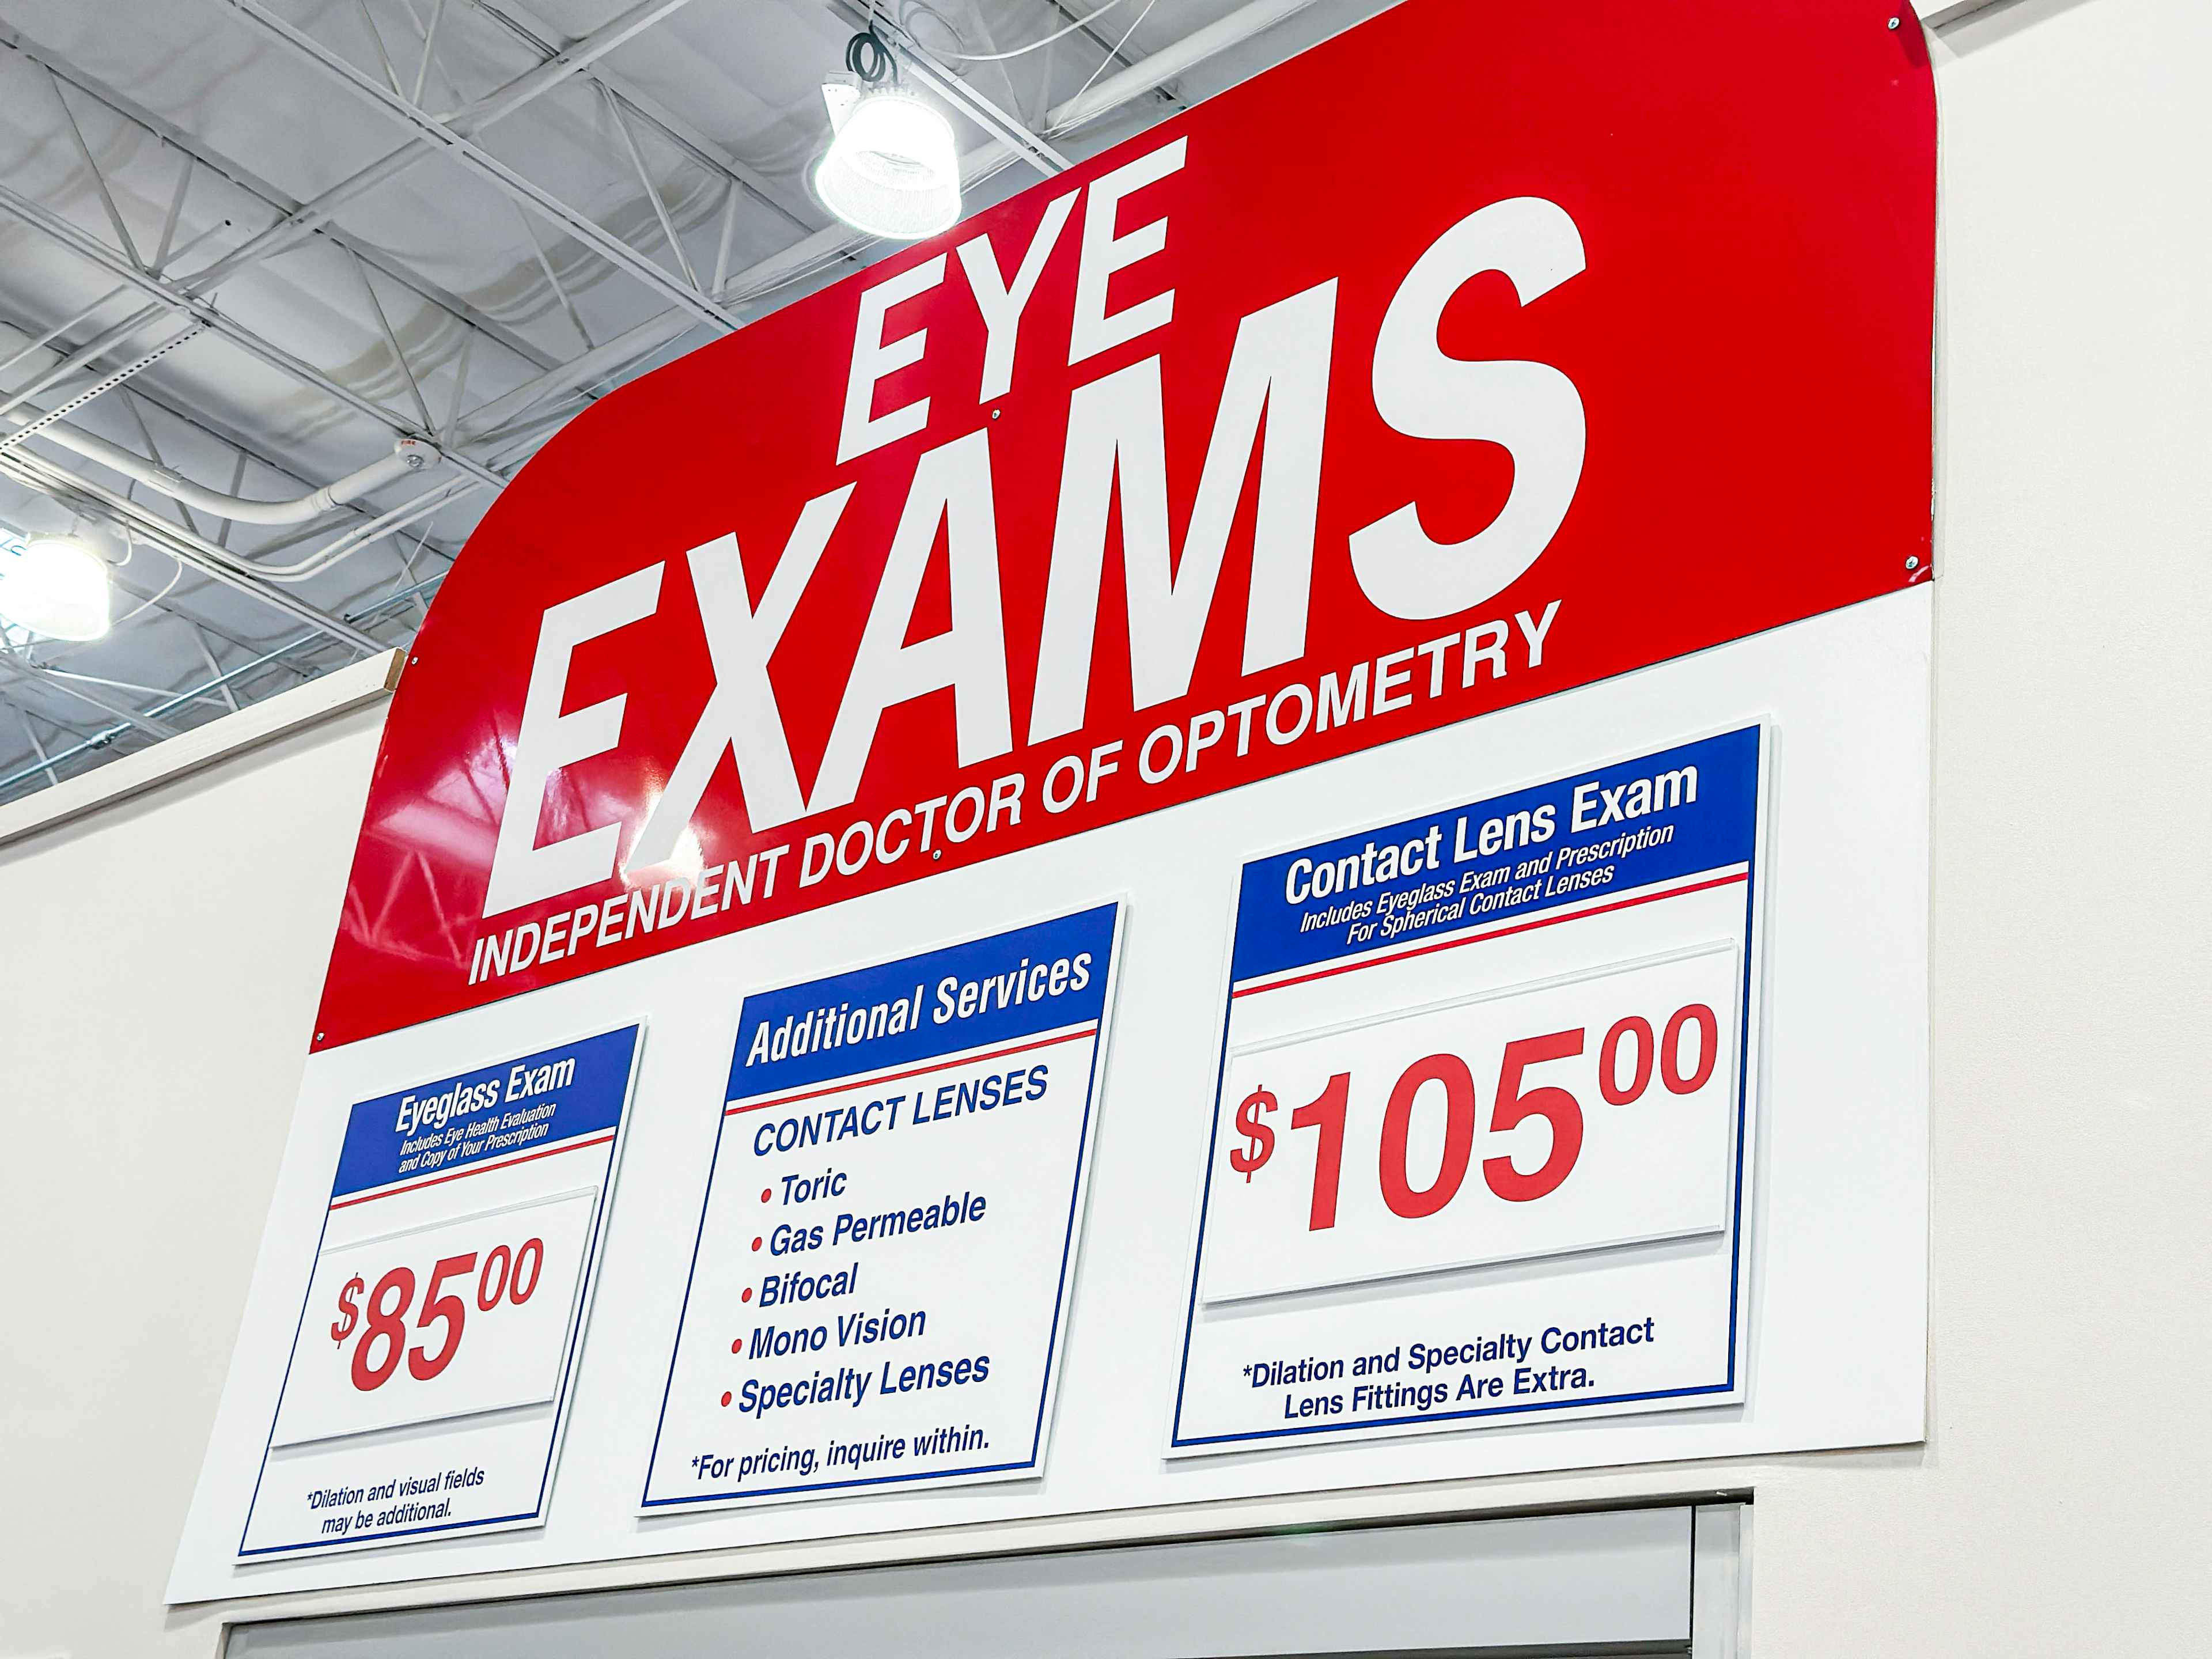
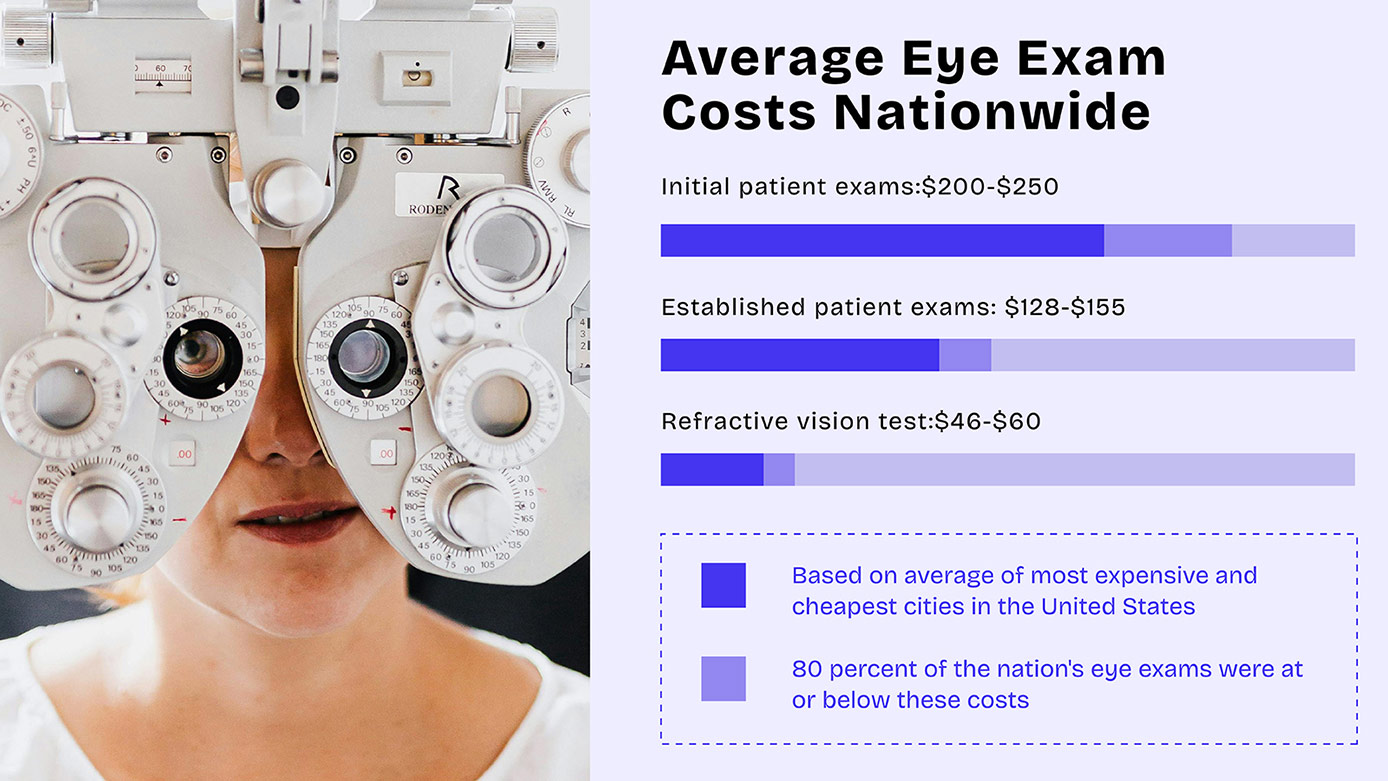
The Eye Exam Cost in the United States runs a weird range depending on who you are, where you live, and whether insurance touches the bill at all. A routine vision check without insurance will set you back anywhere from $50 to $200. That number jumps to $200–$500 if your optometrist needs to do a comprehensive dilated exam, and it can go even higher if you're seeing a ophthalmologist for something medical. I learned this the hard way in 2019 when my insurance told me an in-network plan would cover the exam but not the refraction. The difference between those two things is the key detail most people miss. The medical part — checking your eye health, looking at your retina, measuring pressure — that's what insurance usually covers. The refraction, which is the machine that tells you whether you need plus or minus numbers for your glasses, is often billed separately and not covered at all. That add-on ran me an extra $85 on top of an otherwise fully covered exam. If you don't have insurance, the pricing landscape shifts entirely. Retail optical places like Walmart and Costco tend to charge around $50 to $80 for a basic vision screening. Independent practices in cities like San Francisco or New York will quote $150 to $300 for the same thing. It's not about quality, really. It's about overhead and market pricing. But here's the practical move that most people don't know: call your local optometry offices and ask for their self-pay cash price for a comprehensive eye exam. Many will drop their sticker price by 20 to 40 percent if you say you're paying out of pocket. I once got a $280 exam quoted down to $165 just by asking, and no, nobody expected me to ask.
Eye Exam Cost: How Insurance Actually Works Here
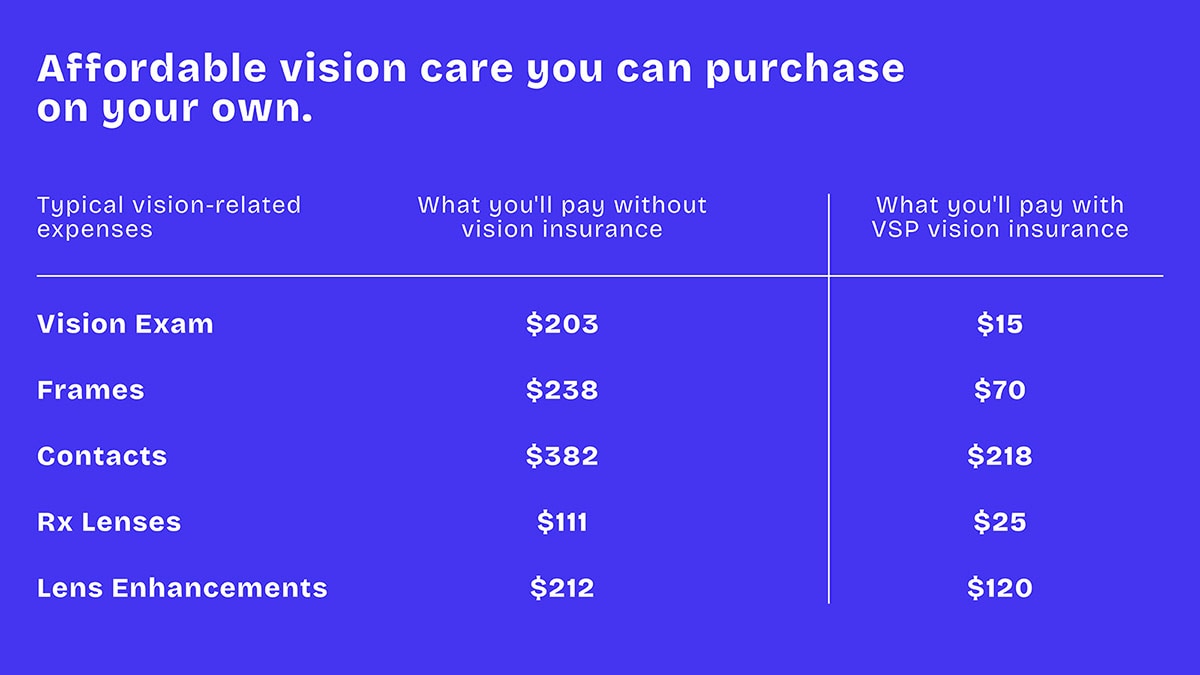
There are two completely separate insurance categories you need to understand before you walk into any clinic. Vision insurance and medical insurance. They are not interchangeable, and using the wrong one at check-in will result in a surprise bill. Vision insurance plans like VSP, EyeMed, and Good Eye typically cover one routine exam per year with little to no copay. Your copay might be $5 or $10. But these plans almost never cover dilation or any medical work. If your doctor dilates your pupils to look at the back of your eye and you're on vision-only insurance, you're paying for that exam under medical insurance, which means deductibles and coinsurance apply. I've seen people get hit with $300 bills for a standard diabetic follow-up because they didn't clarify which insurance to run first. Medical insurance covers eye exams when they're medically necessary. Diabetic retinopathy checks, glaucoma monitoring, post-surgical visits — those are all covered under medical. But a routine vision check for new glasses? Most medical plans won't touch that. They'll deny it outright. So if your only coverage is medical insurance and you need a standard eye exam, you're paying cash. There's no workaround for that unless you have a diagnosis code that justifies medical necessity.
One counter-intuitive thing about Eye Exam Cost that most people don't realize: Medicare covers eye exams, but only for specific conditions. If you're diabetic or have family history of glaucoma, Medicare Part B will cover a annual dilated eye exam. Otherwise, routine vision screenings are not covered. The American Academy of Ophthalmology notes this gap explicitly, and it's one of the most common sources of confusion I see in practice. Let me give you a realistic breakdown of what the numbers look like in different scenarios. Routine vision check with vision insurance: $0 to $20 out of pocket.
Get the Full Details
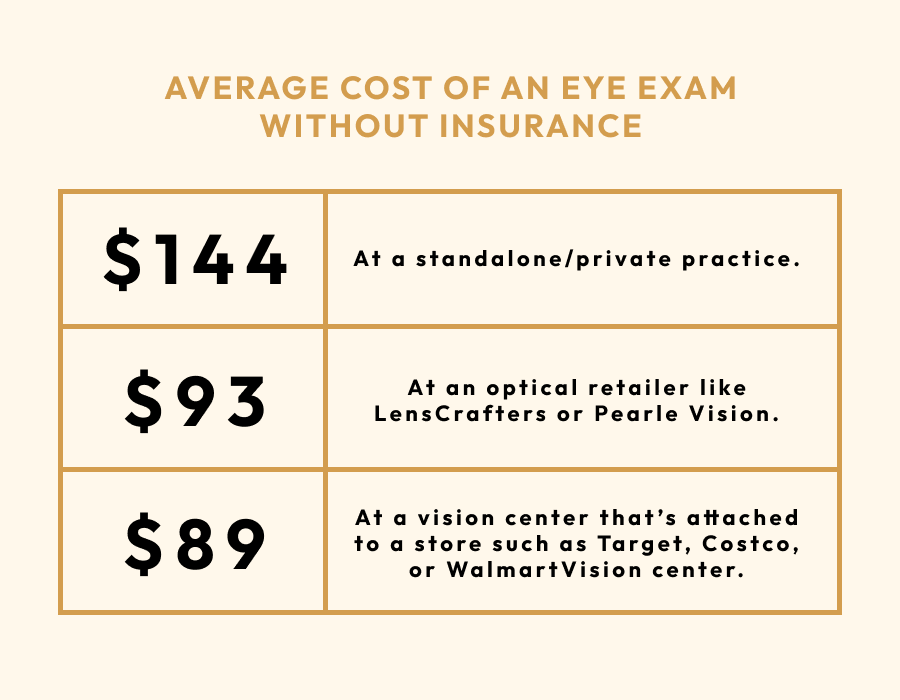
Comprehensive exam with vision insurance, refraction billed separately: $50 to $150. Self-pay comprehensive exam at an independent practice: $150 to $300. Self-pay at a retail chain: $50 to $100.
Medical eye exam with medical insurance, after deductible: depends entirely on your plan, but expect $200 to $500 before coinsurance kicks in. Ophthalmologist visit for a medical condition: $120 to $250 copay, or more if you haven't met your deductible. Here's the niche edge case I ran into last year that most cost guides won't mention. I was switching optometrists mid-year. The new practice wanted to repeat my comprehensive exam even though I'd had one eight months earlier at my old place. They wouldn't accept the previous records as a substitute. That meant paying full price for an exam I'd essentially already paid for. I called my old office and requested a records transfer, and the new office accepted a portion of it, but they still charged me for the new refraction and the updated prescription workup. The total was roughly $180, and honestly, it wasn't unreasonable. But it's the kind of hidden cost that catches people off guard when they switch providers.
Another thing worth knowing: contact lens fit exams are almost never included in a standard Eye Exam Cost. If you wear contacts, the initial fitting and follow-up visits can add $100 to $250 on top of your regular exam. Some vision plans bundle this, some don't. Check your summary of benefits before you schedule. I've seen people show up for what they thought was a routine visit and leave with a $200 balance because the contact lens fitting was itemized separately. The practical takeaway is straightforward. Call ahead, ask about self-pay discounts, clarify whether refraction is covered, and confirm which insurance to submit first. The pricing is opaque by design, and the only person who can navigate it is you. Nobody is going to volunteer that information at the front desk unless you push for it.