Why Most Deals Fall Apart Before Closing
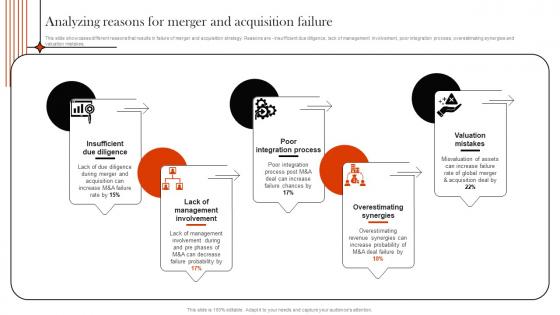
The numbers rarely tell the whole story. I spent years watching multi-million dollar acquisitions collapse not because the financials didn't work, but because people kept treating culture and operations as soft factors you could address after the ink dried. They can't. M&A failure doesn't usually look like the movies. It's not a dramatic boardroom argument. It's a slow bleed. Integration starts three weeks too late. Key talent walks. Systems don't talk to each other. Customer service drops. Revenue stagnates for two quarters straight. By the time anyone admits the deal is sick, it's already terminal. The actual process of evaluating whether a deal will survive integration should start during due diligence, not after signing. Most teams get this backwards. They focus on valuation multiples and synergies while ignoring whether the acquired company's ERP system can even connect to their own. That's like buying a house without checking the foundation. It works fine until it doesn't.
I once worked on a mid-market acquisition where the target used a completely different inventory management platform. Nobody in finance or IT caught it during the 60-day diligence window because they were too busy with revenue models. The deal closed. Then we spent eight months rebuilding their supply chain integration from scratch, which blew the post-close budget by roughly 340 percent. The workaround was brutal but straightforward: we temporarily isolated the target's distribution centers and routed everything through a middleware bridge we built in two weeks using existing AWS infrastructure. Cost roughly $180,000 instead of the $2.4 million it would have taken to fully rebuild. We still lost some senior ops people in the process, though. Not everyone came along for that ride.
The Real Reasons Deals Die
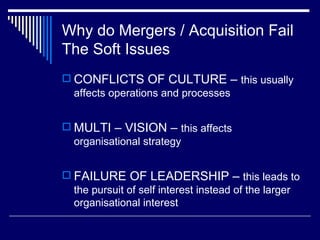
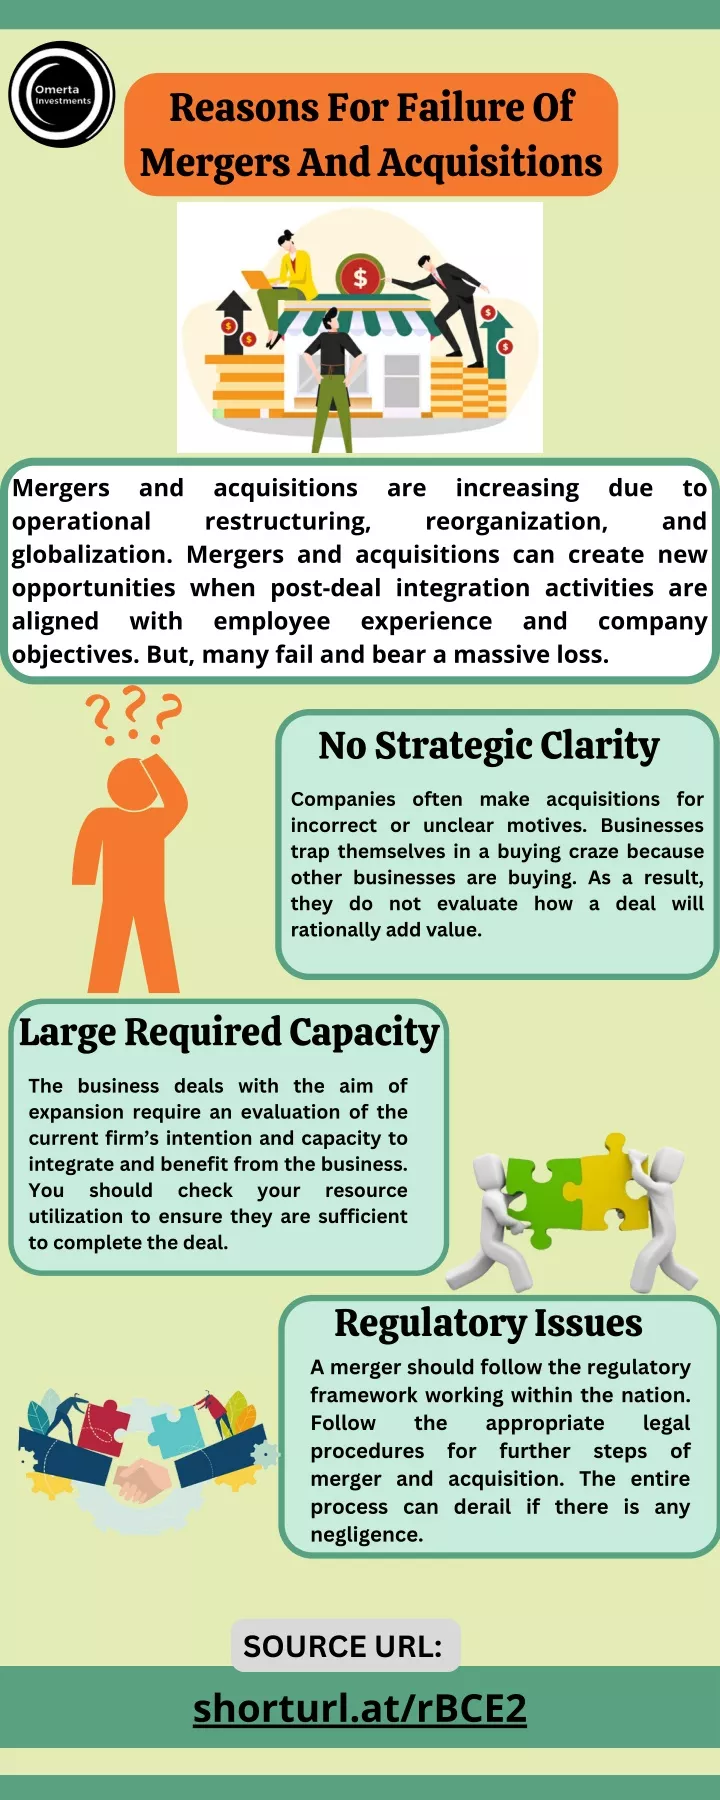
Culture clash gets thrown around like it's some vague HR problem. It isn't. When two companies merge and one has a flat hierarchy where decisions happen over Slack and the other runs on approval chains and quarterly reviews, the friction shows up in missed deadlines, stalled projects, and people quietly updating their LinkedIn profiles. I've seen it kill deals faster than any financial discrepancy. Pricing synergy assumptions are another quiet killer. That projection saying you'll save $12 million by combining procurement? Yeah, good luck with that. Vendor contracts have lock-in periods. Volume discounts get renegotiated downward when purchasing power actually consolidates. Supply chain rerouting takes longer than anyone estimates. The typical gap between projected and realized synergies sits around 40 to 60 percent in mid-market deals. That's not a typo. Retaining key talent post-close should be the single highest priority after day one. Not rebranding. Not office moves. The people who actually know how everything works in the acquired company. You offer retention bonuses. You make them stick around. If you wait until after integration begins to figure out who matters, you've already lost them. Turnover among critical roles within the first six months routinely hits 25 to 40 percent if you don't have a concrete plan written before close.
Get the Full Details
What Actually Works During Integration
Start with a combined integration team on day zero. Not a project management office that reports up through layers. People from both sides who have authority to make decisions without escalation. This changes the timeline dramatically. Instead of waiting two weeks for approval on basic operational decisions, you're resolving them same day. The first 100 days matter more than the full year. I've seen integrations where the first 48 hours were a complete mess because nobody had figured out who controlled what systems, who had access to financial data, or which email aliases were active. You need a contact tree, not an org chart. Org charts lie about who actually makes things happen. Communicate early and often to both workforces. Silence creates speculation. Speculation creates panic. Panic creates turnover. Regular updates, even when there's nothing new to say, beat silence every time. I learned this the hard way when a quiet two-week period during a mid-size deal triggered a rumor mill that cost us three senior engineers before we got it together.
Set measurable milestones. Not vague goals like improve collaboration. Revenue targets, retention percentages, system migration completion dates. If you can't measure it, you can't manage it. Track progress weekly through the first quarter, then shift to biweekly once the dust settles. The difference between tracking and not tracking usually separates deals that hit integration targets from ones that don't.
When To Walk Away
Sometimes the best move is not to close. If due diligence reveals structural incompatibilities that would take two years and serious capital to fix, and the deal's value proposition relies on those fixes happening within 18 months, the math simply doesn't work. I've seen executives push through deals anyway because the alternative looked bad on paper. It always comes back to hurt them worse later. Patience in negotiations matters more than speed. A deal done poorly takes twice as long and costs three times as much as a deal done right. The syndication and diligence process alone can eat six to nine months. Rushing that window to meet an arbitrary timeline usually means skipping the checks that would have caught the problems in the first place. We're talking about scenarios where the target company's customer base has a 30 percent churn rate that wasn't disclosed, or where regulatory approval is virtually guaranteed but takes eight months instead of the four estimated in your model. Those aren't edge cases. They happen regularly. The hard truth is that most M&A literature tells you to optimize for valuation. In practice, the deals that survive are the ones where someone actually sat down and mapped out what day one looks like before the paperwork is even signed. Everything else is just optimism dressed up as strategy.